

Investor. Small cap asia, tech, monopolies, semi’s
Joined July 2022
- Tweets1.6K
- Following429
- Followers1.8K
- Likes2.7K





First Hill Capital retweeted

The value of Terafab’s output will place it in the top 20 of country GDP in a single building

According to Korean media, Elon Musk's Terafab is now talking to almost EVERY Korean chip supplier it can find.
Until now, the only known Korean suppliers were HPSP and Hanmi Semiconductor.
Now TheElec reports that Tesla and SpaceX are in talks across nearly every category Korean companies can supply, from basic piping parts to process materials to test components.
At SEMICON West in San Francisco last week, Terafab staff walked straight to around 10 Korean booths on the morning of day one, including ENF Technology, Dongjin Semichem, Hanmi Semiconductor, Unisem and MiCo.
Several companies have already signed NDAs. One got an NDA by email the same evening Terafab visited its booth.
Hanmi Semiconductor is discussing TC bonders for Terafab, and HPSP has agreed to supply one high pressure hydrogen annealing tool to the R&D line.
MiCo's cleaning unit Komico signed a three way NDA with Tesla and SpaceX about a month ago, and ISC is already swapping samples for rubber test sockets.
Tesla and SpaceX do not buy from Chinese suppliers. One Korean supplier put it simply, without China there are only a few options, and Japan is expensive.
They also want prices that are CHEAPER than China.
$LRCX and $AMAT have reportedly built dedicated Terafab teams, and Fujifilm is meeting Terafab buyers regularly on slurries, photoresist and etchants.
The goal is a fab with 1 million wafer starts per month within 10 years, with $16.8 billion of initial investment and more than 3,000 jobs.
SpaceX broke ground in Grimes County, Texas this month, and the first 100,000 wafer per month phase is expected before 2030.
Logic is being done with $INTC, talks with $TSM are ongoing, and memory will be built separately.
One supplier said that if they email Terafab in the middle of the night in the United States, they get an answer in 30 minutes to an hour.
$TSLA and $SPCX are building a chip supply chain at Elon speed.


Just wait until you invest in Korea 😂

Its kind of interesting that my portfolio is pretty polar opposite, my US investments are all Mag 7 and DRAM, and the rest is foreign.
I didn't consciously try not to have small mid cap exposure in the US, but here we are.
Am I being too doomer, what are the best opportunities in the US besides $GOOG, $META?
I definitely think regional banks but I have a rule against investing in banks, I need to learn more about them.
Yep, if you through enough money at the problem
xitter.cf/firsthillcap/status/21…

This is a really interesting chart.
I attended the TrendForce San Francisco roadshow yesterday, and this chart got me thinking about a lot of things.
China is now expected to localize more than half, or close to half, of most equipment categories, excluding lithography and track.
What does this mean? It means China can now expand mature node capacity far more easily than before, using equipment made domestically within China.
Mature node foundries are booming right now, right? That's thanks to the AI supercycle driving demand for PMICs, power semiconductors, and so on.
Samsung and TSMC shutting down their mature node capacity has also helped a lot.
But here's what I imagine... that China could oversupply mature foundry capacity.
Think about it. If China can be self sufficient in equipment, there's no limit to how far it can expand capacity. Then are companies like TI, with large revenue exposure to China, really safe?
I think it's time to take another look at Western mature foundry companies with a high share of China revenue.
Of course, I'm not saying sell TI right now. I'm just saying we should think about whether it makes sense to hold them for 10 years or more, like Coca Cola.
If you have a different view, please feel free to share it. I’d love to learn.

As a sales guy I can go from meeting record -> CRM notes -> Follow up emails, tasks, deal updates in one go.
Opus 5.5 is the first model that was capable of writing decent sales emails
AND I can vibe code custom apps for presentations


First Hill Capital retweeted

text-to-cad just crossed 20,000 stars on github!
here's a lightning talk i gave about it at frontiers, enjoy
Big fumble missing IBKR. I think their software is so shit that I had a mental blocker to look at it
Death, taxes, and $IBKR growing accounts at 30%+
(EPS was weaker this quarter due to lower trading volume/commission revenue + "Other income" dropped as well)

Even in 2028 we can't predict what the demand for DRAM will be. We can extrapolate AI in the way we currently use it TODAY, but by then we're going to be using it in other ways.
Most importantly it could be one of the first years the main demand driver is PHYSICAL AI not digital AI. No one is forecasting DRAM demand from robotaxi's + Humanoids.
Plus China demand truly coming online 2028-2029 digital + physical

I'd like to add that some WFE revenue is going to be way ahead of the fab construction, some during, and some after.
Reclaimed wafer boom is only going to happen once the fabs get rolling with production and recurring AT THAT RATE going forward
It's not going to be lumpy like the equipment sales


The Reclaimed wafer industry is entering a demand boom as TSMC and others demand higher throughput of wafers per month and prime wafer supply shortens.
Below is a comparison of 4 major public wafer reclaim providers

Really easy fix here lets see what happens lol

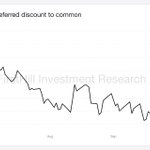
SK HYNIX SHARES TRADE AT A 40% PREMIUM IN THE U.S. THE LOCKUP JUST EXPIRED.
TIL: SK Hynix's 90-day ADR lockup expired October 7, opening the door to additional U.S. share issuance.
Its Nasdaq-listed ADRs are trading at a 40.4% premium to the underlying shares in Seoul.
SK Hynix hasn't announced any new issuance yet. But with Q3 earnings coming later this month, investors are watching for a possible move to narrow that gap...
[Get more breaking semiconductor news straight from Korea and around the world, on Antfeed]
#SKHynix #ADR #Nasdaq #KoreanStocks #Semiconductors #메모리반도체 #HBM #DRAM #낸드 #MemoryChips $SKHY $000660 $005930 $MU $NVDA solana:5XqMbyZbtse5UQUzgrYMpeWLWLR6BWFqUm5H3VAWpump $SOXX $DRAM $RAM $EWY $KORU

I'm very curious about how much this translates down the supply chain to the tiny suppliers in Japan and Korea.
Like is the CMP slurry spot price up 100% too??
Probably not but you get the point.

Open-weight models that decrease margins at the model layer are positive for AI infra, exhibit 1001.2
Since the @silicondata “token index,” which captures both price and mix, peaked on May 31:
B300 prices are up 38%
B200 prices are up 10%
Other GPU indices are up *much* more.
