

The microcap index focused on quality+value+momentum at growth inflection points (MSMqi) supported by Cliff Notes & tools: https://xitter.cf/t.co/xH7cRPUNOQ
Joined November 2023
- Tweets1.2K
- Following94
- Followers4.9K
- Likes1.6K





Pinned Tweet
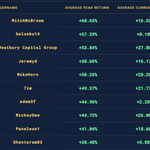
🏆 The Stock Picking Contest leaderboard is LIVE!
Current Top 10:
🥇 MitchMcBroom | belzebu14 | @WestCapGrp | @DillerJeremy | MikeHorn | @sdrinkingmiller | @adamturner21 | @twoparadox | @paneless1 | @shantaram83
Pre-register for phase 2 or view rankings: investingcontest.net/

Our next virtual conference is here: October 27.
Four companies and one investor pitch. Stay tuned for details. Special appearances by @bmb21 @MicrocapDr @Diego_La_Torre_
MSmicrocaps retweeted

Plenty of boring stocks approaching 52 week highs in the @MSmicrocaps Index - as the mini correction in tech and AI dominates headlines.
🇺🇸 $SCIA $MG $AMNF $FACO $BUKS $KRT $RCEL
🇨🇦 $FTG.TO $OML.V $BRM.V
$MG merger arb is interesting. $SCIA is quietly inching higher.
@leevalueroach likes $BUKS
@bmb21 likes $AMNF
@Atrium_Research likes the 🇨🇦 lineup
@Diego_La_Torre_ likes $OML $BRM $BUKS
Make sure to follow all four of these very talented investors.

MSmicrocaps retweeted

Just added two more @InfoArbMonitor hot button news monitors to help expedite and curate research👇
•Smart Capital Allocators - like $FTG.TO $SODI $PXHI $ITRN
•Zombie Index (shit cos) - too many to list, but hopefully they’re not in your portfolio or heavily weighted 🤐

We just dropped a Beta feature at @InfoArbMonitor - Curated lists that we call monitors. Think of these as hot buttons to help you bypass the junk and focus on press releases based on themes, categories, topics… etc. We just added @Atrium_Research's coverage universe.

We’ve been working through MSMqi stocks by conviction, from High to Mid and now Low. Part 2 of our Low Conviction series is out, covering what we like about each name and what would need to change for our conviction to rise.
Read the full breakdown here: mscliffnotes.substack.com/p/…
Paid subscribers also get our live dashboard, which sorts every name by conviction, theme and industry, with P/E ratios, weekly movers and a running log of every upgrade and downgrade.
We're building a curated smaller-cap hunting ground, like no other, for serious investors who want more than just the next "pick." We're a little biased, but our Substack has become perfect place for quality focused investors/authors to hunt for ideas during market sloppiness, like what's currently going on in certain corners. Thanks for all the support that is making this possible. We won't let you down.

MSmicrocaps retweeted
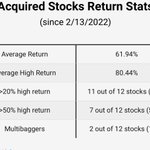
Four years in, and we’re starting to get some good KPI‘s on the MSMqi.
Remember, these are passive indexes to show that you can earn some nice returns by just being in the right curated universe. The challenge is trying to use active Mgmt. to improve returns or screw it up lol

Our September letter is ready. Our Microcap Quality indexes include 153 stocks across two passive indexes to help you hunt for Cos. hitting multibagger markers:
•2025 Index: YTD 23.8% CAGR 34%
•2022 Index: YTD 26.4% CAGR 19.6%
•YTD NASDAQ, S&P, Russell 2K: 15.6% 12.1% 17.4%


MSmicrocaps retweeted
Rely less on FUD headlines like the Open AI revenue miss BS and more on facts.
Facts from $III 👉 Regarding spending on infrastructure services👇
“The AI infrastructure boom is still accelerating,” said Steve Hall, ISG’s chief AI officer and leader of the ISG Index. “The hyperscalers continue to post strong growth and are committing extraordinary levels of capital to new capacity. While supply is growing, this is definitely a demand-driven market. Providers are continuing to build because enterprise demand for compute, storage and AI capacity remains exceptionally strong. The implication is the infrastructure cycle still has room to run. We are not yet seeing a clear peak.”
“It was the highest quarterly growth rate for the combined market ever recorded by ISG, and the ninth consecutive quarter the market grew by double-digits versus the prior year.”
monitor.infoarb.io/news-feed…
$FTGFF $FTG.TO just delivered blowout Q3 results
FTG CEO Brad Bourne joined our conferences twice:
Mar 2025: mscliffnotes.substack.com/p/…
Oct 2025: mscliffnotes.substack.com/p/…
Up 550%+ since adding to MSMqi. Aerospace/defense, up the value-chain & margin expansion thesis playing out.


MSmicrocaps retweeted
$FEIM (defense) was a great example of this. Not only was backlog growing, it was replacing sub 30% gross margin backlog with over 40% GM. You had all day to buy the stock between $8 & $15 in 2024. Now it’s pushing $100. $SIF (defense) might be approaching that type of set-up.

MSmicrocaps retweeted

$VCM.TO — Breakout Q4: record revenue up 36% to C$91M, EBITDA more than tripled to C$18.9M. Gross margin jumped from 26% to 45%. EPS swung from a C$0.55 loss to C$0.22 profit.
Guided FY2027 revenue growth of 30-35% with ~20% EBITDA margins. Trading at 7.1x FY+1 P/E. Mgmt says their newer software products are barely included in guidance and could be a bigger driver in 2028+.

MSmicrocaps retweeted
$NTWK - Some InfoArb Delta Sheet findings have implications for future recurring revenue.
NTWK provides software to the global asset finance & leasing industry and just reported a very strong quarter.
Historically, results have been inconsistent due to lumpy implementation and services revenue. But this also helps feed future recurring revenue. Still, the quarter is hard to trust at face value.
The opportunity: grow the recurring base enough to create a higher earnings floor, while layering services revenue on top. So far, recurring revenue has been relatively steady rather than a meaningful growth driver. Recurring revenue hints👇

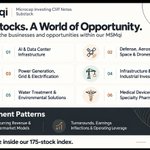
Our Microcap Quality Index platform now has 175 stocks, giving us a diverse cross-section of businesses through which to follow major trends and uncover opportunities in companies many investors have never heard of. This is just a glimpse of what’s inside the index.

MSmicrocaps retweeted

just pointing out that when this post dropped, $OCC was trading at about $12, now $18.37
MSmicrocaps retweeted
$TAYD (Shock Absorption & Damping Devices): Don't look at Q4 revenue, down 42% to $9M due to delayed order timing. Look at the backlog: record $52.8M, up 60% from the prior record of $33.1M. 92% is Aerospace & Defense.
Includes a single company-record $19M order. We're trying to determine if the ramp is tied to missile programs like THAAD, which is expected to see significant spending increases. Haven't confirmed yet.

We’ll be adding another stock to our microcap quality index this weekend. We love infrastructure stocks going through a margin up-cycle, as they layer on recurring revenue from service and maintenance contracts. This is where you see crazy multiple expansion. Here’s an an excerpt from the research that will accompany the stock’s addition to the index👇
“Many industrial companies make most of their money selling machines; the more profitable ones keep earning after the sale, from the parts, service, and repairs those machines need for decades. This century-old heavy equipment maker is in the middle of that shift, and so far it’s working: its aftermarket business, made up of parts, service, used equipment, and rentals, earns roughly three times the gross margin of new machines, has grown rapidly, and is now ahead of management’s own targets.
The rest of the business hasn’t caught up yet. Despite being one of the leaders in its industry, the company’s margins sit near the lowest level in years, leading to the opportunity we see here. Management has laid out a plan to double EBITDA margins without needing much growth, and if it gets there, our estimates show EPS rising more than 4x by 2030.