

Earnings insights for US & Canadian micro- & small-caps (less than $2B mkt cap). By @majgeoinvesting & @SebKrog
Joined January 2026
- Tweets142
- Following58
- Followers1.2K
- Likes146
EPSMonitor retweeted

Get ready for the third-quarter small and microcap earnings season. Many stocks with great earnings reports have pulled back during the last few weeks. That’s precisely the time to be more aggressive in research, when some people have temporarily given up.

Every month @SebKrog & @majgeoinvesting hold a live virtual event, going over the best and most interesting smaller-cap earnings reports during the last few weeks, as well review past reports getting more of our attention. Learn more at our Substack - where events are archived.

Every month @SebKrog & @majgeoinvesting hold a live virtual event, going over the best and most interesting smaller-cap earnings reports during the last few weeks, as well review past reports getting more of our attention. Learn more at our Substack - where events are archived.
$GG.V — Debt-free gold miner, and insiders own ~42%. The negatives are that they'll likely miss their 2026 Galaxy target, and the Summit restart has slipped to Oct/Nov.
But both mines are ramping toward ~40k oz by 2028, up from ~20k this year. At $4,300 gold, mgmt's model shows FCF reaching US$56M in 2028 vs. a US$143M market cap. We'd push the production targets back a year, but the cash flow is still there.

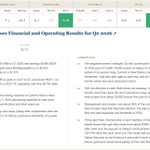
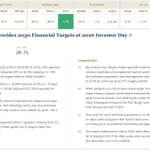
$ROG — Big investor day. Mgmt targets $1.5B in revenue and $14 adjusted EPS by 2030, up from $2.39 adjusted EPS in 2025, all organic.
The AI angle: they're testing circuit board materials for AI servers and liquid chip coolers with major players. First design wins are expected within 2 quarters.

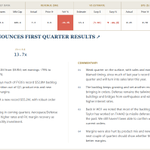
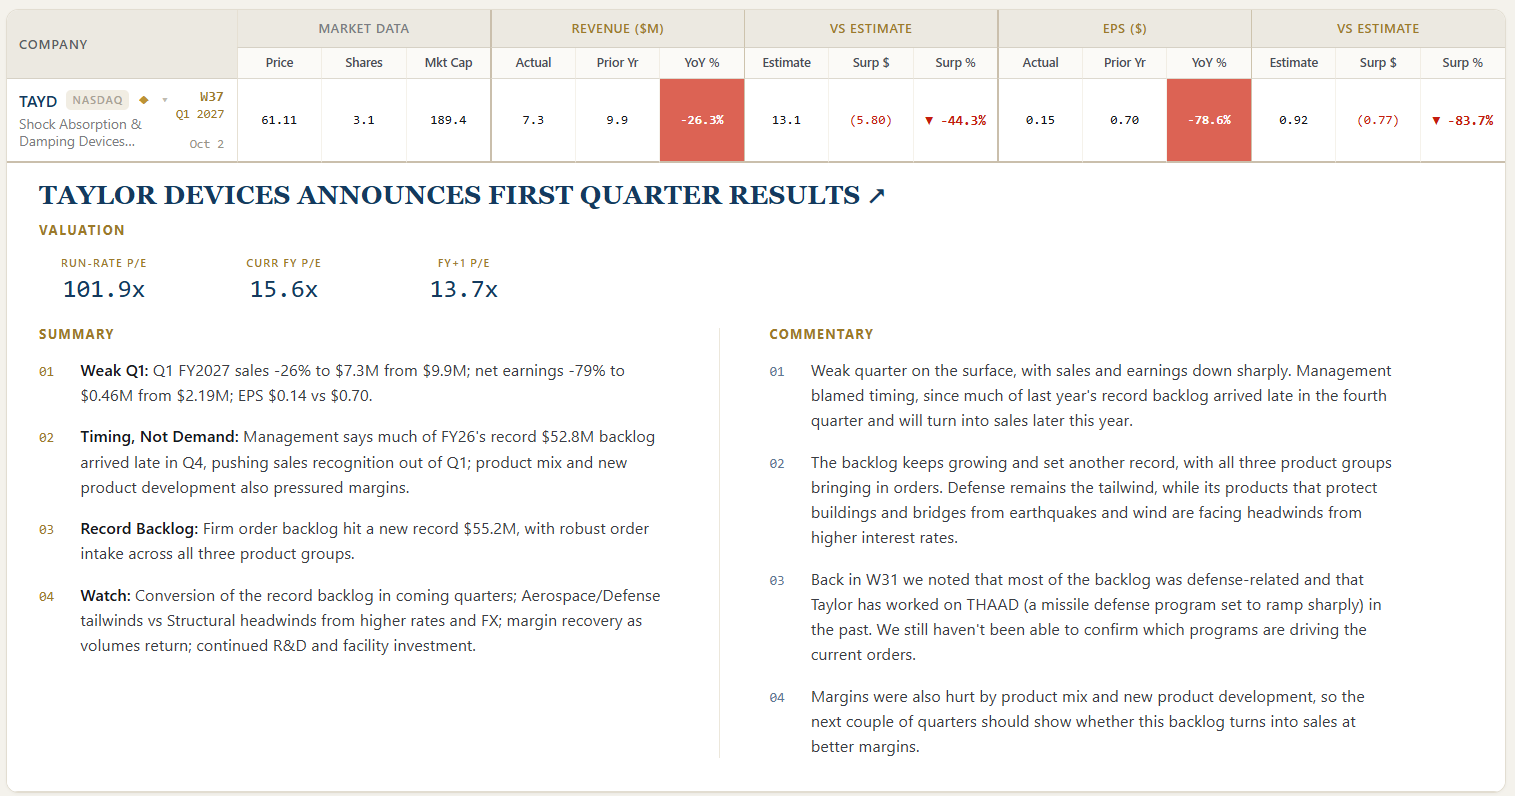
$TAYD Weak Q1 on the surface: sales down 26% to $7.3M, EPS $0.14 vs $0.70. Mgmt blamed timing, since much of last year's backlog arrived late in Q4.
The backlog keeps growing and hit another record at $55.2M, mostly defense. We still haven't confirmed which programs are driving it.
EPSMonitor retweeted
At first glance, this one looks really interesting. Worth diving into. I’ll be spending lots of time going through these earnings cards on @EPSMonitor, ahead of the third-quarter small and microcap earnings season.
$VCM.TO — Breakout Q4: record revenue up 36% to C$91M, EBITDA more than tripled to C$18.9M. Gross margin jumped from 26% to 45%. EPS swung from a C$0.55 loss to C$0.22 profit.
Guided FY2027 revenue growth of 30-35% with ~20% EBITDA margins. Trading at 7.1x FY+1 P/E. Mgmt says their newer software products are barely included in guidance and could be a bigger driver in 2028+.

$TAYD (Shock Absorption & Damping Devices): Don't look at Q4 revenue, down 42% to $9M due to delayed order timing. Look at the backlog: record $52.8M, up 60% from the prior record of $33.1M. 92% is Aerospace & Defense.
Includes a single company-record $19M order. We're trying to determine if the ramp is tied to missile programs like THAAD, which is expected to see significant spending increases. Haven't confirmed yet.

$VCM.TO — Breakout Q4: record revenue up 36% to C$91M, EBITDA more than tripled to C$18.9M. Gross margin jumped from 26% to 45%. EPS swung from a C$0.55 loss to C$0.22 profit.
Guided FY2027 revenue growth of 30-35% with ~20% EBITDA margins. Trading at 7.1x FY+1 P/E. Mgmt says their newer software products are barely included in guidance and could be a bigger driver in 2028+.
$WEBC — FY2026 sales up 15% to $671M, net income nearly doubled to $26.50/share. Gross margins improved. The company has data center exposure, but the filings don't break out end markets, so we can't tell yet how much growth is coming from there.
Cash flow is the weak spot; it turned negative as inventory built up with rapid growth.

Weekly Earnings Brief #36 is out: $NNBR, $WEBC, and others.
$NNBR - Third guidance raise this year. FY2026 sales now US$470-490M (+14%), EBITDA US$58-68M (+29%). EBITDA is growing 2x faster than sales as new wins ramp: NVIDIA liquid-cooling parts, robotic-surgery components, and others.
Data Center & Grid on track to become the company's biggest market. Mgmt targeting $120M near-term with 14-16% EBITDA margins.
$HITI (Cannabis Retail Chain): Record Q3: revenue up 33% to C$198.8M, the fastest growth in 13 quarters. Adjusted EBITDA up 53% to C$16.2M, hitting a 12-quarter high margin of 8.2%. Record operating cash flow of C$11.9M.
Canna Cabana is now Canada's largest cannabis chain at 232 stores with 14% market share. Germany's Remexian distributed a record 10.2 tonnes, up 62%, and holds 10% of the German market. Cabana Club loyalty membership at 2.73M.
The company targets C$1B in revenue and ~C$126M in EBITDA, with Germany as a major growth driver. Trading at ~5.6x 2027 EBITDA. Ian Cassel is closely following the stock.

$CODA (Subsea Imaging Sonar): Q3 revenue up 9% to $7.7M, EPS $0.12. Core Marine Technology actually declined 15% on Iran-related procurement delays, but Defense Engineering Services surged 68%, and Acoustic Sensors grew 10%.
The bull case is compelling: DAVD technology for the Navy, sonars for unmanned underwater vehicles, 65% gross margins, $31.7M cash with zero debt. A prime customer just won a multi-year US Navy repair/sustainment contract.
The caveat is that management has consistently overpromised and underdelivered countless times on commercializing these opportunities.

Weekly Earnings Brief #35 is out: $RFIL, $CODA, $HITI, and others.
$RFIL (Cable & Connector Manufacturer): RFIL is deliberately shifting from cyclical wireless-carrier work toward custom cabling and integrated systems for aerospace, edge data centers, AI infrastructure, and public safety. Higher engineering content, stickier relationships, better margins.
The other angle: their DAC (Direct Air Cooling) segment is approaching ~$10M in sales. We have evidence suggesting DAC carries higher margins than the rest of the business, which should lift overall profitability as it scales.
Backlog is at $18.6M on $22.5M in Q3 bookings. Mgmt expects continued operating leverage as revenue scales above the $20M quarterly run-rate.

$OCC (Fiber Optic Cable Manufacturer) — Q3 revenue up 22% to $24.3M. Revenue grew 22%, but gross profit rose 44%, and earnings grew even faster, textbook operating leverage.
Growth across enterprise, data center, and specialty markets. Domestic +20%, international +29%. Backlog up 82% from fiscal year-end to $13.5M. Swung from a $1.5M YTD loss to $2.5M net income.
Mgmt is now looking to expand capacity for certain products at certain facilities. Demand is described as robust.

$PPIH (Industrial Piping Systems) — Q2 revenue up 24% to $59.6M. Backlog at $142.3M with $67M+ in Q2 awards, including its first MENA critical-cooling infrastructure contract.
Mgmt expects 40-50% of backlog to convert next quarter, implying US$57-71M in revenue; the midpoint would be a company record. Project pipeline exceeds $900M, more than 6x current backlog. The new $139M facility now allows them to bid on $100M+ projects for the first time.
Gross margin dipped to 29.2% due to Ohio and Qatar ramp-up costs. We think a return to 30-35% is reasonable as one-off costs roll off and volumes grow.

Weekly Earnings Brief #34 is out — $FEIM, $PPIH, $OCC, and others.
$FEIM (Precision Timing & Frequency Electronics): Record Q1: revenue up 70% to $23.5M, EPS of $0.41 vs $0.07 a year ago. Operating margin exceeded 22%. Record funded backlog of $129M, up 82% YoY.
FEIM is a missile replenishment beneficiary, involved in PAC-3 & THAAD and now bidding on components that go directly onto missiles. The 2027 defense budget proposes ~10x increases in PAC-3 & THAAD procurement, with production tripling and quadrupling by 2030.
Caveat: FEIM is known for lumpy quarters. Expect a bad one eventually.

$YTY.V Wi2Wi posted Q2 revenue up 59% to $2.3M, swinging to $251K net income from a $653K loss. Gross margin went from -5% to 37%.
New CEO Sue has been executing a textbook turnaround: price increases the company hadn't implemented in years, resolved quality issues, and raised flagship yield above 30%. New advanced equipment will be operational by Q4 2026 for capacity expansion.
There are strong reasons to believe they are a beneficiary of the US missile replenishment cycle. We are watching this stock closely.
