





@Globalflows, any concerns with the HYPE unlock on June 6th killing momentum and the squeeze thesis?
ً retweeted

Sidoti raises $PBI price target to $20:
portal.sidoti.com/pdf/F74E91…

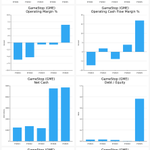
$GME shrank hard, closed stores, and diluted holders, but margins, cash flow, and net cash improved. It's now an allocator story as @michaeljburry pointed out.

Not at the enterprise level but I do get packages sorted by them quite often. Their API (as an engineer with experience using FedEx & UPS) seems quite robust and a great solution for multi-carrier/courier management & pricing.
ً retweeted

$PBI has bought back 16% of their shares in the last 6 months. $350m FCF and about 150m shares left.
ً retweeted

Love this mental framework ..

I started my career during the throes of the GFC crisis, working on CDOs / CLOs / RMBS / CMBS.
This gave me one of my earliest mental models, which I light-heartedly call “everything is bond math” - the ability to see that most financial assets with streams of cash flows are simply bonds in disguise.
It’s proved useful for me. Let me share a few observations:
🧵1/8:
I think your math is off...
Core FCF = $225M TTM + $159M bank outflow = $384M
Easily funds $252M buybacks + $46M divs.
Debt DOWN $7M net
ً retweeted

Finally got around to reviewing $PBI... more interesting than I thought...
1) An "everything" special sit - activist, mgmt change, GoodCo/BadCo, divestiture, early innings capital allocation inflection, and dash of public LBO
2) Exited money-losing segment in 2024 paving way for cash generation + capital allocation
3) Repaid ~$1.9bn debt (gross) from 2017-1H25
4) Activist investor stepped in as CEO in May 2025 with plans to ramp capital allocation... shareholder friendly comp package (low base + options at $12-16/sh)
5) GoodCo/BadCo setup - BadCo is larger & more profitable, declining 2-3% w/ stable earnings; GoodCo growing 3-4% (see table)
6) FCF (ex-divestiture) ramping from $150m to $200m and now $330m+
7) Early innings capital allocation inflection - buybacks started April 2025, already at 6% of market cap and auth = ~13% of cap
8) Valuation very reasonable = $2.1bn mcap / $3.7bn EV = ~6.5x EBITDA, <8x FCF, <3x leverage
9) Other value levers - captive bank subsidiary (see Harley deal), cost cutting, acquisitions (~hiatus since '22)
Stock is up a bunch recently, but picture is much clearer with divested segment gone... arguably still very early
Hmm...

ً retweeted

$PBI Let me get this straight.
The stock has tripled, and yet Kurt Wolf thinks the turnaround isn't moving fast enough. He abruptly told the CEO and CFO to get out of the car, snagged the keys, and started driving himself. Brought in Paul Evans as CFO.
Market cap sits at $2.1B. Company maintains guidance on $330-370m FCF despite a major hiccup in Presort. They're within striking distance of remedying the problem, after which they're looking to substantially expand the segment's EBIT. There's so much remaining opportunity to drive efficiency and profit that Kurt casually compared the current state of the company to the GEC era. Tons of work to be done, he says. This is the verbiage of someone who sees a path to >$400m FCF in the near future.
Then, $400m buyback authorized, representing ~20% of the float as of May. $130m already executed. At current prices, share count would be reduced to ~150m. Kurt is using all of it. This isn't a matter of debate. The only question is what price the market will let him have, and by the looks of it, everyone is fast asleep. So asleep that Kurt is making it a priority to get more analyst coverage.
The call ends with the CFO admitting that he's looking into whether they can copy/mirror the execution of Harley Davidson's cash-out on their financial services division (!!). Hundreds of millions, apparently $300m+, would be freed up for more buybacks. And, again, Kurt is going to use the money.
Kurt confirms that he deliberately let his 105b-1 plan expire. He could have sold ~2m more shares by now if he wanted to, but stopped the plan dead in its tracks.
They say they're deliberately staying levered around 3.0x. Share repurchases are too attractive to pass up. But opportunistic debt optimization still possible regardless.
And I'm supposed to care about revenue guidance falling $50m?