





VKMacro retweeted

Even for someone optimistic on AI in the long term, objectively Ant went from adding 10B rev per month to ~2-3B of rev per month. Growth has slowed significantly in real terms, it’s not just “law of large numbers” deceleration, it is actual slowdown. On 70B base their recent rate of growth is possibly <50% forward annualized, which is slower than the Hyperscalers entire businesses are currently growing (CSP AI biz growing much faster obviously).
Data indicates potential acceleration for Ant from Aug-Sept levels in Oct, and there are 1-off headwinds they have absorbed contributing to slower recent levels of growth.
But that the business can decel by ~8B/mo almost as quickly as it accelerated highlights the risk, and why mkt is so jumpy on datapoints.
Not irrational at all that AI stocks are down this much. Add in rates/debt markets, politics, supply chains, lots of reason for elevated discount rates.
For the bull case for AI supply chain stocks in the short term, you need to see:
- Successful Ant IPO / OAI fundraise
- Rates to calm down and appetite from debt markets to support current rate of issuance for a few more years as buildout > monetization.
- Blowout cloud earnings and positive EPS revisions
- A few more “Claude code” moments unlocking new TAM from better models / harnesses / applications to re-accelerate AI token monetization trends out of current lull.
The trend is no longer your friend unfortunately.

VKMacro retweeted

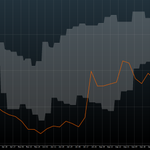
Not just the back end bidding up—Brent front vs M12 21d rolling correlation is dumping to levels unseen since last spring’s prompt spike(uncertainty blowout).
Setup flipped completely. Front is grinding slow, but long dated paper is rallying faster than back then.
Back end decoupling from the front signals a regime shift. Time to reprice the "crude dumps once this ends" consensus.
#oott #iran


The macro repricing of energy is now underway. Check out today's move in long dated oil - that's calendar 2027 WTI. When long dated oil moves this strongly in tandem with energy equities making new ATHs, financial markets need to listen. This is not a transient spike in prompt oil. It's far more structural. Get long, buckle your seat belt, and hang on for the ride.


VKMacro retweeted

New BIS Bulletin talks about increasingly non-linear inflation risks with Iran dragging on longer than expected and inventories rapidly depleting. BIS using "non-linear" language is a trigger for me.
bis.org/publications/bulleti…


Since the June bimonthly central bank governors meeting at the BIS, the BIS has published 3 Bulletins that read overly hawkish. These will be heavily discussed at their next meeting in September.
Bulletin 133, Aug19 on TERM PREMIUM: “term premium weakens the currency, heightens concerns that fiscal will constrain central bank independence, raises costs for credit-reliant firms, builds higher inflation into price and wage setting… term premium feeds thru to inflation expectations more rapidly when debt is elevated… adverse non-linearities raise the cost of delayed policy action… paramount for monetary policy to focus firmly on the price stability mandate”
Bulletin 131, Aug5 on ENERGY SHOCKS: "inflationary impact of energy shocks twice as large when inflation expectations are above target... tight labor markets intensify wage demands as labor seeks to reserve purchasing power... energy price surge combined with loose fiscal is followed by higher inflation... central bank wait-and-see strategy risks ripple effects such as unanchored inflation expectations and may warrant hiking more quickly"
Bulletin 130, Jul28 on AI IMPLICATIONS: "central banks too accommodative if they underestimate demand or overestimate supply improvements... demand effects already large and observable, supply effects remain uncertain on scale and timing... AI capex has not come at expense of less capex elsewhere... AI capex driving upward growth revisions... labor displacement has been limited... uncertain AI translates into higher aggregate total factor productivity... near-term inflationary effects already emerging... AI inflationary if households boost consumption in anticipation of stronger future income... AI wealth-driven consumption can boost aggregate demand and add to inflation... financial markets may lift household consumption thru wealth effects"
Notable because BIS messaging tends to lead global central bank messaging.
bis.org/bisbulletins/index.h…


Shame that’s the thing we trade and care about? Also what about products. Shipping costs hurt margins

Hard to argue with this: "The world's most important oil benchmark has become little more than a 'vibe contract', blunting its usefulness."
"Everything associated with energy is going up but Brent. It is not connected to the real world anymore." bloomberg.com/news/articles/…

The divergence in twd vs krw and other Asia fx makes sense to me.
At this stage 70% of twd movements can be explained via Nasdaq and equity flows. These are still negative as AI sentiment is bad.
In contrast Krw is less reliant on the daily equity flows side given exporter flow
As RBA goes further into restrictive territory, the bar for hikes rises. So far, out of their three point wish list, only the unemployment rate is really flagging green, with gdp growth and trimmed mean not quite there yet.
H7/h8 type flattened just make a lot of sense
Ya the big question really is what’s the benefit of the R&D if your edge only lasts 3m?


Specifically I mean previous cycles had a predictable half life of acceleration: it’s around 18m.
These cycles typically last longer, but by going to annual big capex earlier this year it changed dynamics for markets quite a bit.
IMHO the Anthropic supply side arguments for Q3 are the worst.
If you think the compute issues are more important than competition and bad product then ngmi
VKMacro retweeted

Update: Reuters revised its article to say the $110B figure stems from estimates from analysts who met with the company.


