

toronto rates + credit pm
Joined May 2020
- Tweets437
- Following2.7K
- Followers2.6K
- Likes4.8K





New BIS Bulletin talks about increasingly non-linear inflation risks with Iran dragging on longer than expected and inventories rapidly depleting. BIS using "non-linear" language is a trigger for me.
bis.org/publications/bulleti…


Since the June bimonthly central bank governors meeting at the BIS, the BIS has published 3 Bulletins that read overly hawkish. These will be heavily discussed at their next meeting in September.
Bulletin 133, Aug19 on TERM PREMIUM: “term premium weakens the currency, heightens concerns that fiscal will constrain central bank independence, raises costs for credit-reliant firms, builds higher inflation into price and wage setting… term premium feeds thru to inflation expectations more rapidly when debt is elevated… adverse non-linearities raise the cost of delayed policy action… paramount for monetary policy to focus firmly on the price stability mandate”
Bulletin 131, Aug5 on ENERGY SHOCKS: "inflationary impact of energy shocks twice as large when inflation expectations are above target... tight labor markets intensify wage demands as labor seeks to reserve purchasing power... energy price surge combined with loose fiscal is followed by higher inflation... central bank wait-and-see strategy risks ripple effects such as unanchored inflation expectations and may warrant hiking more quickly"
Bulletin 130, Jul28 on AI IMPLICATIONS: "central banks too accommodative if they underestimate demand or overestimate supply improvements... demand effects already large and observable, supply effects remain uncertain on scale and timing... AI capex has not come at expense of less capex elsewhere... AI capex driving upward growth revisions... labor displacement has been limited... uncertain AI translates into higher aggregate total factor productivity... near-term inflationary effects already emerging... AI inflationary if households boost consumption in anticipation of stronger future income... AI wealth-driven consumption can boost aggregate demand and add to inflation... financial markets may lift household consumption thru wealth effects"
Notable because BIS messaging tends to lead global central bank messaging.
bis.org/bisbulletins/index.h…

The question for bonds is are we going to "v-top" on yields (like 2022, 2023, 2025) or not?
Consensus last week with us10y at 5.35 was no because a v-top doesn't kill inflation (it didn't in 2022/2023/2025). Only sustained higher for longer can kill inflation.
Then we get a bond short squeeze on AI slowdown fears and now people think THIS CYCLE WITH THESE ECO NUMBERS will v-top at 5.35 during a week that had hot cpi and hot ppi?!
I don't think yields will do a v-top, but even if they do v-top, I still don't think this week was THE v-top... hence I am looking to short duration soon.
Some bond thoughts...
1. Price action feels more short squeezy than fundamental especially with hot cpi/ppi... how many were long tech + short bonds because "only high rates can crack tech" and now forced to unwind both sides?
2. Potential Friday 12pm dealer survey surprise (cut 20y auctions?) is preventing duration sellers from stepping in
3. If spreads behave then next week every corporate will want to issue bonds at these rates, especially with no data volatility, also gets them ahead of potential Fed volatility the following week
4. Bull flattening shouldn't keep going unless equities actually crack but all signs point to rotation not outright selling
5. 2y at 4.70 is only pricing 2 more hikes (remove the last 2 insurance cuts), don't think it can price less hikes without cold inflation prints which are now >4 weeks away
6. 10y at 5.05, who wants to buy 10y with a 4-handle? 4.98 is 50% retrace
7. This is still a long-term bond bear market right? You buy consolidations after breakouts to catch the potential face ripping reversals. Then you reset the shorts. You don't chase reversals until you have conviction in fundamentals changing.
I sold my duration longs today and cut my flattener in half. I want to be short duration next week if nothing fundamentally changes by Friday.
US2v10 now 38bp with -3bp today from hot CPI. Next target is 50% retrace from Sep23 low of 17bp to Oct8 high of 54bp, which is 36bp and should hit before Friday catalyst.
IMO Bessent adding a new question to Friday's primary dealer survey (cancel/reduce 20y auction sizes) is a no cost lever that opens door but doesn't box him into actual changes at Nov QRA. I do think he pulls that lever on Friday, but curve will bear steepen if he doesn't.
When Mnuchin added the question on sizing new 20y on 1/17/2020, he preceded with surprise press release on 1/16/2020 at 6pm. Perhaps we get a news bomb Thursday night before the scheduled Friday 12pm release. home.treasury.gov/news/press…

Something to consider for all those thinking BOC won't hike (Oct pricing only 27%)...
RBA minutes: considered arguments for not hiking, one reason was falling housing prices, but analysis suggested even large falls in housing prices would only have modest effects on spending
RBA has already hiked +100bps after cutting -75bps in 2025
US2v10. 45bp is the 50% retrace from Feb 74bp to Sep 17bp. Needs to flatten below 45bp to open the trap door lower.


Japan 30y finally breaks thru 4.20 on the 4th try but immediately reverses with an engulfing candle. Possible interim top for Japanese duration, which has been the leader ytd.

Bear flattening dominates hiking cycles, but there are brief periods of bear steepening when you zoom in at the start of hiking cycles:
2026: +30bp after 1st hike
2022: +45bp after 1st hike
1999: +20bp after 1st hike and +30bp after Dec skip
1994: +20bp after 1st hike
1988: +20bp after 1st hike
1987: +40bp after Volcker surprise quit
In almost all cases Fed became significantly more hawkish and curve bear flattened.
Only 1987 had durable bear steepening until Oct87 equity crash started bull flattener. Is today 1987? (inflation panic, dxy plunging, oil rallying)


Since last Fed meeting: Oct hike odds drop from 55% to 20%, but 10y +33bp...
Greenspan May2000: 10y +50bp as markets adjust to stronger growth… should hike 50 to match market and allow market forces to play out rather than trying to pushback… should follow market until evidence that inflation is slowing… corps shifting borrowing from longend to frontend because they think rate rise is temporary, eventually they will understand rates are higher for longer and will slow capex
...think Oct hike odds too low. Warsh speaks Oct16.

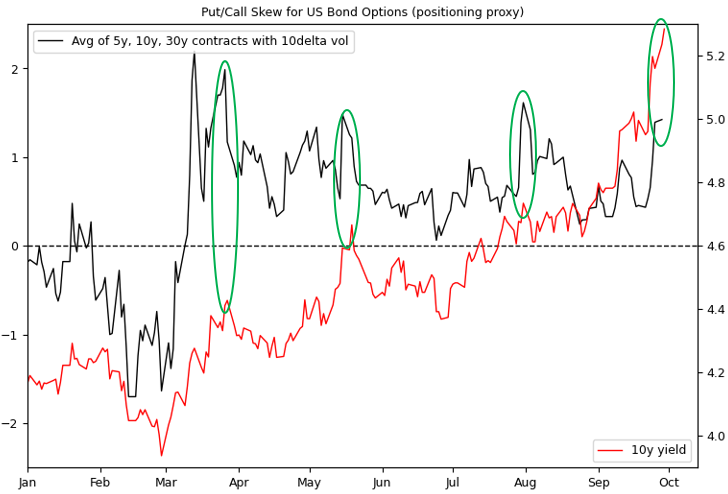
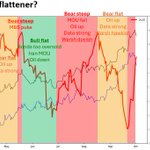
Flattener time? Bear flat is classic behavior at this stage of cycle. Bull flat has 4-week window before midterms for Bessent to do something.
Bear steep feels overdone here. Bull steep requires Iran deal (unlikely) or something breaks that allows dovish pivot (unlikely)...


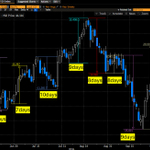
Big moves in the curve have been running out of steam after 7-10 days... recent bear steep move is now at 7 days.


Treasury advisor Zervos: market should take into account that treasury manages maturity structure, watch closely how it gets managed, bond supply matters to yields, buybacks and guiding market as it finds equilibrium for long-term rates is good and I'm excited to be a part of it

