

I'm a CPA with a focus on equities, derivatives and currencies that benefit from chaos and shortages. Conversely, I short anything that's oversupplied.
Toronto
Joined February 2014
- Tweets3.2K
- Following275
- Followers832
- Likes5
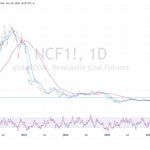




Newcastle coal prices still haven't broken out. Unless #newc starts tracking LNG prices.... $whc.ax $yal.ax $BTU are going nowhere.
In 2022 LNG and #newc prices were correlated and coal equites had a fantastic run. The chart to watch is Newcastle coal, not LNG.


After WWI, Britain and the other victorious powers redrew Europe's borders. Great powers have a history of sacrificing smaller nations for their strategic interests. This a plausible end game for Ukraine.
Don't rule out the US and China sacrificing Ukraine in pursuit of Middle East stability. The continued destruction of energy infrastructure is not good for anyone.
@toiletkingcap

There is a quid pro quo here. Russians help out US with Iran. US helps out Russia with Ukraine.
Once China gets fed up with high oil prices, they'll tell Iran to stand down.
Wars are costly and nobody wants to lose money indefinitely.

One thing I've learned about investing: if your thesis falls into the TL;DR category, pass.
A good investment thesis should fit into three sentences. If you need five reasons to justify buying $GLNG, you're probably trying to convince yourself a mediocre idea is a good one by piling on arguments. Adding on more arguments does not make an investment any better.
Great investments need one or two compelling reasons. The other three are just noise. $glng is an easy pass.

$GLNG
It’s annoying to see how the market is mispricing this company.
I mean, it’s true the company should be viewed as an infrastructure play—a kind of bond proxy—and its valuation should reflect rising interest rates. But the current valuation is just silly. It has $17bn in contracted EBITDA over the next 20 years with strong counterparties. That EBITDA represents free cash flow before debt service and interest, as the business requires virtually no taxes or maintenance capex, yet the company is trading at around $4.5bn. That’s before adding the fourth FLNG, which has already reached FID and could significantly increase run-rate EBITDA from $800m to $1.1bn–$1.2bn. It’s also before considering the 20-year commodity upside option Golar signed into its contracts, which could generate free cash flow equivalent to the market cap in a year like this one—and multiple times that amount if we look at 2022.
Is the market so silly? I think so… As I’ve argued, I don’t expect Goldman Sachs’ strategic review to end in a sale, and that’s likely been weighing on Golar’s share price recently. I can see Goldman bringing in a strategic partner to develop and accelerate the strong pipeline, but I don’t think any capable external player could both fund and execute that growth pipeline.
After meeting Tor Olav Troim at my office this week, I’m even more confident that Golar has four or five highly credible projects it could sign soon. Recent reports from TradeWinds and Africa Intelligence confirm that these projects are moving ahead—and that only Golar can deliver.
1) TradeWinds reported that Eni and Repsol are moving ahead with Venezuela’s FLNG project. Golar LNG, BW LNG, Bumi Armada, SBM Offshore, Samsung Heavy Industries, Hanwha Ocean, and Saipem have reportedly submitted EOIs, with a full invitation to tender expected later this year.
2) Africa Intelligence reported that Trident Energy is looking to monetize its 1 trillion cubic feet of gas reserves in Congo, with Golar and Exmar currently competing for the contract.
With all due respect to the companies mentioned in the news, nobody can really compete with Golar. Only Samsung and Exmar have ever built an FLNG vessel. That’s no simple undertaking, so I don’t expect any of them to take on more than $2bn in risk to get started. As for Exmar, it built a very small liquefaction vessel called Tango, which performed so-so for a while before Eni bought it in 2022. Exmar’s accounts are public, and it’s well known that the company doesn’t have the funding capacity to carry out a project of this size. I know Exmar very well, as we recently funded $12m out of a $150m bond. Finally, Samsung has experience, but it’s a shipyard, and financing a customer over 20 years isn’t its business. I don’t expect it to change its business model now.
Gas is hot right now, and demand is expected to grow considerably. After the conflicts involving Russia and the Middle East, every country realized it needs to diversify its supply; it can’t rely only on the US, Russia, or Qatar. This is a great time for Golar to capitalize on the current environment, which is why it’s building a $2.5bn FLNG on spec. I expect we’ll have a contract within the next six months, and thereafter, Golar will find another compelling project for the fifth.
I may be overthinking this, and the current weakness could simply be driven by its association with shipping—which seems silly nowadays, given its legacy as a shipping company. Or even some HF exiting as they are forced to cut leverage because interest rates are rising… But to be fair, I just struggle to understand why Golar is so cheap, even without factoring in growth or commodity upside.
A lot of bad things can happen to $GLNG between now and 2029. The market doesn't even discount tech earnings that far out.

Their 2029 contracted EBITDA is $800M without talking into account the commodity upside and the SESA participation. So it's really at 5,5-6x the 2029 EBITDA. Quite a different story. These kind of companies don't usually trade so cheap.
Tor Olav Troim has been buying into the most expensive offshore driller - $BORR.
Why should anybody else do so, when there are much cheaper companies? What's the story with $borr? Even $tdw is cheaper.

Offshore Q3 earnings preview is out.
The deepwater bull case looks more or less confirmed: floater utilisation at 84% in September, heading to 92% by end-2027, and leading-edge drillships fixing at $440-530k/day. But the drillers are already considerably up this year, at 0.8-1.1x gross asset value, so we are positive on the cycle and can easily see the stocks trading sideways from here.
The valuation spread is the more interesting part: 3.8x EV/EBITDA at SED against 12.7x at Borr, with Odfjell and SED screening best on visibility and yield and Tidewater, at 118% of newbuild parity, the most expensive name.
Full note, with company-by-company previews and what to watch into results, below or at nortilus.com.
#offshore #oott $BORR $RIG $VAL $GMS $GMS.L $TDW $SEA1.OL $ENH.OL $ODL.OL

Valuations aren't driven by fundamentals alone. Perception and sentiment matter. Why is gold worth thousands an ounce? Why pay $20,000 for a dress or $1 million for a watch?
Value is subjective. Something is worth what people are willing to pay. $tsla

If you are the Supreme Leader of Iran, would you make a deal with the person who killed your father?
This personal grievance is the essence of why resolving the conflict is so difficult.
@BurggrabenH

"Relatively" and "More" Do Not Mean the Same Thing
More is a comparative word used to show that one thing has a higher quantity or quality than another (e.g., "Gold is more expensive than silver").
Relatively means "in comparison to something else" or "proportionally."
When you combine them, "relatively" modifies "more." It specifies how or by what standard something is more expensive.


Future wars will be fought with AI-powered weapons. The country with superior AI will have a decisive military advantage.
For the West, winning the AI race against China is a national security imperative. I expect AI capex to accelerate over the next five years, not decline. Military superiority is too important to compromise.
Invest accordingly. The future of warfare is AI. Go all in on AI because wars will always be around.
$nvda $mu $crdo


Markets don't trade on fundamentals alone. When technicals look bad, technical traders sell regardless of fundamentals.
Not everyone sees the market your way. Pay attention to what others are doing. They have far more money than you and can move the market. $SOXX
Leopold Aschenbrenner is anything but unlucky. That guy has accomplished more in his 20s than 99.9% of us will achieve in our entire lives.
@JonkooTrades can only dream of being as "unlucky" as Leo.

Leopold Aschenbrenner might genuinely be the unluckiest motherfucker alive.
After getting absolutely destroyed in July and being forced to liquidate much of his AI portfolio, he reportedly came back swinging in early September, buying hundreds of millions of dollars worth of options premium.
Look at how those stocks have performed since September 8:
$CRWV: -37.4%
$SKHY: -25.8%
$SNDK: -23.8%
$DRAM: -22.9%
$BE: -18.1%
$INTC: -9.4%
$AMD: +9.1%
Six out of seven are underwater, with an average decline of roughly 18.6%.
And remember, we're talking about someone who reportedly rebuilt exposure through leveraged options, not just common shares.
Imagine surviving a massive forced liquidation, watching your favorite stocks recover, deciding it's finally safe to get back in, and then getting hit by ANOTHER brutal selloff barely a month later.
The worst part about options is that you can be absolutely right about the long-term AI infrastructure thesis and still lose a fortune because your timing was wrong.
I genuinely feel for the guy.
The market has absolutely no mercy.


Seeing the future and getting there before anyone else is how you win as an investor.
Imagine being able to see the future in 2000 with $amzn or $nvda in 2023. These companies did, and you won big time.

Stocks go up when there are buyers. That's what you need.
Who is buying $ONON? Certainly not dividend investors, momentum staying away, technical buyers won't go near it. $onon won't go anywhere until new buyers show up. The market is telling you that it won't happen anytime soon. $onon is dead money.


Stop whining about why a stock is down or acting weak. It shows how naive you are about the stock market.
People sell stocks to pay taxes, buy a house, put a kid through school, buy a car, go on vacation, have cash for fund redemptions —the list is endless.
There are hundreds of reasons a stock can go down that have absolutely nothing to do with the fundamentals of the company.

The market is always right...
But I don't understand #Tankers being so weak last days...
Rates keep going even insaner.