

Industry leading shipping & offshore research with proprietary earnings estimates and data coverage. Follow us for updates
Joined July 2025
- Tweets540
- Following2
- Followers1.3K
- Likes135






New note on Golar LNG (GLNG) is out.
The engineering finally works. Hilli finished Cameroon with 100% uptime, Gimi is running above contract and Esperanza is on time. The balance sheet is another story. Golar ordered a $2.45bn fourth FLNG with no charter and has about $3.5bn left to spend against $2.0bn of liquidity. Net debt goes from $1.8bn to roughly $4.9bn by 2029, with the RCF due before Esperanza earns a dollar.
The stock is 22% off its high and the strategic review has gone quiet. At $44.95 it trades at about 8x 2029 contract EBITDA, which already prices everything being delivered. We'd get interested below $40.
Full note: nortilus.com / nortilus.substack.com
$GLNG

Offshore Q3 earnings preview is out.
The deepwater bull case looks more or less confirmed: floater utilisation at 84% in September, heading to 92% by end-2027, and leading-edge drillships fixing at $440-530k/day. But the drillers are already considerably up this year, at 0.8-1.1x gross asset value, so we are positive on the cycle and can easily see the stocks trading sideways from here.
The valuation spread is the more interesting part: 3.8x EV/EBITDA at SED against 12.7x at Borr, with Odfjell and SED screening best on visibility and yield and Tidewater, at 118% of newbuild parity, the most expensive name.
Full note, with company-by-company previews and what to watch into results, below or at nortilus.com.
#offshore #oott $BORR $RIG $VAL $GMS $GMS.L $TDW $SEA1.OL $ENH.OL $ODL.OL

The US may ease sanctions on grey-fleet tankers to curb freight but how much new capacity would actually emerge?
BRS counts 658 OFAC-sanctioned tankers, yet only 148 are sanctioned by OFAC alone. Just 14 of those appear to have been idle for over 3 months.
China’s clean product exports could fall from ~2.8M tonnes in October to ~2.0M tonnes/month in November–December. That’s a ~29% drop in monthly export volumes.
For MR tankers, the impact depends on whether shorter Asian routes and resilient regional imports can absorb the available fleet.
A tough week for shipping equities. Dry bulk lost 9.4% as Capesize rates fell 32%, and tankers, gas and containers gave back 4-7%. Only liners and offshore drillers finished in the green.
The backdrop didn't help: hotter US CPI and PPI, a 16% crash in the KOSPI, and an Iranian campaign in Hormuz that now targets container ships too, with the first sinking this week. Washington is even weighing easing sanctions on shadow fleet tankers to cool freight rates. We think the practical impact is limited, and explain why.
We also look at why the Cape sell-off is about congestion clearing rather than weak cargoes, and at a busy week in offshore, from the Transocean/Valaris approval to record dayrates in Norway.
Full Note on: nortilus.com / nortilus.substack.com
#shipping #shiptwit #tankers #drybulk $FRO $OET $ECO $INSW $SBLK $BWET $BDRY

The Transocean/Valaris merger has received final regulatory approval, with Brazil's competition authority clearing the transaction without restrictions following US approval earlier this month. Closing is expected in Q4 2026, subject to shareholder approval.
The merger is another important step in the consolidation of the offshore drilling industry. The combined company will control approximately 40% of the global seventh generation drillship fleet. Together with Noble and Seadrill, the three contractors will control around 80% of seventh and eighth generation drillship capacity, compared with just 40% held by the three largest contractors in 2017.
Importantly, Valaris has been particularly aggressive on pricing, while Transocean has been one of the most restraintful.
Bringing the two fleets under one roof should remove some of that competitive pressure and shift pricing power back towards the drillers. The combined company will also control much of the sidelined high specification capacity, which should help maintain discipline around reactivations.
$VAL $RIG
Saudi Aramco is offering extra spot crude cargoes to Europe for late October and mid-November delivery.
Angola is fighting to keep crude output above 1M b/d as mature fields decline. For Africa’s 3rd-largest oil producer, the battle is no longer just about growth, it’s about defending the production base.
Dry bulk Q3 '26 preview is out.
Capesize averaged $44.9k/day in Q3, up 13% on Q2 and almost 60% on last year, then lost 30% in a week in mid-October. The curve prices a softer Q4, but November-December Capesize at $32-35k/day is still more than double the median cash breakeven of the ten names we cover.
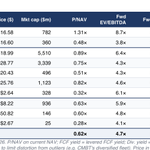
The stocks have run (median +27% in Q3, EDRY +135%), yet the median name still trades at 0.62x NAV. We stay with the spot-exposed, high-yielding names into year-end.
Full preview, with our estimates for all five names: nortilus.com / nortilus.substack.com
#shipping #shiptwit #drybulk $GNK $SHIP $DSX $SB $HSHP $SBLK $USEA $EDRY $BDRY

West African Suezmax demand: record highs, but a reversal may be coming. Volumes topped 84M barrels in October, a historic high. Now, demand is expected to fall month-on-month, with downward pressure looming.
Record cargo volumes. But the rate rally may be running out of fuel.
Our Containerships Q3 earnings preview is out.
On the spot side, things look flat over the quarter: the WCI peaked in early July and ended Q3 about where it started. That hides a lot underneath. Asia-Europe has dropped 30-40% as carriers go back through Suez, while the Transpacific is up 18-29%. For the owners we cover, though, what counts is the charter market, and that kept firming. 12-month rates rose or held in every size, and small feeders were up 7-10%.
All five names beat consensus in Q2, and with near-full charter cover through 2026 Q3 should be fairly predictable. The sector trades on 0.66x NAV and 4.1x EV/EBITDA. Navios is the one we like, at 0.39x NAV, with Angeliki Frangou buying shares almost every day through Q3.
Full preview, with our estimates for all five names: nortilus.com / nortilus.substack.com
#shipping #shiptwit $NMM $GSL $DAC $ESEA $MPCC $MPCC.OL

Saudi crude has arrived at Aramco’s new refinery complex in northeast China. The first cargo brings the billion-dollar project closer to production, potentially creating another major outlet for Middle Eastern crude.
Our Crude Tankers Q3 earnings preview is out.
Q3 was a good quarter, but most of the real move came at the very end. VLCCs averaged around $295k/day over the quarter, against $129k in Q2, with September alone near $580k. October has started even higher, above $800k/day, so a lot of what we saw in September only really shows up in Q4 numbers.
The equities have noticed. Every name was up 34-61% in Q3 and they’ve kept going since. Even so, the sector still trades on around 4.3x EV/EBITDA, and Tsakos is at 0.41x NAV.
Full preview, with our Q3 estimates for all seven names: nortilus.com / nortilus.substack.com
#tankers #tankergang #shipping $DHT $TNK $ECO $OET $FRO $INSW $NAT $TEN

Nortilus retweeted

According to the WSJ and other news outlets, ADNOC L&S ($ADNOCLS) is approaching HEA Energy, to buy a stake in the company.
The article says that HEA Energy is being valued at $3 billion.
This is very relevant for Gulf Marine Services ($GMS.L), given that HEA Energy is an owner of liftboats.
#offshore #oott
wsj.com/business/energy-oil/…
