

Tech investor for ~25 years. Ran large hedge fund for 10 of those. Here to help. Not investment advice. I never reach out to sell ANYTHING.
NYC
Joined July 2018
- Tweets1.9K
- Following344
- Followers19.5K
- Likes2.5K


Good point. Although if I were management and supply constraints limited growth, I would definitely say that in the S1 / meetings.

This exchange:
Analyst "So, should we expect a re-accel to maybe 100-110b by year-end"
Anthropic CFO: "We aren't commenting on forward looking figures but believe in a large opportunity over time"
Analyst "Got it" [Writes down "management didn't talk me down from 110b"].
For what it's worth, I think Anthropic ARR and revenue are both gross per their consistent commentary that they are the principal in transactions.
So the revenue and ARR tie nicely, and mention of 85% GMs likely means the cloud partner share is categorized as S&M.
So I think this all foots.
And, fwiw, Claude says cleaning up distillation is at most 500m / mo headwind so that's not it. But apparently company is saying otherwise?
I'm not meeting with Anthropic today so I don't know - but I would have to imagine that if that explanation is significant, it is definitely being discussed.
Because otherwise the M/M growth implies a dramatic slowdown.
Ok, it might be over folks.
Anthropic revenue disclosure maps to ~5.8b in September revenue or 70b ARR which means August / September only increased by 2-3b ARR in each month.
[There is no way that ARR is calculated using last day of the month as that would be more aggressive than anything I've ever seen out of companies this size (exception: Musk).]
Worst monthly numbers by far this year. (Maybe some self-infliction from cleaning up distillation?).
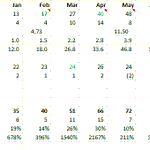
My rough math indicates OAI / ANT ARR monthly add softened from 16b in July to 10b in Aug to 9b in Sept. That is no bueno...
Supportive of the view that either CAPEX is getting cut or pricing is going to weaken substantially.

Thx for the thoughts.
I think the pushback would be great models are available from 5-10 players who have been neck and neck forever, so seems like inference margins will be quite low over time (although I hear your point that this isn't a certainty), and that LLMs don't seem to present a distribution threat for now.
I'd say that's a strong point if there was only 1-2 labs w/ good AI. But there are plenty of them to make sure LLMs are available at great quality / price specs.
Dumb question but what's the advantage of $META having spent 100b+ to develop their own model under Muse, as opposed to having kept that money and just built Muse with whatever model gets the job done?
$MS Q3 CIO survey had some interesting results.
These surveys aren't super reliable - partly because big company CIOs are often very political so have to take all feedback with a grain of salt.
Highlights
-AI is at top of enterprise priority list. Basically every other category decreased including security.
-LLM share of AI spend jumped from 11% in Q2 to 16% in Q3 – not surprisingly the biggest jump.
-LLM share of AI spend over next three years jumped from 17% in Q2 to 21% in Q3 – again, the biggest jump amongst answers
-Nearly all SaaS companies declined in expected incremental share of AI budgets – foots with slow progress on product / sales of AI products at SaaS companies
-50% of CIOs said they were funding AI from net new dollars directed towards AI.
-50% of CIOs said they are not using any open source AI models today; 4% said open-weight usage is >50%. [I’m honestly guessing most CIOs have no clue or answered for budget share and not workload share]
-42% of CIOs said not sure about ROI on token spend. [Again, CIO’s are typically large company politicians so not sure what to make of this answer. Also what was the immediate ROI on giving employees PCs or cell phones?]
-43% have token spend controls in place
OpenAI at 70b net never really made any sense intuitively.
Still seems like net ARR added in September was 17b similar to 17b in August. 17b is still pretty ridiculous and suggests we finish the year ~200b gross across ANT / OAI.

@a16z put out a solid deck today on State of AI.
Does a good job of just putting it all together - AI capabilities rapidly expanding, AI model revenue ramp unprecedented, semi spend underneath unprecedented and driving earnings growth of the entire stock market, and multiples reasonable due to cyclical concerns.
To me, the "elephant in the room" question is simply will AI monetization accelerate over the next couple years from what likely will be ~200b run-rate at the end of this year.
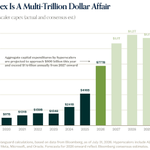
Very rough math, but we added ~170b of model revenue in 2026 against 1.4t of capex over the past 3 years and 780b in 2026.
Expectations per chart below are for 1.1t of capex in 2027 which then flattens. Maybe that implies the model companies in aggregate need to add ~200b of ARR each year to justify that spend?
Is that possible? Sure but also tough to assign probability bc there are a million unanswerable questions underneath (product development, pricing power, etc.).
That's also the bear case for semis for a future date: even if model companies plus others can add ~200b / year of incremental revenue, that implies semi spend stagnates after 2027 -> second derivative turns negative and multiples stay low until the inevitable downturn.
I personally think 2028 is probably a 20-30% growth year in capex so the whole trade is more likely to up than down from here at these valuations, but just pointing out the risk that the market is pricing in here (and that has to dissipate via continued ARR growth / hyperscaler capex growth commentary to see the trade run).
[Btw, I also think it's so fascinating that leading investment firms are also publishing leading news / research. This free newsletter from A16Z smokes independent publications (WSJ, Gartner, etc.), and the sell-side (less conflicted in some ways and more informed)]

