

Tech investor for ~25 years. Ran large hedge fund for 10 of those. Here to help. Not investment advice. I never reach out to sell ANYTHING.
NYC
Joined July 2018
- Tweets1.9K
- Following344
- Followers19.5K
- Likes2.5K

Ok, it might be over folks.
Anthropic revenue disclosure maps to ~5.8b in September revenue or 70b ARR which means August / September only increased by 2-3b ARR in each month.
[There is no way that ARR is calculated using last day of the month as that would be more aggressive than anything I've ever seen out of companies this size (exception: Musk).]
Worst monthly numbers by far this year. (Maybe some self-infliction from cleaning up distillation?).
My rough math indicates OAI / ANT ARR monthly add softened from 16b in July to 10b in Aug to 9b in Sept. That is no bueno...
Supportive of the view that either CAPEX is getting cut or pricing is going to weaken substantially.

OpenAI at 70b net never really made any sense intuitively.
Still seems like net ARR added in September was 17b similar to 17b in August. 17b is still pretty ridiculous and suggests we finish the year ~200b gross across ANT / OAI.

@a16z put out a solid deck today on State of AI.
Does a good job of just putting it all together - AI capabilities rapidly expanding, AI model revenue ramp unprecedented, semi spend underneath unprecedented and driving earnings growth of the entire stock market, and multiples reasonable due to cyclical concerns.
To me, the "elephant in the room" question is simply will AI monetization accelerate over the next couple years from what likely will be ~200b run-rate at the end of this year.
Very rough math, but we added ~170b of model revenue in 2026 against 1.4t of capex over the past 3 years and 780b in 2026.
Expectations per chart below are for 1.1t of capex in 2027 which then flattens. Maybe that implies the model companies in aggregate need to add ~200b of ARR each year to justify that spend?
Is that possible? Sure but also tough to assign probability bc there are a million unanswerable questions underneath (product development, pricing power, etc.).
That's also the bear case for semis for a future date: even if model companies plus others can add ~200b / year of incremental revenue, that implies semi spend stagnates after 2027 -> second derivative turns negative and multiples stay low until the inevitable downturn.
I personally think 2028 is probably a 20-30% growth year in capex so the whole trade is more likely to up than down from here at these valuations, but just pointing out the risk that the market is pricing in here (and that has to dissipate via continued ARR growth / hyperscaler capex growth commentary to see the trade run).
[Btw, I also think it's so fascinating that leading investment firms are also publishing leading news / research. This free newsletter from A16Z smokes independent publications (WSJ, Gartner, etc.), and the sell-side (less conflicted in some ways and more informed)]


Should have added that OAI simply saved down that I have $FDS and will just use it when it needs to going forward....!
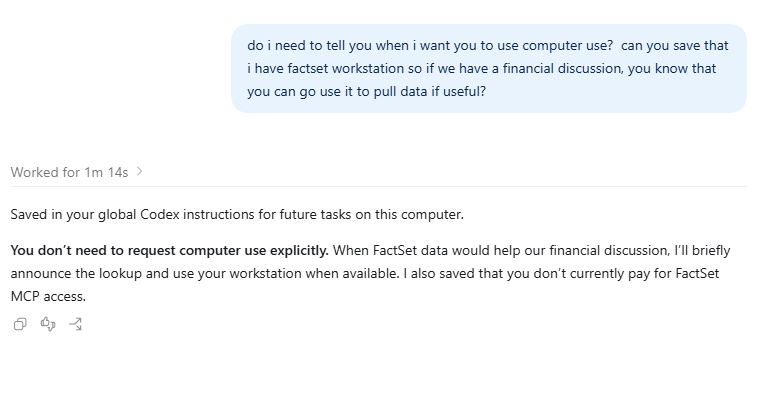
Another day, another bit of AI functionality, and another question as far as incumbents...
So I previously tested $FDS MCP which was a huge advance for AI financial functionality, and a growth driver for $FDS subscriptions (call it 20% uplift to enable).
And then today I tested just using OAI's computer use on the regular desktop session, and it worked pretty well albeit a lot slower.
Kind of funny how quickly some of the SaaS bear points from earlier this year are materializing...
In this case, it's that usage of the SaaS app becomes more automated from outside and becomes unmonetizable...
(Separately, being bullish on $CRM Claudeforce is really puzzling to me - that felt more like a defensive point for the SaaS won't go away tomorrow than an offensive point for SaaS will participate in AI).

I'm really curious to know what percent of $GOOGL / $AMZN ad spend consists of brands buying sponsored listings for their own search terms - basically spending to defend their own screen turf from competitive ads.
See below for searches for Speedo Goggles:
GOOGL: The entire visible screen is sponsored ads which Speedo has to pay for. The next screen down has Speedo in a thin organic result followed by a Deals market ad where Speedo again has to pay for shelfspace.
Using Gemini search for "Find me speedo goggles" only showed Speedo branded goggles.
AMZN: Speedo has an organic link in the bottom left and right, and otherwise is surrounded by competitive listings. Interestingly Speedo not paying up here (maybe realized using branded term this close to checkout means consumer is buying Speedo regardless).
Using Alexa AI search for "Find me speedo goggles" only showed Speedo branded goggles.
I personally find GOOGL / AMZN search results to be over-monetized w/ ads that don't add value - and, in fact, make it more annoying for me to find what I want.
AI search for products on AMZN works really well for me fwiw so I must already be seeing far fewer ads simply by this usage shift.
I don't really know what happens to this "traffic defense" spend in an agentic world. Feels like it would be less necessary in a world where agents need to be trustworthy to win consumer preference. So hard to imagine I ask an agent for speedo goggles and it spends 80% of the answer discussing competitive brands like regular search results do today...
Maybe consumers always want choice so there is room for other brands to pay to be mentioned within the AI results - while still not being dilutive to the consumer's experience?
Or, maybe agents can find the best 2-3 products so less need for brands to advertise within search and just put those dollars towards improving product quality / Internet posts to drive agentic preference?
Random thoughts...


$QQQ forward P/E has averaged ~25x for the past 10 years.
It currently trades at ~20x the 2027 EPS estimate.
Let's assume a big recession in semis. I cut the 2027 EPS estimates for NVDA, AVGO, AMD, MU, LRCX and AMAT by 50%.
$QQQ is then trading at 24.5x the revised 2027 EPS.
Obviously, that isn't going to happen but shows that the market is already effectively pricing in an outcome like that already. [Maybe that's too optimistic and market would trade at 20x EPS in that scenario which would present 20% downside from here if it were to unfold].
I'm not smart enough to have a view on 2028 yet but doesn't feel like capex is going to get cut materially unless Anthropic / Open.AI growth dramatically decelerate.
Separately, AI in Excel is pretty solid. Just obvious to me AGI is already here.


Further review of $DXYZ filings reveals some interesting points.
Punchline is disclosed NAV is $34.30 today (6% upside from current price), conservative NAV is ~$35.31 (9% upside but only assuming Anthropic is 1t), and a reasonable NAV target might be $43.86 (35% upside assuming Anthropic is 2t and OAI is 1.3t).
And some call option value on the equity doing something silly in advance of the IPO.
1. DXYZ is paying neither a management nor an incentive fee to Magnitude for the Anthropic position. See table below. Not paying fees for anything other than SPCX really.
2. DXYZ did not sell any Anthropic in the quarter. The N-PORT filings confirm it continues to hold 386,088 shares.
3. The value of the Anthropic holding only increased from 134m on 3/30 to 236m on 6/30. The stake was acquired on 1/26 for 107m. Assuming the 107m was invested at ~350b valuation, DXYZ is carrying Anthropic at ~770b valuation at 6/30 which equates to 14.4% of the NAV.
4. The valuation methodology for Anthropic is buried in the SPV valuation table. The Fair Value of $278,448 is only cleanly calculated by summing Magnitude, Goanna, and OAI. The methodology blends volume weighted average transaction price, index price and recent transaction price. The avg for these three investments was $651.51 over the qtr w/ the highest input being $766.76. A long way of saying this is another sign that Anthropic is likely being marked at a meaningful discount to even the 965b post Series H on 5/28.
Scenario 1 (realistic cut as of today): Assume Anthropic 1t, OpenAI 850b, SPCX current price results in $35.31 NAV with position sizes of 46% cash, 18% Anthropic, 12% OpenAI.
Scenario 2: Anthropic 1.5t, OpenAI 1t: $39.23 NAV with 41% cash, 25% Anthropic, 12% OpenAI.
Scenario 3: Anthropic 2.0t, OpenAI 1.3t: $43.86 NAV with 37% cash, 29% Anthropic, 14% OpenAI
5. DXYZ sold 17m shares in the qtr at an avg price of $41.82. This is where the interests of DXYZ and investors diverge. Investors want exposure to the home-run investments w/o dilution. Meanwhile DXYZ has a business to run and wants to raise assets when the equity is at a premium.
5. The board approved a share repurchase program in August that allows them to buy back stock when it trades below NAV. So they now have a mechanism to raise capital when the stock is above NAV (bad for short-term traders of the stock), and buy the stock back to NAV when it trades below (good for short-term / long-term traders).


$WDAY Q2 was totally fine.
Leading SaaS provider of HCM / FINS is building out their AI capabilities. Business is mature since they are highly penetrated in the market so growth depends on upselling additional products (40% new logos / 60% upsell) which results in ~10-12% revenue growth. Meanwhile, margins are finally a point of focus and have plenty of room to increase from 14% GAAP this year (they plan to keep headcount flat going forward).
They previewed next year at exactly where street is (11% growth) which I think is meant to get ahead of having to guide below later this year, and will show 200 bps of margin expansion which is nice to see. Really not much of a revisions story which is probably why so many people were short it.
The business hasn’t really changed in quite some time although the narrative went bonkers to the downside and is now normalizing. The business ought to continue growing 8-12% for a while w/ much faster profit growth. AI revenue is only 6% of the business although growing quickly – so unlikely this business materially changes even if AI monetization works.
The real risks are just that big companies focus their investment outside WDAY into hotter technologies (Claude, new AI point solutions) which would slow their growth rate. But the Global 2000 isn't ripping this stuff out. You are definitely a loser company if your first thought in an AI world is to focus on your ERP software instead of more growth-oriented applications.
No discussion of M&A which I’m sure is ongoing. The co-founders have voting control so comes down to them. I think it would be pretty insulting to shareholders to sell anywhere south of $250 and could even argue that’s too low.
I don’t know what the right multiple is for this company. Would think 20x earnings power (see-through margin) isn’t crazy which equates to 30-35x GAAP EPS / NOPAT. Maybe it goes back down to 10x FCF although that was pretty crazy.
It's good to see that the old rule of it being impossible to lose money buying a profitable, growing and recurring revenue business at 10x FCF or below still holds.
Qtr
Subscription rev of 2.47b grew 13% yy cc organic consistent w/ prior qtrs. Retention rate stuck at 97%.
PF OM of 31.1% up from 29.0% last Q2. SBC of 17.4% up from 16.7% - not sure what’s going on – maybe retention bonuses for acquired teams.
NOPAT margin of 10.9% up from 9.8%. Put me in coach. I could take it to 40% tomorrow.
Sharecount is down 9% in three quarters. Good job with the buyback – well executed.
