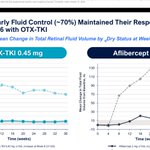
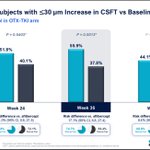
$OCUL latest slide (post-hoc) show that the ~30% that does not respond well to Ax or Eylea can be identified week 4-8. In Axpaxli group, the remainder, 70%, all get to 9 month.
900m EV for $OCUL is nuts when clinical risk is behind us. There’s regulatory & commercial risk left. With SOL-R rescue criteria applied, which are inline with industry practice, 77% of patients in SOL-1 are rescue free at 6 months. This is a phase 3 program with an SPA.
$OCUL would have loved to buy at these levels but too overweight this stock
$ocul $kod If both get approved, Axpaxli having better durability, on label and in practice, is close to a given. Sustained release vs bolus is structural. If durability drives share, $6B vs $1.5B is a wide gap.
The path to market share is to have durability that meets or exceeds the other products on the market. $OCUL is weeks from submitting a product that is almost guaranteed to get a product approved with a label that will read durability of 6 months to 1 year. They will be able to advertise that this works for up to one year. Anyone who wants to grab a significant market share will need to be able to say the same.
$OCUL dump totally overdone. News is Axpaxli got a competitor at 6m dosing. Vabysmo class drug. Good potency and longer duration vs Vab. Very good BCVA @ 6m. For TKI class, superiority label and 9 or 12 month duration, there is ONLY Axpaxli. Ax also likely fewer rescues @ 6m
Random thought; I addition to extending SOL-R to get HD superiority data + fibrosis data, I think Dugel is timing the SOL-R release for maximum $EYPT damage, ie when they are to raise or launch.
My biggest concern with SOL-R was if axp could hit even numerical non inf against HD in this very stable pop. They are now going for stat superiority, much higher bar. $OCUL is swinging for the fences. Very gutsy!
$OCUL “let’s use SOL-R to try to prove superiority against Eylea HD” 🔥


