




Mr. DCC retweeted

1. Increased share buyback program
2. Boosted quarterly dividend
3. Announced cash tender to retire debt early at a discount
The 🐺 must know that $PBI is generating (and will continue to generate) massive free cash flow for the foreseeable future.
This quoted post is unavailable.
Mr. DCC retweeted

At $1.90, $ALTO has just barely started trading above the price it was at when Bradley Radoff's group disclosed their activist position back on February 24 ($1.87).
The market is contradicting itself here. Back in February:
1. The BBB, which substantially extends 45z credits, had not been passed yet. Also, management hadn't hinted at the possibility of lowering their CI score through EAC's and other initiatives.
2. E15 in California had not been passed.
3. Crush margins were weaker.
4. The benefits of activist involvement, including SG&A cuts, better operational efficiency, and more thoughtful capex, were unknowns and hadn't been realized yet.
5. Related to (4), asset sales weren't being seriously entertained. Now they are.
6. Western assets were still stuck in the mud. Now they're a net positive for the company (environment is so good now that Magic Valley might even be able to restart).
7. There weren't any performance catalysts. Now we're coming off of Q3 results, which were the best $ALTO has had in over 3.5 years.
So, in a very real sense, the market hasn't factored in almost anything on this list. We've only returned to the price $ALTO was at when it was still incinerating shareholder equity and the future was unclear.
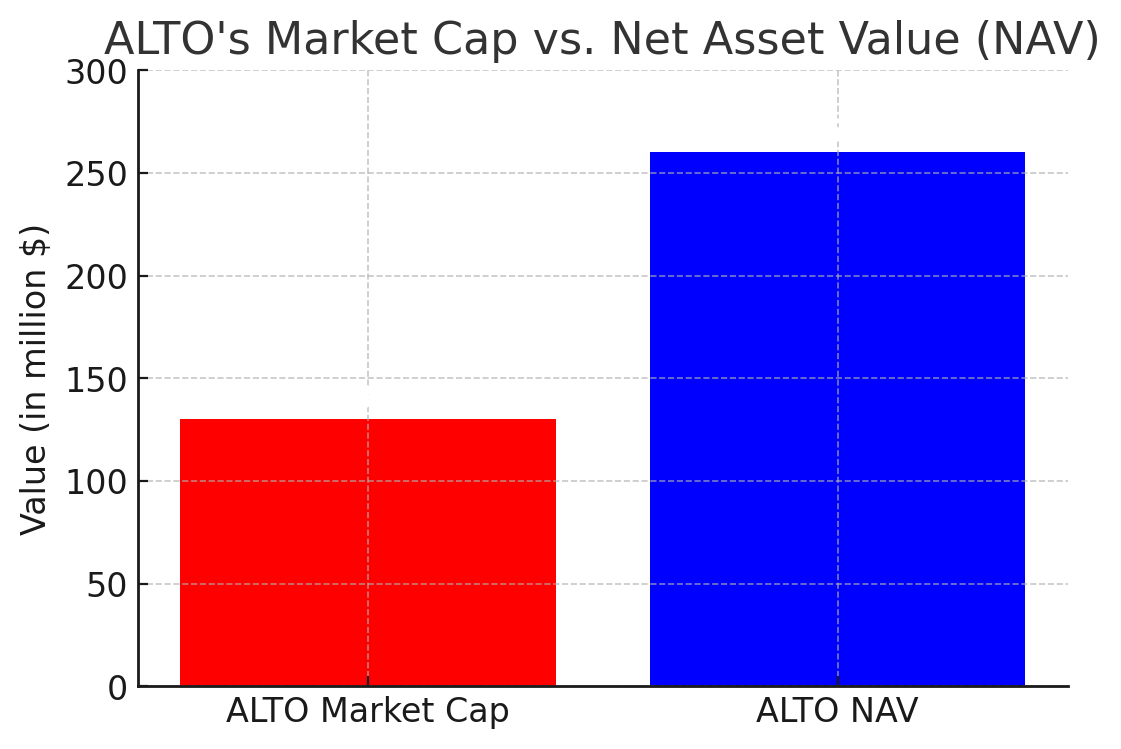
At minimum, $ALTO's tangible book discount (31%) should have closed vs. $GPRE (7%) by now. But it hasn't.
Mr. DCC retweeted
$PBI was trading at $9.10 when Kurt Wolf negotiated his incentive structure.
Instead of opting for $3m of shares, he asked for $3m of options with an average strike of $14.
This is a bad trade unless he believes the stock is going higher than $23.10.
$PBI's convertible note strategy included capped calls that prevent dilution up to a share price of $22.36, which was a 100% premium to the share price at the time ($11.18). Setting the cap this high cost millions of extra dollars. There's no reason to do this--unless Kurt thinks the stock is going to at least $22.38.
Kurt's original 10b5 plan, initiated in December, allowed him to sell about half of Hestia's stake in $PBI by the time it reached $14. He cancelled this plan in May.
Now he's being paid in call options that, on average, don't even go in the money until $14.
Speaking of doubling down, Permit Capital (part of Hestia's activist group) raised their stake in $PBI by 19% this summer, buying shares at a ~200% premium to their original cost basis.
I think Kurt learned or realized something between December and May that substantially raised his expectations for $PBI's future.

Mr. DCC retweeted

Check out my latest article highlighting $pbi as a top pick and noting its similarities to how the Gamestop $gme played out in 2021.
hiddenrockcapital.substack.c…
Mr. DCC retweeted

the $PBI story is complex, but all you really need to look at is that despite falling top-line (due to accounting changes + some 'temporary' biz headwinds), EBIT grew $28M and the CEO has enough confidence in that EBIT trend to go all-in on buybacks


Mr. DCC retweeted
Excellent article about Kurt Wolf / $PBI.
Wolf: "There is so much opportunity at Pitney Bowes, and we have the right business leaders and employees to realize the potential in front of us.”
ctinsider.com/business/artic…


Mr. DCC retweeted

5/ Bradley Radoff
Experienced small-cap-only activist. His playbook centers around gaining control of the company through board reshuffling with the subsequent improvement in the governance structure. In some cases, he pushes for the break up of the company or an outright sale.
Mr. DCC retweeted

$PBI Crew. Next monster opportunity is $ALTO. Bradley Radoff just filled a 13D to help lead board / command take over just like he did with $PBI and Kurt Wolf. Beteeen @DOMOCAPITAL, Radoff, and Kaufman they now own over 17%
sec.gov/Archives/edgar/data/…
Mr. DCC retweeted

New #equityresearch on @PitneyBowes $PBI published 2/12/2025 #sidotiresearch
Read Note: buff.ly/3tamndX
#investing #investors #stocks #stockmarket #stockresearch #smallcap #microcap
Mr. DCC retweeted
🚀 With all the recent buzz around Pitney Bowes ($PBI) I wanted to take a trip down memory lane and give those new to the story why I am so confident we are in the early innings here and why I see this at $15+ by year end: @DOMOCAPITAL @crowdturtle @violacapital
Mr. DCC retweeted
Every major $PBI development since October 2, 2023 has been 100% foreseeable, but only a handful of people realized that Hestia's plan would commence unobstructed following change in control.
The content of these press releases was known years ago. We just didn't know the dates.
Mr. DCC retweeted

A @Playboy story in two parts. If you believe this management team will buy back stock and won't use their shelf offering, I have an NFT ticket on the Big Bunny to sell you. @NewYork_SEC, does this look like someone trying to lure retail investors? $PLBY @InvestmentTalkk @siyul


Mr. DCC retweeted

Hedgeye Retail ahead of the Wall
Analyst Actions: Wedbush Adjusts PT on Advance Auto Parts to $210 From $180, Citing 20%+ Annual EPS Growth Potential; Outperform Rating Kept
MT NEWSWIRES 5:57 AM ET 4/16/2021
@HedgeyeRetail @HedgeyeRetailJM @Hedgeye $AAP