
Emerging Technology Researcher | Former Ethereum Core Developer | Former Besu and Teku Protocol Engineer @PegaSysEng @ConsenSys
Texas, USA
Joined October 2018
- Tweets1.6K
- Following411
- Followers770
- Likes4.1K




For @XMoney users that subscribe to @X Premium (and not Premium+) don't have regular W2 income/direct deposits, such as retired folks, would recurring ACH transfers from another owned account qualify?
Not sure how one would find if the SEC code was PPD.
money.x.com/en/i/interest-fa…

This does seem disingenuous to me while many are making up their minds wrt AI watermarking.
xitter.cf/anthropicai/status/208…

I've spoken recently about the @XMoney card, my largely positive experience with it. In so doing, I've mentioned my background as a billing and payments technologist. So, without further ado, let's begin our deep dive series on credit and debit card processing in the US. 🧵(1/6)
🤖 Made with AI

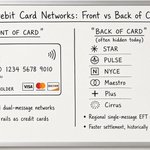
These networks, as opposed to the global dual-message networks, are the regional/domestic single-message EFT networks.
The process is similar from the perspective of the payment terminal: you swipe your card, it identifies the global "front of card network" (i.e. Visa, MC, etc.) based on the BIN, but it also identifies these other "back of card networks" associated with the debit card. The merchant then uses a lowest-cost routing (LCR) engine to determine which payment network to send that payment on. If the LCR chooses one of the "back of card" EFT networks, then the two-step process is simplified in to one. When the issuing bank returns the authorization message to the terminal, an EFT transfer to the merchant's bank happens alongside it.
Historically they always required an encrypted PIN-block to be sent as a part of that single-message, but recently they've allowed limited PINless utilization, subject to additional checks/requirements. This is why you probably notice transactions at stores where you've entered your PIN settle much faster than those without.
As an aside: And all debit cards will have at least one (but often multiple) "back of card" EFT network not associated with the global "front of card" network, it's required by law under the Durbin Amendment. 🧵(5/6)
🤖 Made with AI

And with that, it's probably time to end today's installment of the series. We truly have just scratched the surface, and I look forward to delving deeper in to the tech with y'all.
That said, despite this being my bread and butter, these do take quite a while to write. While I use AI to help me generate the nice whiteboard diagrams, all of the explanations (and therefore the prompts to generate the images) are hand-written.
If this has proven useful to you, then I would be honored to earn your follow. I intend to add new content to this series twice a week, getting more in depth as we go. And if you have any questions or feedback, I am always willing to chat. (6/6)
3/4 of the way to 1k! Thank you everyone! I am grateful. 🙇♂️
I'm not an influencer, nor do I desire to be. Just a regular guy who likes to collaborate and share my experience, having spent a career developing billing and payment systems - both decentralized and traditional.

Like, seriously y’all. 30 minute response on a Saturday evening. 🤯
I know @X has its issues (and what large company doesn’t), but what more do you need to demonstrate that the @XMoney team really does also walk the walk.

I think I found another small bug (or just lack of documentation) on @XMoney. To be clear, I'm extraordinarily happy with it. The fact that @dbatura is so responsive is a testament to @X's commitment to the product. But, me being the good beta tester that I am (and one with billing/payments development experience), I feel compelled to report things as I see them.
This particular bug (or again, just a lack of documentation/understanding) concerns selecting accounts to be associated with a card. If you select an account to point a card to, when that transaction is authorized, it does authorize against that account. However, if you change that selection back before the charge is captured, despite being authorized against one account, the actual charge is captured (settled) in the account that was selected at the time settlement was made. My expectation was that the debit would settle in the account that the auth happened in, which was the account selected at the time of the transaction. Turns out that's not the case, and that either needs to be fixed, or better documentation.
This also means I've also been an unintentional beta tester of the NSF/negative balance flow. Notification popped up, I was confused for a sec, noticed the unexpected behavior documented above, moved funds between my accounts on X, and all good. That said, I'd rather not have been a beta tester of that flow - and a bug fix or better documentation can prevent others from encountering the same message.

And just like that, no one's talking about the cost of a burrito anymore.
help.x.com/en/using-x/creato…
help.x.com/en/using-x/origin…

So, uh - what did (or didn't) @telegram do to get banned from the @Apple App Store?🤔
I get that it's used for encrypted messages, and that's contentious lately for some reason, but so is @WhatsApp, @signalapp, @session_app, and even iMessage for that matter.
AI is interesting because it can synthesize and test thousands of different paths in the time that a humans would need to even begin understanding the problem.
Where AIs are not optimized, though, is creativity. Creativity in AI comes from randomness and statistics. But, in some ways, the creativity is limited. AI is goal oriented, and its creativity is only along with and in furtherance of that goal.
Where humans excel is the sort of creativity that comes completely out of left field. Wild, harebrained, truly imaginative ideas, seemingly unrelated to the problem at all.
That's why, IMO, for the foreseeable future, AI will exist as a wonderful supplement for humans - allowing them to perform iterative thought work with the help of the AI, while remaining (at least relatively to before) mentally offloaded allowing capacity for true imagination and creativity. #ai #math #research #riemann #creativity #imagine

This is a great example of why a (non-deterministic) LLM is not a panacea, and why good ol’ fashioned deterministic APIs are still necessary. The trick is determining when an application does or doesn’t require strict determinism. That is software engineering.


The US vs Aus soccer ref is cramping up and the announcers are blaming the heat in Seattle. Um...it's literally 80º in Seattle. That was the overnight low in Texas last night.
I feel for the ref, cramping is no fun and dehydration is no joke, but let's not pretend 80º is hot.