

Long-biased microcap stockpicker. Author of Byron Street Research. Read my disclaimer on each report.
Joined May 2023
- Tweets728
- Following1.1K
- Followers11K
- Likes2.2K
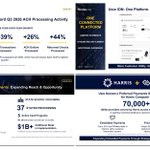




3-4 wks of news flow ahead for $USIO. Starting today at LD Micro, followed by Planet MicroCap next week and earnings shortly after. The updated deck has just been filed.
“During his remarks, Mr. Hoch will comment on third quarter performance of the Company’s ACH business, the company’s highest-margin business line, which set all-time quarterly processing records, surpassing second quarter 2026 performance, which was ACH’s previous best quarter. Compared to a year ago, third quarter 2026 ACH transactions processed grew 39%, dollars processed grew 26% and returned checks processed were up 44%.”
Re the school voucher programs, USIO has already been deployed in 5 states, w/ a 6th larger currently in implementation. The recently announced Harris deal is even larger (huge actually) and the company will start moving bigger accounts onto ION, an almost 100% margin product, next year.
In short, I expect a very strong beat-and-raise Q3.
SG&A should stay mostly flat for a year, if not longer. Just organically, that gets you to $0.35-0.40 in 2027 EPS. With Ohio, ION and Harris, the number could get silly but I’ll risk a prediction: sooner or later, USIO will get acquired @ ~$5.00-6.00+.


Really strong quarter for $USIO. Record processing volumes & transactions. Significant EBITDA beat and rev guide raise to +14-16% (still v conservative given H1 was already +17% and new programs are just ramping.)
3 of 4 segments grew 20%+. Gross margins up 400bps sequentially to 24% (mgmt comfortable in 23-25%, ION could push that further). SG&A down yoy despite the growth. 2nd consecutive quarter of profitability.
H2 setup is even better. School voucher programs (now ~5-6 states, up from 2, w/ one state alone ~$1.2B) ramp w the new school year + a university loan refund program (partner already serves 30 unis) goes live in H2.
Revs should accelerate from here and bottom line should follow. Expecting ~$8M in EBITDA this year and $13-14M+ next, which puts them on track to do smthing like $0.40 EPS in 2027.
Biz is almost all recurring, no customer concentration, high retention. NACHA data show strong ACH growth w USIO running ahead of the industry the last several Qs.
Trades <1x revenue. Can really take off from here.
Liger Cub retweeted

Good post on $USIO. Company doing good job on beginning to show op leverage with top line growth around 20% today with real additional growth drivers coming and keeping SG&A fairly flat.

We continue to like $USIO even after the recent runup.
The company should continue to grow 15%+ simply from its existing customers growing. Then you layer on top of this new partnerships like Harris, new opportunities like the state and school voucher programs, and new products like Usio Ion (rolled out 2027 could materially impact bottom line) and there are several green shoots that could be additive.
To give a sense of how big the green shoots are. If USIO was able to secure just one medium to large sized Utility, for example, CPS Energy out of San Antonio has 1.3m customers average bill $175/month that is $2.75 billion in annual processing. USIO did 9 billion in total processing in 2025.
In addition, we believe this company will eventually be acquired (within 3 years) by someone like Harris. USIO currently doing ~$100 million in sales. The average multiple in this space for a company 100m-300m is ~2x sales.
Disc: Long and wrong a lot
Liger Cub retweeted

$USIO another record quarter in ACH. Can't wait to hear more.

Usio's presentation at LD Micro Main Event XX will take place on Tuesday, October 20, 2026, at the Luxe Sunset Boulevard Hotel in Los Angeles, California. Usio's presentation is scheduled for 5:00 PM ET and will be available via live webcast at na2.hubs.ly/H08lVZ-0. For registration information, please contact [email protected].

Travelzoo ($TZOO) is being priced as if its new membership model doesn’t work. The stock doubled in April following strong Q1 results, then fell ~50% after Q2 as CAC jumped and reported profitability disappeared. It currently trades near its lows for the year.
In detail, membership fees are recognized ratably, while acquisition costs are expensed upfront. New cohorts depress reported earnings today, but renewals deliver high-margin revenue later.
In Q2, TZOO recorded the highest number of membership renewals in its history. In response, mgmt decided to step on the gas and double their investment in member acquisition right when the EPS drag from the transition narrowed from -$0.15 in Q3 2025 to -$0.08 in Q4 and -$0.04 in Q1 2026.
Right now, the Meta Ad Library shows heavy activity since late September into early October w high engagement and additional placements at the NY Post, HuffPost, Fortune, and The Sun. Instagram followers are also up ~12% in 3 months.
Mgmt guides for an incremental EPS impact of -$0.60 in 2026 and +$1.20 in 2027. At $5.31/share, TZOO trades at less than 5x that incremental 2027 EPS alone.
Q2 CAC was $62 on $4.6M of marketing spend (~2x the prior quarter avg). The spike reflected macro conditions and should normalize (i.e. it does not represent a new baseline).
Dividing marketing spend by CAC shows quarterly members acquired oscillate around 70-75K. If CAC comes down, that $4M+ expense won’t be the new norm.
The new member platform is growing fast and member LTV is likely a multiple of CAC. It’s simple math and they’re accelerating the growth trajectory now.
Semrush estimates Travelzoo.com visits increased from 4.50M in June to 4.73M in July and 4.93M in August (+10%). Downstream data confirms this. For example, TripToGo (an advertising customer) saw a sharp traffic increase w 31.3% of its incoming desktop traffic coming from Travelzoo.com in Q3.
Q2 advertising revenue declined partly bc TZOO sold fewer insertion orders while prioritizing memberships. Still, the company’s deal feed showed campaigns continuing through September from Exoticca, Princess Cruises, Windstar, Avalon Waterways and others.
Post-quarter end, the industry backdrop improved. US travel-agency air-ticket sales hit $9.6B in July (+18% yoy) and a record $9.8B in August (+19% yoy), w August passenger trips up 5% yoy. BKNG, EXPE and ABNB all beat in Q2. TUI raised the low end of its guidance on Sept 22. Hotel RevPAR guidance was raised again.
The travel hesitation in April and May eased as Q3 progressed. As mgmt noted, June was strong and July was even stronger. August and September data point to a continuation of that trajectory.
TZOO estimates ~$17.2M of 2026 membership revenue (excl. Jack’s Flight Club), implying ~$10.25M in H2. A simple ramp implies ~$4.6M in Q3 and $5.6M in Q4.
Mgmt guided for a return to yoy revenue growth in Q3. The latest investor deck implies ~$30M in membership fees on ~$100M revenue for 2027 (I think it will be much higher).
TZOO repurchased 200K shares in Q2 at prices above $10, then bought 200K directly from the CEO on Sept 28 at $5.64 (he had bought those in February at $5.39 - this back and forth has happened before). Insiders still own ~45% of the company and the CEO holds 1.6M options.
As of June, 300K shares remained under authorization. TZOO repurchased 30K through Aug 7 and another 200K directly from the CEO, leaving ~70K. A new authorization is likely imminent given the pace.
Importantly, this member acquisition and buyback activity happened while mgmt guided for a rebound in its cash balance from the $7.6M reported at Q2 end.
Membership fees currently run at ~$25M annualized (growing 60%+ yoy with high incremental margins). At 3-4x revenue, that’s $75-100M. A ~$75M advertising business at 0.5x revenue adds another $37.5M. That’s a rough SOTP of ~$112.5-137.5M, more than double its ~$54M market cap today. The company has zero debt and $7.6M cash at quarter end.
In summary, mgmt guided to yoy revenue growth in Q3, said ad-offer restrictions are past the worst of it and stated cash would be higher. Q2 CAC was higher than prior quarters and should normalize. Marketing spend doubled to $4.6M bc the model is working. Q2 renewals hit record highs and deferred revenue kept ramping. Their META product is launching imminently as a possible catalyst.
Expectations have been completely stripped out post-Q2, leaving very little room for disappointment while offering significant upside if membership economics play out. I haven’t found a single datapoint explaining the magnitude of the recent selloff. Available evidence points to sequential improvement in Q3 and explosive EPS potential.
Disc: VERY Long
Liger Cub retweeted

Some good sources of stock ideas from @BullpenDotNews.
Who else should be on this list?

Liger Cub retweeted

$TZOO estimates 2026 Travelzoo Membership revenue of ~$17.2M (without Jack's Flight Club)
Travelzoo 1H2026 (again without Jack's) Membership revenue was $6.9M.
$17.2M minus $6.9M = $10.25M for 2H2026
Assuming continued ramping, 3Q could be $4.6M and 4Q could be $5.6M right?

Last week, I joined the army for at least the next 9 mths.
Obv, until I manage to set up an army trading station, I won’t be able to dig into new ideas like I normally would. But I’m introducing the Liger Ceasefire in the meantime.
If I find or you send me a fat pitch, the Liger Ceasefire will be activated. At that point, the stock gets my full attention, regardless of whether shots are firing and grenades are exploding around me. Research comes first - everything else can wait.
If you have an idea you think deserves a Liger Ceasefire, send it to me via DM or at [email protected].
Liger Cub retweeted

Added 92 new stock write-ups to the site (pt 3):
@realLigerCub - $CDTI
@internpierre - $REAL (short)
@realroseceline - $TTD (watchlist)
@peterepstein2 - $SVRS.V
@AndrewRangeley (One Idea per Day) - $FMC
@stpioc - $LTRX (primer)
@StableBread - $DECK (earnings)


Liger Cub retweeted

$CDTI is super compelling even after this run. Amazing accomplishment here from @realLigerCub for digging it up and doing that leg work.
LAST IDEA BEFORE A 9-MONTH BREAK:
CDTi Advances Multi-Sector Catalyst Programs as Blue-Chip Partners Near Production
(1/17)
byronstreetresearch.com/p/cd…

Liger Cub retweeted
Back in $TZOO
Market treating stock like the model doesn’t work
Assuming modest improvements, think we see breakeven EPS, alongside continued deferred revenue build (~$2M qoq)
Could result in cash flow positive quarter ($2M +) indicating the model works
Could see $10 again?

Liger Cub retweeted

$CDTI: $7.7M market cap, two employees named on an ExxonMobil patent, one of six on the MAMII shortlist. Byron Street covered it well. I went into the audited financials and found the US segment loses money while Europe carries the profit, plus $804K of cash against $700K of annual burn. Base $5.85, bull $19, bear a dollar. Long at $1.71. No paywall.
guardianresearch.substack.co…

LAST IDEA BEFORE A 9-MONTH BREAK:
CDTi Advances Multi-Sector Catalyst Programs as Blue-Chip Partners Near Production
(1/17)
byronstreetresearch.com/p/cd…
There's more in the report I'm leaving out of this thread, but none of that shows up in the price.
At 0.7x trailing revenue, CDTi gets no credit for programs with immediate production-level activity and none for those still in other development phases. Even the legacy business alone is worth more than the market is pricing it at.
Management believes CDTi is at the early innings of a "transformative" multi-year revenue ramp. The data presented in the report backs that statement. Apply a multiple that reflects where revenue is headed, and setups like this don't come around often.
As @majgeoinvesting said: "The valuation is hard to ignore... a company doing nearly $10 million in revenue, generating positive operating income, and developing technology for one of the largest infrastructure buildouts in history, valued at less than the cost of a nice house in most major metros."
(16/17)
I am long shares of $CDTI. Please read my full disclaimer on the report.
$CDTI
(17/17)
byronstreetresearch.com/p/cd…