

Research on the world’s strongest companies (NFA). Join 1,900+ investors:
Groningen, Nederland
Joined August 2024
- Tweets708
- Following321
- Followers1.1K
- Likes918



Pinned Tweet
I just published a new investment letter, including an overview of my current portfolio, my thoughts on three core themes for building a sound portfolio strategy, and why I favor a concentrated portfolio over a diversified one.
massivemoats.substack.com/p/…


This episode has video on Netflix.
An exclusive deal between two of my favorite companies @AcquiredFM & @netflix 🤝


Some thoughts on Hermès $RMS.PA.
If France’s current trajectory continues to deteriorate over the coming years, what could that mean for French companies like Hermès? Beyond the risk of higher taxing on successful companies, could political instability and social unrest gradually change how consumers worldwide perceive “Made in France”-brands like Hermès, as they do not want to be associated with France its decline?
Hermès’ French origins sit at the center of its brand identity and anchor its IP moat: Parisian elegance, craftsmanship, and heritage. So what happens if France continues to loses its prestige?
Can Hermès transcend its national context and stay insulated from a weaker image of its home country? Or would the brand’s status slowly erode as the nation loses its allure and, perhaps, even its culture?

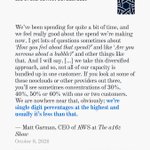
I believe the market currently overestimates the value capture at the model layer and underestimates the value capture at the data center layer.
Jensen Huang (CEO of NVIDIA $NVDA) on why future AI usage will take a lot more inference than the LLMs we know today:

I run a concentrated portfolio. What is not visible from the outside is that I research new prospects almost every day. Lately, I have not found a new idea as strong as my top positions. This is the primary criterion, because I do not want to dilute the portfolio with mediocre ideas. I do not want to add positions merely for the perceived benefit of diversification; I only want top-tier, alpha-generating ideas.
One thing that might differentiate me from most professional investors is that I have a different perspective on risk and do not feel the urge to add new companies just “to feel important” or to chase the currently popular “momentum waves.”
I remain calm. My goal is to expand the portfolio to 6–8 positions in the long term. I believe the right ideas are worth waiting for. While I keep searching, I am curious which recent ideas you are allocating toward that you consider truly exceptional.

In a recent episode of The Modern Investor podcast, @BillAckman shared his perspective on concentration in portfolio management. Some thoughts:
- Concentration starts with the proper set of knowledge. The more you know about investing and the businesses on your radar, the more opportunities you have to be a concentrated investor.
- In addition to the knowledge you have about particular businesses, which forms the foundation for well-grounded conviction, the ranking of positions in a concentrated portfolio should be based on risk and return.
- There is only a small number of incredible businesses with a certain scale. On certain occasions, these businesses trade at a discount. When this happens, provided that you have built up the proper knowledge over the years, you can do a quick assessment and swiftly decide whether to seize the opportunity offered by the market.
- In Ackman’s view, there is a maximum number of stocks to hold to properly benefit from concentration. Beyond 12-15 positions, the incremental benefits are no longer meaningful. In other words, one should ask whether, in a properly constructed portfolio, allocating capital to a new idea (e.g., idea 16) truly pays off compared to the top ideas, Nos. 1-3.
- A certain degree of diversification is still important, however, since investing remains a game in which the unexpected can happen, as Ackman concludes.
Watch the full interview here: youtube.com/watch?v=2kTVSQS2…

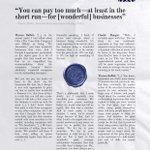
Warren Buffett and Charlie Munger at the 1997 Berkshire Hathaway Annual Meeting on wonderful businesses, their fluctuating valuation, opportunity costs, and the self-reinforcing nature of rising prices:

I think few investors who only recently started their investing journey fully grasp how enormous the dot-com boom and bust really was. Between January 1, 1995, and March 10, 2000, when it hit its all-time closing high, the NASDAQ Composite Index soared 571.4%, climbing from $751.96 to $5,048.62. It then collapsed by 77.9%, bottoming out at $1,114.11 on October 9, 2002.
To put that in perspective: after a 77.9% drawdown, an investor needs a gain of 353.2% just to get back to even.

In a recent episode of The Modern Investor podcast, Bill Ackman explained why he expects more attractive investment opportunities in high-quality companies in the years ahead. Three key insights:
📈 Rising volatility from indexation. The volatility in markets is rising due to the rise of indexation, with bigger percentages of equity stakes held by large index funds, which shrinks the effective float. As a result, the marginal buyer and seller will have more impact on price.
⚡ Short-term capital amplifies volatility. Short-term oriented investment strategies, deployed by firms like Citadel and Millennium, tend to capitalize on short-term events like quarterly earnings. This further exacerbates the movement of stock prices, both positively and negatively.
🏛️ Permanent capital is a big edge. Investors with permanent capital have a strong advantage, since they can buy into severely punished stocks and hold them as long as they like, without the perceived pressure to sell these underperforming stocks at the end of the year. This sets up high returns in future years.
Watch the full interview here: youtube.com/watch?v=2kTVSQS2…
I highly recommend reading the latest quarterly letter from Bristlemoon. Some thoughts:
Albeit tracking a net return of -34.8% over the past 12 months and describing a difficult period for the fund, Bristlemoon remains positive and sees immense value in its portfolio companies. Bristlemoon’s top 5 positions as of 30 September were: AppLovin, ASML, PAR Technology, ServiceNow and Timee.
According to Bristlemoon, the sharp price declines across a large group of individual companies partly reflect broader market rotations, which have directed capital toward a limited group of market leaders. For example, ~70% of the S&P 500’s YTD return of ~12.7% (TR) comes from the top 10 contributors, 9 of which are in the semiconductor and AI infrastructure sectors.
According to Goldman Sachs data, ~45% of S&P 500 constituents now have a negative 3-month beta, significantly exceeding the previous peak of ~18% in 2001. Bristlemoon believes this has caused a substantial dislocation between the share prices of the fund’s portfolio companies and their underlying intrinsic values.
Bristlemoon defined a fund manager’s traditional edge as Investment Skill = Information Gathering + Analysis + Judgment. It sees that edge disappearing in the analysis of information and shifting toward the judgment process, supported in part by proprietary data and investigative journalism (e.g., scuttlebutt, with on-the-ground insights via interviews and site visits).
I wrote about this earlier this year as well: the human factor is becoming more important, both in terms of psychological and behavioral skills for investors themselves and in assessing the quality and integrity of company management.
I have also written about the amplification I see in market narratives due to AI, and its effect on share price movements. Bristlemoon sees this exacerbating too. It expects that more investors will be able to use AI to analyze and act on the same information quickly. I believe this, in turn, can intensify both sentiment and movement around stocks, both positively and negatively.
I currently find myself in a similar position to Bristlemoon. While the S&P 500 is up more than 12% YTD, I stand at -6.5% YTD as of 30 September (TR). This is largely driven by my largest position, 3i Group, which lost more than 25% of its market value this year. Like Bristlemoon, I see considerable value in these non-AI companies that are lagging and significantly underperforming a benchmark index which is largely driven by a handful of semiconductor companies.
I therefore share the thrust of Bristlemoon’s letter: be patient, focus on intrinsic value, and in the meantime keep working hard to challenge your assumptions and strengthen your investment process to foster long-term results. In the end, what matters is who goes the furthest, not who makes the fastest start.

We published our September 2026 quarterly letter, with the Bristlemoon Global Fund returning -8.4% for the September 2026 quarter, with a -5.9% return for the month of September 2026, net of fees. We are not happy with these results and they mark a very disappointing last 12 months for the Fund. While we remain excited and optimistic about the Fund's holdings, many of these stocks have continued to derate to depressed levels, despite robust fundamental performance those businesses. We look forward to a time when we can report better news.
In the letter we discuss the lack of market breadth, how AI is commoditizing analysis, and outline our theses on 4 shorts: $CPB, $REA AU, $MBC and $PII.

In his latest memo, Shall We Repeal the Laws of Economics – Part III, dated September 22, 2026, Howard Marks addresses the interplay between rising demand for capital, higher interest rates and inflation. These dynamics are being driven by a strong economy, massive investments in AI, and substantial government debt and deficits. Some thoughts:
Howard Marks highlights the sharp rise in the yield on the 30-year U.S. Treasury bond, which reached 5.3% on August 17, 2026. Since then, as of October 12, 2026, the 30-year U.S. Treasury yield has climbed further to 5.6%, its highest level in 24 years.
With U.S. federal debt now exceeding $40T and substantial government deficits (~$2T for FY2026, ~6% of GDP, with ~$1.3T in interest costs), inflation in the U.S. is further being fuelled. This is happening at a time when the economy is running at near capacity (e.g., with an unemployment rate of only ~4%). The incremental liquidity created by this situation (i.e., government spending > tax revenue) stimulates economic growth and, in turn, inflation.
At the same time, enormous investments are being made in AI. In recent years, these investments have largely been financed through companies' existing cash balances and OCF, including those of hyperscalers. These companies are now increasingly raising capital themselves through the issuance of debt and equity. This further increases the demand for capital, and with it, the price of capital.
Given the high levels of government debt and deficits, alongside interest expenses that continue to rise as a proportion, it is reasonable to question the sustainability of this trajectory. According to Howard Marks, a change in behaviour is the only long-term solution to prevent the situation from deteriorating further. The hope, therefore, rests on the U.S. government adopting a more fiscally responsible approach, including steering toward a lower growth rate in government spending than the growth rate of GDP.
Hereby, AI could become part of the solution. AI could help accelerate U.S. GDP growth in two ways: first, by stimulating economic activity through AI-related investment and, second, by driving further productivity gains.
Should we sell our stocks?
This is a question Howard Marks was recently asked by a fellow entrepreneur. In Marks' view, this is not where the answer lies. The problems do not concern the U.S. stock market or U.S. companies, but rather U.S. fiscal management and, by extension, the U.S. dollar. According to Marks, a potential risk lies in the latter: investors could become less comfortable with the USD and, therefore, could begin seeking assets denominated in other currencies. However, doing so would generally entail a different set of risks.
Personally, I believe it is useful to reflect on these issues from time to time. This in order to identify the potential second-order effects that may emerge. These could affect certain companies in our portfolios or on our watchlists. That said, investing ultimately comes down to allocating capital in businesses that can generate long-term TSR in excess of the rate at which the purchasing power of our capital erodes. After all, this is the foundation for increasing the purchasing power of our capital.
History teaches us that economic growth, inflation and currencies can fluctuate considerably (with currencies even being replaced). In my view, the greatest risks do not lie in these factors themselves, but in the quality of the value-creating mechanisms—the businesses—in which we choose to invest.
The best companies in the world will succeed in continuing to create value even during periods of severe monetary, fiscal or government-policy turbulence, drawing on the physical, digital and intangible assets they have built and continue to develop across the many countries in which they operate. Perhaps, these assets will become even more valuable during times in which the value of money appears to be under increasing pressure.

Read the full paper here: oaktreecapital.com/insights/…
Great paper by Michael J. Mauboussin and Dan Callahan (Morgan Stanley, 2026) on FCF, ROIC, and ROIIC, the relationships between them, and the market’s current expectations for these metrics at hyperscalers. Some thoughts:
- Periods of large negative FCFs resulting from capital expenditures (CapEx) can have an extremely positive effect on total shareholder return (TSR) if the return on investment (ROI) from these efforts exceeds the cost of capital.
- The spread between ROI and the cost of capital determines whether it creates (+) or destroys (−) incremental intrinsic value for companies.
- Ultimately, TSR depends on changes in extrinsic value, but over longer periods, it is strongly correlated with the trajectory of intrinsic value. Although negative FCF resulting from CapEx can create financing challenges, intrinsic value can soar if the cash is deployed in investments that generate returns above the company’s cost of capital (e.g., Walmart generated substantial negative FCF from 1973 to 1986 while delivering a TSR of 33% CAGR during that period).
- However, if (parts of) large CapEx outflows do not immediately translate into incremental revenue, a company’s return on invested capital (ROIC) can temporarily decline as a result of lower return on incremental invested capital (ROIIC) driven by a time lag between investment and returns. This could happen to a hyperscaler such as Amazon in the coming quarters, given its substantially expanding invested capital (IC) base and the lead time before the resulting investments translate into net operating profit after taxes (NOPAT).
- It is therefore important to estimate the total incremental NOPAT generated over the lifetime of an investment, rather than judging CapEx solely by its immediate impact on KPIs such as FCF or annual ROIIC. In other words, it is important to look beyond the horizon to assess companies’ long-term value-creation mechanisms.
- Meanwhile, we should remain vigilant about automatically endorsing large investments simply because they have a positive net present value (NPV). Changes in a company’s value-creation mechanisms and their potential impact on its overall valuation are even more important.
- As investors, our job is to determine whether the market overvalues or undervalues companies’ FCF prospects, the underlying capital expenditures required to achieve them, and the returns those investments are likely to generate. After all, alpha is created by identifying mispricing between the intrinsic value and the market’s extrinsic valuation of a company.


Read the full paper here: morganstanley.com/im/en-us/i…
Warren Buffett and Charlie Munger on portfolio diversification at the Berkshire Hathaway Annual Meeting in 1996:

Revenue generated by Anthropic through its cloud partners, Amazon ($AMZN) and Alphabet ($GOOGL), has increased in recent years, according to Reuters, which reviewed a copy of Anthropic’s confidential IPO filing in September. According to this report, the share of Anthropic’s total revenue generated through Amazon and Alphabet rose from 11% in 2023 to 32% in 2024 and 47% in 2025. Anthropic reportedly pays a commission of roughly 16% on revenue generated through its cloud partners.
