

Head of China Research & APAC Chief Rep @iif; Formerly Tudor Investment, Evercore ISI, and Citics.
Singapore
Joined February 2017
- Tweets422
- Following289
- Followers3.6K
- Likes332
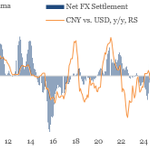
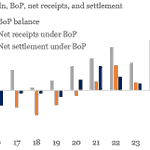
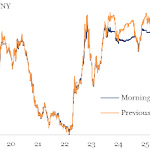
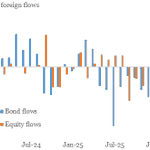

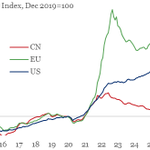
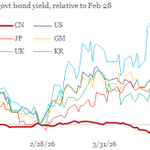


Chinese bonds, equities, and the currency held up well during the Iran shock, especially compared with many Asian peers. CGB yields fell, Chinese equities outperformed most regional markets, and the CNY was among the more stable major currencies.

More importantly, Chinese financial assets have exhibited relatively low correlation with major global markets over the past decade.


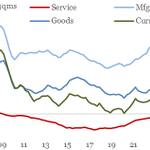
China’s goods surplus has become the focal point of the global trade debate, but the more interesting change may now be occurring in services.
Why China’s services trade matters for global imbalances weforum.org/stories/2026/05/… via @wef


Commentary: How China and Europe Should Manage Their Trade Tensions caixinglobal.com/2026-03-13/…


Three examples of weak domestic sales but strong exports are rebar and cement, which suffered from plummeting construction and investment, and ICE cars, which domestic consumers are abandoning.
