

Currently searching global public markets for alpha. Not investment advice.
Joined February 2012
- Tweets1.7K
- Following247
- Followers1.1K
- Likes1.6K



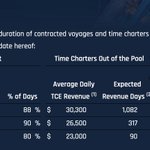

Excited to release a sub tomorrow about one of my largest investments.
It's a company that looks like it's trading at 10x earnings, but current run rate reality is 2-3x.
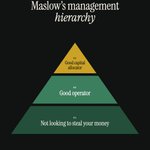
What's misunderstood? They won a contract that hands them an effective monopoly that few are pricing in. Furthermore, as is a necessary precondition of any investment of this size - it has a great shareholder friendly capital allocator at the helm.
It has been a good streak with recent publications - hopefully, this continues it.

I'm biased toward smart people who are non-promotional and continue to hit the nail on the head within their areas of expertise.
@morganhousel is one of those people and his straight talk podcast is one of the most underrated available: youtube.com/playlist?list=PL…

Tour de force by Ray Dalio walking through the bond market: raydalio.substack.com/p/the-…
Solitron Devices ($SODI): Released Q2 (ending 8/31) after the bell. Great cash conversion and demonstrated operating leverage.
Management is keeping the costs low and letting the business demonstrate how it can generate cash - OCF for the last two quarters is $3.6M vs $777K a year ago (on very little CapEx). Backlog continues to provide good forward visibility.
They paid a banker $200K in quarter and they're delivering them a runway of solid results to pitch the company.
To quote: "we anticipate sales to continue to be at this level or greater for the remainder of the 2027 fiscal year."

Solitron Devices ( $SODI ): I've been accumulating shares. High floor, good r/r imo.
They announced a strategic assessment last month and are a beneficiary of the nightmare in the ME. Solitron is a manufacturer of high-reliability power transistors, silicon carbide MOSFETs, and power/control hybrid circuits for weapons systems that include AMRAAM and HIMARS. These systems are bottlenecked by supply.
@eriksen_tim is CEO, and announced a strategic review (attached) on February 3rd outlining all paths to create shareholder value. Including a potential sale.
Since all the bullish news, the company is up less than 20%.
Fundamentally, the business inflected in Q3 and should continue to lap at an impressive pace. Backlog was up to $28.3M before the war, up 100%+ and 2x TTM rev. DYODD.
Here is a short article about the opportunity: open.substack.com/pub/underl…

"We have a crisis of leadership in America because our overwhelming power and wealth, earned under earlier generations of leaders, made us complacent, and for too long we have been training leaders who only know how to keep the routine going. Who can answer questions, but don’t know how to ask them. Who can fulfill goals, but don’t know how to set them. Who think about how to get things done, but not whether they’re worth doing in the first place. What we have now are the greatest technocrats the world has ever seen, people who have been trained to be incredibly good at one specific thing, but who have no interest in anything beyond their area of expertise. What we don’t have are leaders.
What we don’t have, in other words, are thinkers. People who can think for themselves. People who can formulate a new direction: for the country, for a corporation or a college, for the Army. A new way of doing things, a new way of looking at things. People, in other words, with vision."
-- William Deresiewicz

Glad to call Arno a friend. His new fund is well worth a look!

What a month. Depending on who you ask, I did something brave or borderline crazy: I launched a global deep value fund. And what a time to do it. That said, is there ever a good time to launch a deep value fund?
I’ve come a long way from my anonymous Deep Value Situations account days, tweeting about obscure setups behind a 90-year-old Walter Schloss avatar. Starting the account was probably the smartest thing I’ve ever done. I will forever be indebted to the FinTwit community – it opened more doors than I could have imagined and put me in touch with brilliant investors all over the world. It’s how I met Jan van Niekerk and Piet Viljoen, who gave me a shot to become a professional investor and sharpen my deep value DNA. Now, with RECM as my partners, I’ve launched the Maxia Value Fund – a Mauritius-domiciled “Expert” fund.
Over time, I will share more details about my journey, investment philosophy and the fund.
In a nutshell, I am running a highly concentrated portfolio of deep value situations that are more of the 70s Buffett persuasion than those of post-Depression Graham. The fund structure is quite simple. Despite full flexibility and an unconstrained mandate, my approach does not rely on leverage, shorting stocks, exotic derivative speculation, macro bets or chasing faddish themes and momentum.
Almost invariably, portfolio candidates are:
- Undiscovered and out-of-vogue businesses operating in boring industries.
- Industry leaders in emerging and frontier markets.
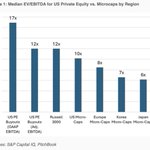
- Almost exclusively small or microcaps that often have no sell-side coverage.
- Collateral damage in a regional orindustry-wide crisis. When headlines scream “uninvestable” I really get to work.
Maxia is a small and nimble investment outfit – operationally very much like the original investment partnership setups of a young Buffett and Walter Schloss. With a one-man investment committee, I am a lone wolf and relish the ostensibly tedious work of combing through entire stock exchanges, A to Z – reading the filings and annual reports of businesses most investors have never heard of.
Virtually all of my net worth is invested alongside fellow investors. These are humble beginnings; however, I have no intention of becoming yet another institutional-like asset gatherer. I am also selective aboutwho I partner with – the right partners share my investment philosophy and think in years, not quarters.
More information and important disclaimers regarding Maxia Capital Management and the Maxia Value Fund are available on the website (link in bio). Fund information is restricted to expert and sophisticated investors as defined under Mauritian securities regulations and, in South Africa, to qualified investors.
~3x earnings (slightly net cash) for a business tied to oil and gas in Western Canada.
What gives? Primarily a minority interest (that has the largest market share in a valuable niche) went from loss making to generating significant profits. It’s equity-accounted, so it misses the screens.
This asset alone is worth the current share price in my opinion.
To be a great investor, being a contrarian is overrated. It's much more important to be an independent thinker.
A lot of the investment ideas that are being pitched are just recycled thinking (even in micro-cap land). Establish your edge and attack it.
The dislocations in the oil and gas ecosystem right now are absolutely incredible (up, mid and downstream).
To give an example of the upstream producers, there are two aspects investors that are critical to factor into your perspective.
1) What is their average realized price relative to WTI / Brent?
2) Are they hedged?
The business I wrote up is unhedged and received an $8 premium to Brent in Q2. If that persists (as I expect it will), that incremental translates into 20%+ of their EV based on guided production over the next year.
Least expensive oil producer thesis is playing out:
- Trades at 8x EV/E this QUARTER (ended June)
- FY Production guided to increase 15-20%
- FY CapEx guided to decrease 25%
I have them earning current EV in FCF at $75-80 Brent over the next two years.
Aimia ($AIM.TO ) update: They've disclosed being a 5%+ owner in two UK companies. Ownership recently moved from:
NWF Group: 6.56% -> 9.26%
Foxtons: 6.9% -> 7.1%
I own shares in NWF. 4x EV / Operating profit. Three attractive platforms (Food has very underrated potential). Industries are actively consolidating at much higher multiples. Juicy dividend goes ex at the end of the month. Full write-up is on the sub.
Aimia ($AIM.TO) started trading in London today.
I think three targets stand out as likely buyout targets. Each is outlined in my updated sub, two are investments.
I'll be surprised if they do not move on their first buyout under Rhys shortly.
The Mag 7 in the United States: Trade at an EV of close to $25T with an EV/E of ~27x and an EV/FCF of ~60x.
There are much easier games to play. Go small, know the names well, demand a margin of safety establish rapport with management and have a clear thesis you hold yourself accountable to.
I hate fees. So I ran a little experiment: held $GRVY at four brokers to see what each actually paid me, net per share, on the ₩4,400 dividend in September.
Gross: $3.2045 per share at each of them.
Net per share:
• Schwab: $2.648
• Fidelity: $2.648
• E*TRADE: $2.480
• IBKR: $2.480
It wasn't the fees. Schwab and Fidelity charged the higher ADR fee (2.75¢ vs 2.0¢) but withheld Korean tax at the 16.5% treaty rate. E*TRADE and IBKR withheld 22%.
If you are collecting dividends on international securities, make sure your broker is deducting the correct amount.
Tankers have been a great trade. I continue to hold FRO, INSW and TNK.
At a ~$30 cost basis in FRO, they're on pace to throw off close to 40% of that in dividends through the end of the year.
$TNK continues to trade too low, imo. A couple aspects re: the thesis:
1) oil markets are dislocated. Barrels that are online cannot get delivered to the buyer willing to pay the highest price... creating a huge arb opportunity for those able to buy the supply and book the boat (causing price insensitivity: the boat fee is a drop in the bucket for the cash they're making). It also adds significant distance to overall charters as routes are longer - e.g. as India sources barrels from the US vs Saudi Arabia.
2) high exposure to spot rates.
3) the balance sheet is a fortress with a third of the market cap in net cash.
4) significant VLCC capacity is trapped and they're too big to re-route through channels like the Suez canal and around the Cape. That displacement is pushing charterers toward Aframax and Suezmax tonnage - TNK's wheelhouse.
I don't see the dislocation resolving soon. The infrastructure damage isn't a quick fix.
Take this and multiply it for the issue with finding LNG carriers. I just can't find any good investments to take advantage of the perceived opp (DM me if you have any ideas!).
Next profile tease: A company that trades at 10x earnings won and is operating an incredibly lucrative long-term contract that makes the current run rate multiple 2-3.5x.
Run by a strong capital allocator with significant skin in the game, I expect shareholder returns to be significant a couple years down the road (if they aren't taken private).
This is one of my largest holdings.
The History of the World: A phenomenal way to pull together your understanding of different times/eras of human civilization. It helped me form a better linear understanding of how they all fit together.
Furthermore, tons of new learnings make this one of the most heavily underlined and note heavy books I’ve read.
I highly recommend.
