

AI Engineer | Prop Trader ( 70k+ in payouts ) | Amateur fighter Bridging the gap between AI and forex trading Nothing for sale - all free content :)
Joined August 2024
- Tweets1.5K
- Following139
- Followers1.1K
- Likes1.1K





Pinned Tweet
Please don't ever stop pumping out content lol.
Literally just fed this into claude, works on all JPY pairs wtf. Haven't tested it on index yet but this is insane.
No parameter, ATR based SL.
More importantly, I'm looking for more ideas that are similar to this ( market effect, no PA etc )


To give everyone a sense of proportions - this was something that ran in the background, took about 5-6 hours for the builder I believe?
Kinda expected this result :
10,000 generated in builder ->
55 passed 2x slippage and spread ->
0 passed Out of sample testing
No better test than OOS ( aside from running live )
But learning this is giving me a greater appreciation of the different strategies/filters which are possible, just gotta make it work with some custom logic that I currently utilize


Late to the party for this one - but another avenue for strategy generation.
Basically my main takeaways from this was
1. In builder, choose whatever entries/indicators/exits you want to use ( it doesn't really matter ) - but apply a filter on stability ( pf and Sharpe in SQX don't really matter )
ii ) Also make sure to use lot sizing based on % risk ( never flat lots ! )
2. Choose a relatively short IS test period ( I'm using 3 years 2018-2021 )
3. After a few thousand strategies are generated, feed them through the retester function ( effectively, this just re-runs those top strategies from builder.
4. Retester stages were :
i ) Double the spread
ii ) Double the slippage
iii ) Out of sample testing
iv ) Parameter sensitivity ( my addition )
Only those strategies that make it to out of sample ( and it will be very few, 1% at best I imagine ) - make adjustments to it to
1. Strip away SQX boilerplate code
2. Add in your own risk management/rules as part of a wider portfolio ( e.g. for me that is going to be going flat before high risk news, single entry a day etc )
By no means am I an SQX expert, but I do love the addition of something I can run in the background to mine more strategies.

As expected, this isn't a strategy that is easily backtestable.
The reason being is that when backtesting in MT5, you can only set one swap fee that will be applied during the full backtest, which isn't accurate / how real market conditions will be.
The solutions I tried were :
1. Look for historical swaps data - this varies broker to broker, the closest I found was Oanda but they only publish a years worth of historical swaps.
oanda.com/au-en/trading/fina…
2. Calculate/infer the swap fee yourself based on their calculation method. Even then this is a bit difficult to get accurately so is questionable at best.
Might need to put this one down to bed , not interested in strategies which I can't reliably backtest with over 10 years of data.
I'm always super fascinated by trading strategies which are not price action / indicator based.
For example , the Gotobi Days strategy which has been shared previously and also this XAUUSD/GC funding rate arb which I have seen recently.
datalore.jetbrains.com/repor…
Basically it involves :
1. Enter a long / short on XAUUSD
2. Enter a short / long on GC ( same contract size )
3. Closing the positions at the before the GC rolls over, where the gain of one should offset the loss of the other.
4. Collecting profit through the positive swap on the XAUUSD.
Super fascinating strategy, I'm not sure how to even backtest this one given how hard it is ( atleast for me ) to find reliable swap data.
I did discover this before I was actively involved with coding agents, so I might give it another spin shortly.

People messaging me about how to get started or that its too expensive to get started with coding/AI agents.
So many free ones exist - sure it may not be the absolute best/frontier , but why would you need a porsche to get from A->B if a camry could do the job just as good.
I used 5.3 flash pretty extensively before hopping onto Codex, and it is seriously quite strong and was good enough for 90% of my usage

Trying to cook something for myself ( a strategy funnel based similar to SQX, but more agent friendly and with a faster backtesting engine ) but man is it eating my usage like insane.
I've actually not run out of Codex usage in a long while but this is taking a beast to build right now.
Probably going to give @Muse a go now, I've heard some great things from it , think I just need something that doesn't have a weekly usage limit ( 5 hours of usage is okay though )

I'm always super fascinated by trading strategies which are not price action / indicator based.
For example , the Gotobi Days strategy which has been shared previously and also this XAUUSD/GC funding rate arb which I have seen recently.
datalore.jetbrains.com/repor…
Basically it involves :
1. Enter a long / short on XAUUSD
2. Enter a short / long on GC ( same contract size )
3. Closing the positions at the before the GC rolls over, where the gain of one should offset the loss of the other.
4. Collecting profit through the positive swap on the XAUUSD.
Super fascinating strategy, I'm not sure how to even backtest this one given how hard it is ( atleast for me ) to find reliable swap data.
I did discover this before I was actively involved with coding agents, so I might give it another spin shortly.
Today's a Gotobi day for the JPY pairs.
Anyone entering into any trades?

shit looks like my at home server was down overnight. Not sure why Microsoft decided to restart it, AND THEN keep it on the set up screen?
I've made it handle restarts but not it being locked lol.
I think I incurred a few losses because of this annoyingly.

I don't believe you need programming knowledge in order to get started into algo trading, however having a slight idea of how software should be built and organised can make things much easier.
For example - I have tested hundreds of strategies ( largely found from online, on X, different trading forums etc ) and from those , have a handful which I think can "work".
Something I've been working on is actually :
1. Extracting out the individual components of each of those strategies
2. Categorising those components into sections
2. Combining these components into different strategies.
Chances are, if Strategy A and Strategy B work on their own, then some combination of their logic should work too.
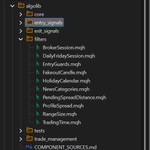
I've written about this briefly, but how I organise my algos are :
1. Entry signals
2. Exit Signals
3. Filters
Its by no means perfect or complete, but it gives me a nice opportunity to test different combinations of things I think may work.

I just wanna say be super , super careful everyone - not just email but even via the phone.
Just had someone dial my phone , they knew my details, claimed to be from a card company and said that a prop firm ( I won't list it because it's not the point ) isn't paying out so I should give them my details to "initiate" a refund.
Only reason I picked up was because I was doing a relatively large transaction and thought it was my bank calling me to confirm it.
Was the most random call, I just hope there wasn't a data breach in play 💀💀

Rise scammer trying his luck again
Not this time mf
I learnt my lesson
Be careful out there guys anyone who receives payouts via @rise_pay
They don’t ever send out such emails, any actions needed are only visible via the dashboard

this is some serious dedication man
for anyone in the future - i’d recommend you just ask grok what’s on my profile and to summarise it haha.
But really it has given me a chance to reflect, i’ve only been looking into algo trading for about a year ( a bit before my first post actually! ).
Anyone looking to get into this space can probably learn much faster than me :)

joining X was one of the highest value actions as a trader
yet another strategy - fully open sourced too guys. Those who dm me asking for ideas - follow this dude

🥇🚀 GOLD BREAKOUT 15M — NEW FREE, OPEN-SOURCE STRATEGY!
Friends, today I'm sharing a new Gold trading strategy inspired by an idea from one of my subscribers! 🙌
I took the concept, developed it, and fully implemented it in TradingView.
And the best part? I'm releasing it completely FREE! 🔥
🎯 HOW DOES IT WORK?
The strategy doesn't try to predict whether Gold will go up or down.
Instead, it waits for the market to reveal the direction of the day's move.
The logic is simple:
🌙 During the night — builds a price range.
🌅 In the morning — places orders at both boundaries of that range.
⚡ On the breakout — enters in whichever direction breaks first.
🛡️ Risk management — risks 1% of account equity per trade.
🌆 By the evening — closes all positions.
One trade per day. No overnight positions. No guessing the direction.
📈 TRADINGVIEW BACKTEST RESULTS
🥇 Gold — OANDA | 15-minute timeframe
📅 January 1, 2011 – October 12, 2026
💰 Approximately +800% total return
📊 Approximately 4,000 trades
🛡️ Approximately 14% maximum drawdown
That's almost 16 years of historical testing!
But here's the important part:
DON'T JUST TAKE MY WORD FOR IT.
Add the strategy to your TradingView chart, select the same testing period, and verify the results yourself.
All backtesting settings are provided in the strategy description.
🤖 READY FOR AUTOMATED TRADING
The strategy can work with any trading bot that accepts TradingView webhooks.
Every signal can trigger a customizable alert, and you control the message format!
✅ Ready-made JSON and plain-text templates
✅ Customize messages to match your trading bot
✅ Insert entry price, stop loss, position size, and risk parameters
✅ Separate entry and exit alerts for LONG and SHORT trades
✅ Preview alert messages before the first signal
No need to rebuild your bot or adapt your entire trading infrastructure.
📊 WHAT ELSE IS INCLUDED?
⚙️ Trade Planning Dashboard — stop loss, position size in ounces and lots, and leverage.
📈 Built-in Performance Metrics — win rate, profit factor, and mathematical expectancy directly on the chart.
🛡️ Daily Drawdown Protection — useful for prop trading accounts.
🎨 Light & Dark Themes — choose your preferred chart appearance.
🔓 100% FREE & OPEN SOURCE!
No subscriptions.
No invite-only access.
No hidden paywalls.
The source code is available for everyone to inspect, study, and test.
👉 Get the strategy here: tradingview.com/script/HnelY…
❤️ AND ONE MORE THING...
A huge thank you to everyone who shares their trading ideas, observations, and research with me!
This strategy exists because one of you suggested the original concept.
I turned that idea into a fully functional TradingView strategy — and now the entire community can use it for free.
That's how great things are built: by sharing knowledge and improving ideas together! 🤝🔥
⚠️ Backtested performance is not a guarantee of future results. Live trading conditions, slippage, spreads, and execution differences may affect actual performance.
😎 Trading together in my Telegram: t.me/WillyAlgoTrader
#TradingView #Indicator #TechnicalAnalysis #PineScript #Trading #Crypto #BTC #Stocks $BTC #forex #xau $xau #gold #vwap

Man all this talk about people building their own strategy funnel has got me feelin a bit FOMO.
Admittedly, how I gather my strategies / inspiration / trading ideas is a bit manual , but I find that it allows me to comb better through alot of the repeated BS.
Would love to give this a go in automation, recently stumbled across Strategy Quant and... it looks promising but it is not the most user friendly ( skill issue? )
Maybe I'm just too much of a boomer but even the videos are a bit difficult to follow along LOL.
If anyone has any tips, then pls enlighten me.

I wasn't going to make a post about this but since I got a one week block from @ifunds_io in their discord I figured I'd make my comment here.
I follow a few algo traders on youtube and this prop has been recommended by them numerous times.
Lets do some quick maths and see if their instant funding plans are worth it.
10k plan costs 700 usd.
Either you choose :
1. 80% profit split and get $600 of DD OR
2. 50% profit split and get a $1,000 of DD.
Now, in no universe is option 1 worth it. You have LESS DD to work with, and any profits you make, you lose 20% of it?
No wonder they can A-book you lol.
Maybe option 2 is worth it, but a 50% split is quite harsh.
You're paying $700 for an extra $300 of breathing room, but all profits are halved.
It might be worth it if you make only $100? but anything substantial ( above $500 ) you lose HALF of it.
And regarding their comment:
"""
For example with a 10K account you pay $700 and get a max drawdown of $1000. That is already $300 more
Now let us take the returns. If you put $700 in your broker and make 10% you will withdraw the whole $70. But if you buy a 10K account and make 10% you will have $1K after profit share you get $500
"""
That makes absolutely no sense.
Lemme give you guys an example.
Let me sell a $1,000,000 account with a max 1k drawdown and sell it for 1k and 50% profit split.
If you guys make 10% on that 1,000,00 account, you'd make 100k! Wait, what if I sold you a $1 billion account with 1k max DD. If you make 10% of that you'd make $100 million!
You're still bound by your max DD.
Don't ever be fooled by account size kids, always look at max DD, thats how much capacity you can actually trade with.
All I had was a simple question lol but if you guys are gonna time me out for asking questions I may as well air out the laundry here.


Busy weekend - literally no access to my laptop but still able to progress some research.
For me it’s less about the outcome and more about the process. Just the process of research is fun for me lol.
Current stack to work mobile :
moshi ( to access my vps remotely )
herdr ( manage multiple agent sessions )
codex / claude ( for trading )
I can still push out ideas even when away from my computer ( albeit not as fast - but still works )
If you think my returns are crazy then you should look at this fella here:
myfxbook.com/members/Flygpla…
$400 to 100k within 1.5 years... - using only one EA ( which you can purchase aswell supposedly?).
This isn't mine of course , but this has really opened me up to Wim's work ( even more than before ) and really understanding how he thinks and develops systems.
How it has influenced my work is thinking of systems as:
1. Filters
2. Entry conditions
3. Exit conditions
I've struggled alot with (3), but think I have developed a much more robust and safe way to manage trades. Everyone and their dog online talks about 1 and 2, but 3 is ignored quite a bit.
I wrote a bit about this earlier especially around exit conditions :
1. Trailing TP in loss
2. Early close if price is against you after N M1/M5/M15 bars.
3. Break even stops after r * ATR price has moved.
This has really helped my system development ( no its not responsible for my 1,800% month haha).

ah fuck well he aint wrong LOL I'll be the first to admit when I'm wrong in something.
I wonder how accurate the data is from Ninjatrader though - mainly the futures data. I had thought historical futures data costs money, so how can they offer it for free?


Worth being precise about what that test proves, because it's valuable but not quite cross market.
XAUUSD and GC are the same underlying. The correlation is close enough to 1 that holding on both isn't evidence the edge generalises to a different market.
What it does prove is arguably more useful day to day, the result survives a different data feed, a different session structure, different tick granularity and an entirely different cost model. Spot CFD spreads and futures commissions are nothing alike. If it holds across both, the edge isn't living inside one broker's quirks.
So I'd file it as feed and cost robustness rather than generalisation. Worth having in the validation stack either way, just measuring something narrower than it looks.