

Investor Founder : https://xitter.cf/t.co/7q4TlMW7Nl Book: 10X Stocks: How to Pick Multibaggers https://xitter.cf/t.co/hirr8nb8lz
Joined May 2018
- Tweets6.3K
- Following477
- Followers11.1K
- Likes1.6K






Pinned Tweet
🚨10X Stocks - My New Book Published worldwide on April 6th
Happy to share it’s already #1 New release and #9 Best seller in Business/Valuation on Amazon 😊
The book as the title says is about:
8 Frameworks on ‘How to Pick Multibaggers’
Order 👉 10X Stocks: How to Pick Multibaggers a.co/d/059DfXkj

🚨 GPU rental prices are RISING. Demand is real—
/COMPUTE PRICING PULSE/
Silicon Data's neocloud rental index stood at $2.82/GPU-hr for H100 vs $2.37 for H100 when the index launched in May 2025
📈 $NBIS raised the card on Oct 1 —
H100 to $4.50/hr (+17%)
H200 to $5.40 (+20%)
B200 to $8.50 (+19%)
B300 to $9.50 (+21%).
A cloud raising prices by a fifth is the purest evidence compute is scarce, not glut !
Nebius reaffirmed its $3–3.4B 2026 revenue guide — same volume, more per hour is nearly higher margin.
Hyperscalers are marking up too. AWS raised reserved capacity-block rates effective Oct 7: H100 $5.191 → $5.97 /hr (+15%), B200 to $14.208, B300 to $16.1
Cloud(neo) companies raising prices 20% into a market where its own cost of capital is double digits is not showing distress — it's showing a seller's market.
My take: The credit selloff has repriced the financing, not the core GPU/TPU Datacenters !! $NVDA $GOOG $CRWV

🚨: TPUv7 FP8 submission showing better performance / dollar is indicating an inflection point for TPU adoption curve 📈
Especially in the rapidly evolving agentic world — $META Muse, Dots, Grok, Instinct
Bullish for $AVGO $GOOGL

ALERT🚨: NVIDIA has been working overtime, nights, and weekends after being shocked 🤯 by last week’s TPUv7 FP8 submission showing better performance per dollar.
Unfortunately for NVIDIA, its first GB300 FP4 counter-submission is still 1.64x worse in performance per dollar than TPUv7 for external customers across most of the end-to-end performance curve.
The x-axis of the graph below uses end-to-end latency, so a higher curve is better. The TPUv7 curve has higher perf per $ across most of the E2EL Pareto frontier.
This initial submission looks like NVIDIA’s first attempt to close the gap, but the gap is still massive. We expect more counter-submissions from NVIDIA as they continue trying to narrow the difference.

🚨 $LITE:LUMENTUM SOLD OUT TILL 2029
I don’t know whether Memory demand is structural but I for sure can see ‘AI Optics’ is a secular trend for foreseeable future 🚀
CEO Michael Hurlston says “DEMAND GOING UP EVERY DAY!! “
Lumentum has increased core production capacity in the Tokyo area , 12X over two years and plans at least $350 million in further facility expansions 📈
Lumentum is working with Astera Labs on PCIe optical interconnects and demonstrated PCIe-over-optics connectivity with Astera and Corning at the OCP Global Summit $ALAB $GLW
$LITE is also a founding contributor to the Open Compute Project’s short-reach micro-emitter optics standardization effort.
They also announced demonstrations at ECOC 2026 of an 8-wavelength laser module and a die-to-die optical interconnect developed with Qualcomm Technologies and Corning $QCOM $LASR
🚨 Retail bought a RECORD $700M in neocloud stocks the week ending Oct 11 while $CRWV bonds priced in distress at 16% yields — Citadel
hedge funds dumped AI names at the 2nd-fastest pace in a year — per Goldman
Institution is selling the leverage. Retail is buying when momentum has broken — who is right?? $NBIS
$META Muse Wonder models made “Active Memory” the headline feature last week
‼️You won’t make money from here on, being on the wrong side of the memory trade.
Training made memory the ‘bottleneck’ but Agents use memory in a completely different way. Let’s see how ??
/ Agentic era: An agent loops: plan → act → observe → replan. Each loop re-sends the full working context. The weights are frozen, so the intelligence lives in state, and state lives in memory.
1. Meta’s Muse runs in its own cloud VM and keeps working after you close the app.
> Active Memory is Meta’s Muse Wonder feature that saves the important details from your past conversations and pulls them back into the prompt when they become relevant.
> Every recalled memory becomes extra tokens in the context window, and every token adds keys and values to the KV cache sitting in HBM for as long as the session stays live.
> Will it drive more HBM demand? Yes, but only modestly on its own, since the recalled memories are small. The real HBM driver is what memory enables: always-on agents running longer, multi-step loops with huge contexts across millions of users at once.
2. OpenAI’s Dots are always-on agents inside ChatGPT. They inherit your ChatGPT memories and keep their own private notes between conversations.
HBM will still be the toll booth. Every loop needs the weights plus the KV cache. Agents don’t run one giant batch; they hold thousands of always-on sessions, each with a big working set. $MU $SKHY Samsung hasn’t peaked yet !! $DRAM 📈

🚨 Gartner: over $3.5T of AI infrastructure spending could face impairment by 2030 — owners need $8.5T in revenue to justify the buildout, but only $3.6T is forecast.
And 80% of neoclouds won't survive independently. The math is the trade now. per Gartner
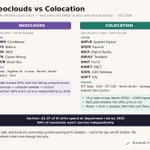
1/ My take: neoclouds are commodity cyclicals wearing tech multiples. They buy depreciating GPUs on leverage and resell compute into falling prices. Colocation like $APLD is the landlord — $36B of 15-yr take-or-pay leases, rent paid whether the GPUs print or not.
2/ Neocloud may have earnings peak in 2027 or 2028— that's one or 2 years of runway. $NBIS $IREN $CRWV $CIFR $BRUN get sold like cyclicals: at the top, not the bottom. $BRUN is already -79% from its high.
3/ See both sides of the coin: Neocloud vs Colocation. For ex:
$BRUN — Boost Run, AI-neocloud listed May 2026, now $8.89, -79% from its $42 high
And now $APLD is contrast: take-or-pay leases (1.4GW), rent paid whether the GPUs print or not.
(One flag: $APLD isn't risk-free either — debt jumped $5B→$6.3B in a single quarter per Reuters, stock -49% from its high. The long side has leverage too)
DYOR, NFA


🚨 In global AI carnage, 🇮🇳 India euphoria:
Sensex +2.11% (biggest day in 4 months), Nifty +1.66% to 22,997. Jio IPO filing lit up Reliance.
TCS +15% profit, $3.1B AI run-rate;
WIPRO Q2 revenue +9.1% to ₹24,753cr, beat estimates; shares +4% Friday to a 6-week high.
Nifty IT +1.8% led Thursday's +1,534-pt Sensex surge. AI isn't killing India's coders — it's unlocking new revenue. per BusinessLine, Reuters
🚨 Oracle is the ‘only’ real net debtor in the group at +$88B —
All other Hyperscalers are still net cash ➕
, even after the borrowing binge.
Google raised $100B in debt and still sits on $142B of net cash.
Note: Debt excludes leases; NVDA's $42.8B of equity stakes excluded from cash.
My take: AI is becoming the "who survives the capex cycle" chart. But we are far from peak of a bubble !!
There are no excesses anywhere and all-around negative sentiment at institutional level.
Today could well be the bottom before Q4 rally 📈 $NBIS $CRWV $NVDA $CRDO $LITE

🏮Cisco reported about $12.2 B in FY1999
On March 27, 2000, $CSCO briefly passed Microsoft to become the world’s most valuable public company. Its market cap peaked above $500B
The company lost about 90% of its market value, bottoming near $60 billion in late 2002.
Cisco wasn’t one of the companies whose balance sheet “couldn’t fund it.” It had plenty of cash and never came close to failing.
The companies that died were overleveraged telecom carriers and fiber builders like WorldCom, Global Crossing, and Nortel.
🎥The cast: 2000 → 2026
1. Cisco → $NVDA. Same role: the picks-and-shovels supplier and the world’s most valuable company. Valuations are nowhere close though. Cisco’s forward P/E peaked somewhere around 136x. Nvidia recently hit a record $5.75 trillion market cap with its forward P/E down to about 17x
2. The real risk at Nvidia is the one Lucent and Nortel taught us: vendor financing. When the supplier funds its own customers, revenue becomes credit risk.
Nvidia now guarantees financing for some GPU buyers. Watch this line, it exposes it to credit risk if customers like CoreWeave struggle with interest costs. $CRWV
3. WorldCom / Global Crossing → $ORCL. Oracle spent $55.7 billion on data centers and AI, ran negative free cash flow of $23.7 billion and issued $43 billion of debt in a year, taking total debt to about $156 billion.
4. The ‘fiber builders’ of this cycle are $CRWV, $NBIS, $IREN and other neoclouds: $35B + of debt, bonds yielding in the low teens, and customers who are also their competitors.
In 2001, this is the layer that went to zero.
5. AT&T-style incumbents → Microsoft, Alphabet, Amazon, $META.
They’re still self-funded, but the margin for error is shrinking.
Capex has gone from 41% of their operating cash flow in 2023 to a projected 92% in 2026.
🎯Scorecard: equity valuations are far from 2000 levels. Leverage at the edges is already there. The core is drifting toward it.

🚨Anthropic just did $16.8B in revenue in Q3 🤯
📈That’s up 46% from $11.5B in Q2, so +$5.3B in ONE quarter
And : adjusted profitable AND cash-flow positive
/ Why this matters for AI credit fears:
The worry in credit markets has been simple. Hyperscalers and neoclouds are borrowing heavily to build data centers, betting AI labs can pay for that compute. If the labs burn cash forever, that debt looks shaky and CDS spreads widen.
/ A major AI lab generating cash weakens that bear case slightly. The customers on the other side of those multi-billion-dollar compute contracts are starting to look like real, self-funding businesses $CRWV $NVDA

Man should have invested instead of analysis paralysis ! $BSP @JonahLupton

I was analyzing it too.. they $4 B debt on books which made me apprehensive. But it’s a great business model
❤️🔥Has the AI Bubble Burst ??
Read: The Sancompounding Special Report — AI Carnage :
investaicapital.substack.com…

🚨 $ASML +3% after print: €11.66B (+55% YoY), GM 57.5% beat, Q4 guide €14.2–15.2B
CEO says even the 30% capacity hike won't meet demand, with order interest to 2030.
Samsung and TSMC, the world's two biggest chipmakers are major clients !! China accounts 20% of the sales still 🇨🇳
Meanwhile memory stocks keeps bleeding ( $MU/ $SNDK premarket) on CXMT fears.
❓Demand isn't the problem in AI buildout as Elon says . Supply Execution and low Cost of capital are the key !!

🚨 Anduril announced Arsenal-2 — A massive $6.6 billion, 2-million-square-foot software-defined mega-shipyard being built by Anduril Industries in partnership with the US Navy.
The project includes a $3.7 billion private investment from Anduril and a Navy contract worth up to $2.9 billion
Extremely bullish for Kraken robotics $KRKNF
Anduril Industries partners with Kraken Robotics and Kraken Technology Group to supply subsea hardware, autonomous systems, and small unmanned surface vehicles (USVs) for defense programs

$BABA OWNS 5% OF CXMT
1. $CXMT Market cap is $510 billion and 5% of that is $25 billion
2. $BABA holds a 36% stake in Moonshot AI, the Chinese artificial intelligence startup that released Kimi K3 model. Moonshot ai is valuation hit $50 billion as it prepares for IPO.
A 50% premium listing can take $BABA 36% stake valued at $27 billion
3. $BABA holds 33% of ANT financials. Based on these current valuation metrics (such as a ~$132.5 B to $200 B company valuation), Alibaba's 33% stake is estimated to be worth roughly $44 billion to over $60 billion. Let’s take it as $50 Billion
Just 3 stakes of Alibaba Adds up to $100 billion ie 36% of $BABA Market cap.
Alibaba also hold stakes in other Ai companies like Zhipu Ai, Kling and a few more that can add up to $10 billion
$BABA Market cap is $275 billion with $50 billion cash on hand.
So that means $BABA is trading at a market cap of $137 billion (50% lower market cap) if you remove cash and investments
At $137 billion, you are getting
1. Worlds largest e-commerce platforms
2. Words fastest AI model (Qwen)
3. Qwen Agentic ai App
4. T-Head (Proprietary Chips): Alibaba's in-house chip design semiconductor division
5. Alibaba Hyperscaler cloud
A much smaller e-commerce company like $SHOP is valued at similar levels of $130 billion !!

🚨Steve Cohen’s biggest stock is no longer $NVDA
It’s $CRDO !! Why Cohen’s book flipped:
Point72 cut $NVDA 94%. Credo took the #1 spot at $1.67B
And for the right reasons Here’s why 👇
Every AI data center has the same ‘hidden’ problem:
> GPUs are fast. Moving data between them is slow, hot, and fragile
> 100K-GPU cluster is worthless if the chips can’t talk to each other. Credo does the job
And it’s one of only three companies that connects data at every distance:
🟣 COPPER (inside the rack)
Active Electrical Cables, the famous purple cables. Copper with a Credo chip inside that cleans the signal. Cheaper, cooler and more reliable than optics over short runs.
🔵 OPTICS (rack to rack, row to row)
Optical DSPs, ZeroFlap optical modules and silicon photonics, boosted by the DustPhotonics acquisition.
⚪ CHIP-TO-CHIP (inside the server)
SerDes IP plus PCIe and Ethernet retimers that keep signals clean as speeds jump from 800G to 1.6T
The numbers:
• FY26 revenue: $1.3B (+206% YoY)
• Q1 FY27: $479M (+115% YoY)
• Non-GAAP gross margin: 68%
• Q2 guide: $525–535M
• Optical revenue target: >$600M this fiscal year, with 3 optical product lines each >> $100M

🚨 $LITE is exactly why you don't chase parabolas.
All-time high $1,143 Friday on "sold out through 2029" optical demand (per Bloomberg).
Monday: -11% in heavy volume 🔻
IBD sell signal, worst on the Nasdaq.
The demand thesis still intact !!
🚀 Why the AI Memory Supercycle is the trade of 2026 ??
6 stocks powering the $DRAM ETF:
HBM sold out through 2028. NAND sold out through 2026. HDD sold out through 2027 !
1. $MU (Micron):
Core product: HBM3E, HBM4, DDR5, eSSDs
Thesis:
→ entire CY2026 HBM capacity SOLD OUT — > pricing locked
→ Q2 FY26 revenue of $23.86B, up 196% YoY, 75% sequentially
→ 20% global HBM market share. first 5-yr HBM supply agreement signed
2. Samsung Electronics 20%
Core product: HBM3E, HBM4, DDR5, NAND, custom HBM base die
@Samsung is the dark horse — finally cleared Nvidia HBM4 qualification
→ Won long-awaited Nvidia HBM4 validation; Q4 operating profit guided to record $14B
→ Counterpoint sees Samsung at 28% HBM4 share in 2026, behind only SK Hynix
→ Morgan Stanley says memory profits to grow 310% in 2026
3. SK Hynix : 24%
Core product: HBM3E (12-Hi), HBM4, eSSDs
SK Hynix is the undisputed AI Memory leader
→ Secured >70% of Nvidia’s initial HBM4 orders for the Vera Rubin platform
→ HBM commitments from hyperscalers exceed 3 years of forward supply
→ 62% HBM shipment share Q2 2025
→ Goldman sees >50% share sustained through 2026
→ Nvidia accounts for 90% of SK Hynix’s HBM supply
4. $WDC (Storage HDD: Western Digital 5%)
Core product: 32TB / 40TB HDDs
$WDC just printed a record quarter — gross margins broke 50%
→ Q3 FY26 revenue $3.3B (+45% YoY), EPS $2.72 (+97% YoY)
→ Cloud = 89% of revenue at $3.0B (+48% YoY)
→ Entire 2026 production capacity sold out to top 7 hyperscalers; LTAs extending into 2027-2028
→ 52% nearline capacity share with 40TB UltraSMR drives
5. $STX (Seagate Technology Holdings) 6%
Core product: Mozaic 3+/4+ HAMR drives (30TB → 44TB)
$STX nearline capacity sold out through CALENDAR 2027
→ Mozaic 4 delivers up to 44TB per drive — 30%+ more capacity vs Mozaic 3+ with same BOM
→ Nearline capacity almost fully allocated through CY2027 under build-to-order contracts with locked configuration AND pricing
→ Selling all exabytes produced; 25% exabyte CAGR over next 3-4 years 📈
6. $SNDK (SanDisk) 6%
Core product: HBF, Enterprise SSDs, 256TB drives, BiCS NAND (Kioxia JV)
$SNDK is the pure-play NAND beneficiary post-WDC spinoff. But entering HBF space
→ Q1 2026 enterprise SSD contract prices rose 33-38% QoQ; AI servers >45% of NAND shipments
→ Data center revenue +64% QoQ
→ Launched industry’s first 256TB Enterprise SSD for AI Data Lakes.
- data center now 55% of total sales .

🚨 $META JUS LANUCHED MUSE WONDER - ENTERED FRONTIER AI RACE
Muse Wonder ($META) claims parity with Claude & GPT on coding, finance and legal work, priced right in Claude Opus territory.
Why it could pressure OpenAI/ Anthropic:
→ Distribution: 3B+ users across Meta apps
→ Matching price, so it competes head-on for developer spend
→ Muse agent app gives it a consumer funnel
Looks like Anthropic and OpenAI will have to fight the enterprise ‘TAM’ since $META has taken out ever consumer AI space !!