

Stocks, options, market and economic research | Sharing portfolio updates regularly | Not Financial Advice
Ontario, Canada
Joined May 2026
- Tweets216
- Following196
- Followers81
- Likes809


Pinned Tweet
Here are my updated portfolios positions. Will be updating them regularly as best as I can. Most put sales are cash secured.
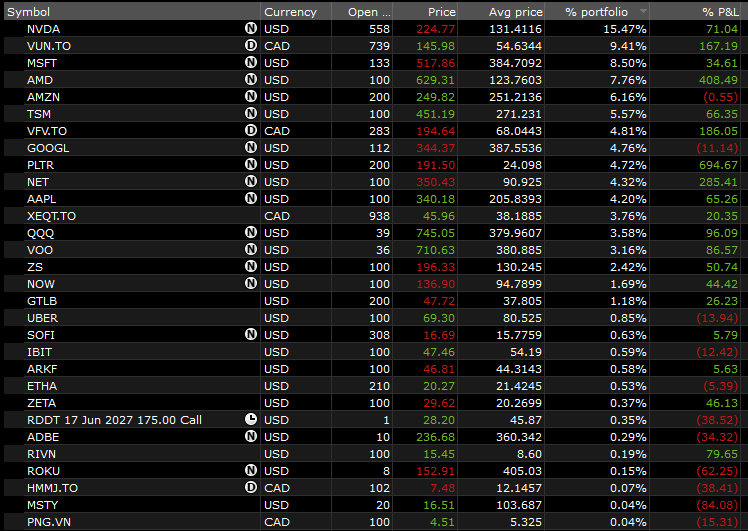
ALT Long Term

ALT Options


MS: Spending by largest cloud companies. Cloud capex reaches US 1.6 T by 2028e, but growth slows from 97% to 12%.


SPCapital retweeted

The S&P 500 is now in bear-market territory..
..the valuation, that is. P/E has contracted from 23.2x a year ago to 18.7x today.. .that's just about a 20% de-rating @dualityresearch
Multiple is the cheapest since Liberation Day April 2025

SPCapital retweeted
Tech's P/E is the cheapest since 2022 @dualityresearch
Now well below the March 2026 and April 2025 lows...


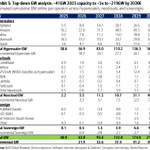
BofA: Our operator-by-operator analysis suggests global Al/cloud data center capacity could increase from ~41GW in CY25 to ~219GW by CY30E, with annual additions accelerating from ~22GW in CY26E to ~45GW by CY30E. Hyperscalers remain the largest contributors, while neocloud and sovereign deployments become increasingly material over time.


JPM: AI capex increasingly relies on external funding and funding requirements are expanding - US 5.5 T of AI capex over 2026-2030. Can AI generate sufficient economic returns to sustain the investment cycle?

The age of easy money is fading, and investors aren’t ready for what’s next
theglobeandmail.com/investin…

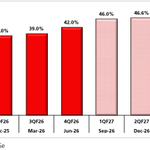
JPM: The AI compute mix continues to evolve toward heterogeneity, with custom XPUs gaining share of the accelerator TAM (XPUs rising from ~32% of units in CY25 to ~42% in CY26E and ~53% in CY27E) as hyperscalers scale TCO-advantaged internal programs. AVGO and MRVL remain the best-positioned custom silicon beneficiaries, with AVGO continuing to add XPU customers and lengthen multi-year XPU commitments across its hyperscaler base, while MRVL's custom ASIC and optical franchises continue to scale on strong design win momentum. On the merchant GPU side, NVDA continues to execute on the Vera Rubin ramp with POs secured from every major hyperscaler/AI cloud/system OEM, while AMD continues to execute on the MI4xx roadmap and Helios platform ramp.

JPM on AI/accelerated compute: Infrastructure demand continues to outstrip supply, with consensus cloud (hyperscaler + neocloud) capex for Y26/CY27/CY28 now at $950B/$1.42T/$1.55T (+97%/+47%/+9% Y/Y) and visibility continuing to push further into the decade on the strength of multi-year hyperscaler commitments and backlog build. The sustainability debate has shifted from whether AI demand is real to whether supply can keep pace. Even as hyperscalers continue to add capacity, both industry and company checks continue to indicate that near-term supply is insufficient to meet demand across GPUs, ASICs, HBM, and advanced packaging, with GPU rental pricing dynamics and lengthening order books at NVDA, AVGO, and MRVL all pointing to the same conclusion. We expect commentary from the leading compute providers to continue to point to upside to CY27 (and beyond) order visibility, with sovereign AI, AI-native cloud, and enterprise demand continuing to broaden the demand base.
