

We inspire, empower & educate a global community of quants, providing world-class infrastructure for them to design and trade investment strategies.
Miami, FL
Joined July 2011
- Tweets2.4K
- Following432
- Followers13.9K
- Likes1.5K




Pinned Tweet
🚀 Live US Equity + Index Options data is now available on QuantConnect.
We’re tracking 2.1M option contracts, delivering 90% of bars within 250ms, with data down to 1-second resolution.
Included free with any QuantConnect live trading server.
quantconnect.com/announcemen…


Today our CEO @JaredBroad will be at the Cornell Financial Engineeering Future of Finance conference in Manhattan - if you around say hello!
QuantConnect retweeted

This is one of the most underrated tools right now.
LEAN by QuantConnect is an open-source algorithmic trading engine, write your strategies in Python or C#, backtest at scale, with an event-driven architecture built for serious quant work.
If you're building trading systems, you need to see this and read the article below.


You can deploy your live trading options strategy to any of our supported US Equity/Index Option brokerages: @IBKR , @AlpacaHQ, @TradeStation, @tastytrade, @WebullGlobal, @tradier, @CharlesSchwab, and @public -- along with any prime brokerage through our FIX networks.
Bitcoin is booming again - up roughly 20% this week and back above $76K. Can it be useful to equity investors even if they never intend to hold it directly?
Our latest QuantConnect research examines whether Bitcoin can serve as a real-time indicator of market risk appetite. The strategy uses Bitcoin’s trend and momentum to determine when to hold QQQ and when to rotate into SHY.
When Bitcoin is above its 50-day moving average and has positive 20-day momentum, the strategy holds QQQ. When those conditions are not met, it moves into SHY.
The hypothesis is that Bitcoin’s continuous trading and highly responsive market structure may allow changes in global risk appetite to appear there before they are fully reflected in growth equities.
That relationship is particularly interesting during the current strength in Bitcoin prices. If Bitcoin is capturing a broader shift toward risk-taking, its price behavior may provide useful information for systematic equity allocation.
From 2014 to 2026, the strategy produced a Sharpe ratio of 0.838, beating 0.682 for buy-and-hold QQQ and 0.564 for SPY.
Read the full research, methodology, and implementation on QuantConnect:
bit.ly/4g6mjkY

What if momentum works better in stocks that don't pay dividends?
We tested the idea.
Buy the strongest-momentum stocks among liquid US companies that pay no dividends, then rebalance monthly.
With a 10-year backtest: 📈 Sharpe: 0.602, beating the benchmarks with almost all parameter combinations 💪. A surprisingly simple behavioral-finance signal.
Check it out on @QuantConnect!
quantconnect.com/research/21…

What if the VIX could tell you when to short volatility... and when to get out? 👀
This dual-signal strategy uses VIX + VIX3M to switch between short and long VIXY exposure.
Result: 0.729 Sharpe vs 0.582 for SPY.
Full research 👉 qnt.co/4wLPP5g

Can algorithmic execution reveal a return signal?
This strategy ranks liquid US equities by intraday volume periodicity, then weights them by confirmed execution flow.
Sharpe: 0.792 vs. 0.406 for SPY. All 25 parameter tests beat the benchmark.
quantconnect.com/research/21…

New Friday Research Drop!🎉 🔬 💹 Read: bit.ly/4wO2SCW
In this study, we build a long-short momentum strategy with conditional short legs to improve the performance and reliability.
The objective is to preserve the strength of long-only portfolio momentum, without continually paying for short assets that may rebound.
Using asset correlations, we can exclude any hard-coded regime parameters, indicating true divergence among the short candidates.
From July 2007 through June 2026, the conditional hedge increased the strategy’s Sharpe ratio from 0.451 to 0.498, compared with 0.407 for SPY. The result was also relatively stable: 24 of the 25 correlation-window combinations tested outperformed the benchmark’s Sharpe ratio.

Public is now supported on QuantConnect 🎉
Deploy live algorithms across US Equities, Equity Options, Index Options, and Crypto.
Public joins 20+ brokerage connections on a platform that processed over $100B in trading volume in May.
See more: qnt.co/public-brokerage-anno…

Can changes in filing language predict returns?
The team @ Triton Quantitative Trading tested a strategy that selects liquid US stocks with the most stable filing language.
The result was a modest improvement in risk-adjusted returns for those companies that make _fewer_ changes to their filings.
Check out the research & source code here: bit.ly/4gwEbGd

QuantConnect retweeted
New Friday Research Drop!🧪🔬🎉
Community member, Zhaoren Deng, explored a classic options concept applied dynamically to the Magnificent 7 - conversion arbitrage.
Conversion combines a long stock position, a long put, and a short call at the same strike and expiry. In theory, the package behaves like a fixed-payoff instrument, with returns driven by deviations from put-call parity.
Full post - quantconnect.com/research/20…
New Friday research drop from the QuantConnect team!🎉🧪🔬
This week, we explored the MAX Effect: how a simple empirical observation can be translated into a practical, systematic strategy.
Check it out: lnkd.in/eQwPxQuW
Building on earlier work, this QuantConnect study explores using VIX-based leverage scaling to adjust market exposure across volatility regimes.
The research shows that stocks with extreme positive daily returns can behave differently in subsequent periods, creating a measurable anomaly in expected returns.
We extend that intuition into a dynamic portfolio approach: instead of treating leverage as fixed, exposure adapts to changing market stress. The result is a clean example of how volatility signals can support risk management and portfolio construction.
This strategy was also almost entirely implemented by our new agentic Research Pipeline. We fed the research paper into the AI, which expanded the idea, backtested it, tested parameter sensitivity, and helped draft the first version of the research post ✨
Credit to the Triton Quantitative Trading team at @UCSanDiego for their latest QuantConnect research: a volatility-targeted QQQ–TLT rotation using a multi-scale CNN-LSTM model to forecast turbulence and adjust exposure.
quantconnect.com/research/20…

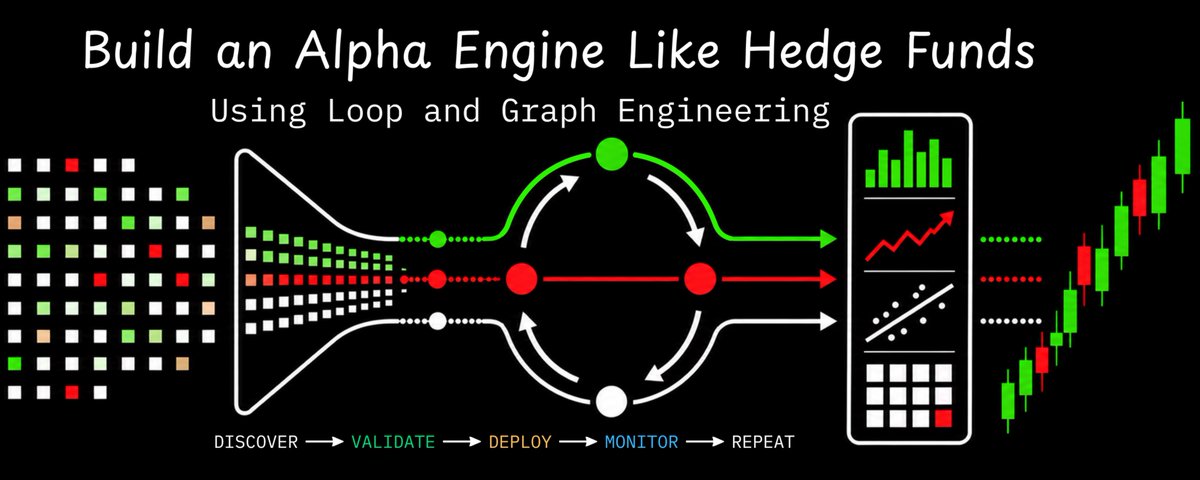
Systematic research is becoming fully agentic.
Today we launched QuantConnect Assistants, an @openclaw like framework for quant.
Specialized AI agents can research ideas, run notebooks, analyze backtests, read logs, and coordinate through a visible Research Pipeline:
Ideas → Research → Validation → Backtesting → Live Monitoring
You can build your own agents, and automate your specific research processes. Read more:
quantconnect.com/announcemen…
QuantConnect retweeted

The team at @QuantConnect recently created an integration that brings Databento's real-time and historical market data directly into LEAN, their open-source algorithmic trading engine. For the hundreds of thousands of developers already building with LEAN, adding a Databento API key provides our normalized market data across research, backtesting, and live trading - all within their existing setup.
⬇️ To get started, check out the guide below

Final count down to the Quaint Quant Conference in Dallas this Friday! Our founder @JaredBroad is speaking on Applied AI for Quant Finance ✨ - come say hello!
quaintquantconference.com/ag…
QuantConnect retweeted

Classical ML + Deep Learning CNNs + Amazon Chronos Foundation Models + @QuantConnect = Can AI actually generate alpha? 📈🤖
Huge thanks to the 50+ of you who packed the room at the PyHou Meetup! Your energy was unreal. 🙏
As promised, I’ve refined the entire presentation into a massive open-source masterclass. Here is the complete teardown 👇 (1/4)