

OpenLP aggregates & amplifies insights across the venture ecosystem to demystify the LP perspective. Powered by LGT Capital Partners
Joined March 2016
- Tweets1.5K
- Following2.4K
- Followers5.2K
- Likes1.1K




3/ Episode highlights:
🔹 Miles’ unconventional path to venture: from Penn State football to a stint with the Pittsburgh Steelers and now CMU’s investment office
🔹 How CMU underwrites funds to a 4x net return target, with public markets setting the hurdle
🔹 What great pickers look for in founders: missionaries vs. mercenaries, plus why GP commitment is Miles’ “cleanest piece of science” on alignment
🔹 Why bigger future exits don’t necessarily justify a $50M seed round
2/ Miles helps oversee CMU’s $4B endowment, with a venture allocation notably larger than many peer institutions.
Conviction = VC's potential for extraordinary outlier returns - in his words, the fat right tail optionality exposure that no other asset class can deliver.
Caution = which mgrs can actually produce those returns, the LPs that can access them & whether today’s megafund math leaves enough room for those outcomes.

1/ Why would an LP who believes 90% of LPs shouldn’t be in venture allocate nearly 1/4 of a university’s endowment to it?
For @CarnegieMellon's Miles Dieffenbach (@Curiousjorge65), the conviction and the caution go hand in hand.
🆕 Origins: Breaking down megafund math👇
"Don't let someone else's outlier change your definition of progress... The goal isn't to win the headlines today. Its to still be building when the cycle turns."
@hpierrejacques on venture’s confidence gap as (anticipated) extreme outcomes at the top distort what "good" looks like everywhere else👇


There is a confidence gap happening in venture capital right now.
On one side, you have new portfolio companies growing at a pace we have never seen before. Companies are going from $0 to millions in revenue seemingly overnight, and the biggest AI companies are creating value at a scale that can make almost everything else feel small.
I saw a chart recently showing that Anthropic, OpenAI and SpaceX alone could potentially generate more returns than decades of tech IPOs. Whether the exact numbers play out or not, it puts the scale of today's biggest winners into perspective.
On the other side, many investors still have significant value tied up in companies from the previous cycle. Some of those companies are still growing 2–5x year over year, but they're struggling to raise capital, founders and employees are tired, and the path to the next round or exit isn't always clear. Eventually, the new companies may grow enough to outweigh the old portfolio, but we're in this weird period where both realities exist at the same time.
That's creating a confidence problem for both investors and founders. You can have a company growing 5x and still feel behind. You can go from $0 to $3M to $10M and wonder why you're not moving fast enough because every week you're reading about another company going from $100M to $1B. As an investor, you can have a portfolio that is objectively performing well and still question whether it matters if you don't own one of the 3, 5 or 10 companies that ultimately define this generation.
The extreme outcomes at the top are distorting our perception of what good looks like everywhere else. I don't think that means the other companies don't matter. There will be generational companies worth $10B or $25B that never become trillion-dollar companies. There will also be great funds that don't own one of the three biggest winners of this cycle.
AI is here to stay, but I don't believe today's growth rates and valuation increases will continue forever. At some point th market will reset, like every cycle eventually does. The hardest thing right now is staying focused when everyone around you is talking about the outliers.
For both founders and investors, the answer is the same: don't let someone else's outlier change your definition of progress. Keep building, keep investing and keep surviving. The goal isn't to win the headlines today. Its to still be building when the cycle turns. Thats where the next generation of great companies will come from.
Megafund capital concentration, power law consensus & AI continue to squeeze seed managers. So what’s the path fwd for early-stage investors? 🌱
@robgo says there are 3:
💎 Fight for diamonds in plain sight
🥈 Mine for silver
🕵️♀️ Search for diamonds in the rough
Each comes w tradeoffs, but only 1 leads on private markups👇

It's been about a year since I wrote my post about the Existential Crisis for Seed VC's.
Some updated thoughts here on the three paths forward for seed investors.
nextview.vc/blog/the-three-p…

OpenLP retweeted

Another outstanding piece of analysis from @credistick 👇
If an LP wants to build a diversified venture portfolio, part of the job is then finding managers who bring a range of opportunities. In today’s concentrated market that can be tricky, as you can invest in five different funds and still end up with a lot of the same bets. Which is great if they all work out. Less great if they don’t.
Dan puts some data behind this. Across 5 megafunds’ seed portfolios, he saw an avg of ~87% of labelled investments were in AI. EMs covered more ground… Still a focus on AI (avg of 55% in one example), but more than twice as likely to back a wider ranges of businesses.
There's so much talk about how tough it is for EMs right now (and it is), and this data illustrates the important role they play inthe ecosystem. They’re willing to put the time (and 💸💸) into ideas that aren’t yet obvious to the rest of the market.

The average emerging manager backs more than twice as many outlier profiles than a megafund, per investment.
Pooling 5 EM portfolios increases the range of investments significantly, while the same is not true for the more homogenous megafunds.
At the earliest stages, venture capital is built on discovery; innovation relies on an appetite for companies outside of "legible" categories.
Megafunds' revealed preference is to dominate existing categories, rather than drive discovery. So, the market will continue to rely on small and emerging managers for discovery.
Thanks to @dealroomco for letting me loose on their data to test this hypothesis.
Full report available here:
research.joinodin.com/#/pape…

She's home! Welcome back to the Bay @Beezer232!
🌉 🌉 🌉


3/ Well-done research by Aaron Dubin (@team8group) on what it takes to build an enduring venture firm & how LPs can identify promising mgrs before they’re widely recognized.
Download the full report here: team8.vc/report/the-emerging…


1/ What do investors who make the @Forbes Midas List YoY have in common?
70% were founders/operators before VC.
New report by @team8group analyzes Midas + performance data to ask:
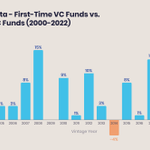
Why do Fund Is attract so little institutional capital despite historically strong returns?

5/ Plus: Why @SPintoPeyronel says people have it backwards about retail investors being “fickle,” and why more women should start investing earlier.
Latest Origins episode on YouTube now:
youtube.com/watch?v=E2h2Suxb…
4/ Robinhood Ventures’ pitch to VC-backed founders:
🤌 Direct cap table access
🤌 No layered SPVs or stacked fees
🤌 The opportunity to engage retail investors before an IPO
Sarah also shares what it’s like to manage a venture portfolio with a stock price marked every day.
3/ Robinhood Ventures is taking two distinct approaches to VC:
RVI: A concentrated late-stage portfolio featuring companies including @Databricks, @OpenAI and @Stripe.
RVII: A $200M early-stage fund built entirely around @ycombinator companies.
2/ Before @RobinhoodApp, Sarah spent 8 years building the venture program at @EmCollective, backing @OpenAI, @AnthropicAI and @coinbase before they became household names.
Today, she leads Robinhood Ventures and serves as president of Robinhood Ventures Fund II.

1/ Private companies are creating enormous wealth, but only ~1% of Americans have any exposure to them.
@SPintoPeyronel is working to change that.
🆕 Origins: Sarah joins @Beezer232 to share how Robinhood Ventures is bringing venture capital to the 99%
Link below👇
Almost 90% of global private capital raised in H1 2026 went to established managers. This spans all private markets, but it matters for VC.
Emerging managers face an uphill climb. But those that build with discipline and differentiation could become the next enduring franchise.


1/ Global VC fundraising dollars fell 4.2% YoY while the # of funds closed dropped ~1/3.
The gap suggests fewer managers are capturing a larger share of capital.
Broader private-market data points to liquidity pressures reshaping LP allocations.
3 charts from @PitchBook 🧵

3/ A not-to-miss LP episode on what every GP needs to hear: headline multiples aren’t enough.
Time, liquidity, position sizing & the ability to meaningfully impact the portfolio all shape how endowments allocate.
youtube.com/watch?v=U_ManIWI…
