

DeFi Researcher || Project Advisor || Content writer 🦅
Jupiter
Joined August 2009
- Tweets119K
- Following8.5K
- Followers21.9K
- Likes20






Maya 💙💛 retweeted

gold ethereum:0x68749665ff8d2d112fa859aa293f07a622782f38 traded $103.6m on ondo perps yesterday some huge numbers but,
I was more interested in something else, something an everyday trader would always consider.
the difference between the buy price and the sell price.
that gap is called the spread, and smaller it is the better for you.
Why should I care about the spread you ask?.
You see apps like this need market makers. these are traders who always keep buy and sell orders on the order book , so you can trade any time.
the more money they can use, the bigger their orders and the smaller the spread.
on apps that only take stablecoins as margin, which is the money you lock up to open a trade, market makers have to split their money.
part sits on the app as margin. the rest sits somewhere else to protect their trades.
ondo perps lets them use tokenized stocks as margin too.
so the stock they hold to protect a trade can also count as margin. one pile of cash either stables or stocks does the job perfectly.
that leaves more money to keep prices tight.
why should you care?
when you buy or sell instantly, you pay the spread on top of the fee, going in and coming out.
a smaller spread means less of your money lost on every trade.
what do you check first on a new app, the fees or the spread?
@OndoPerps spread is just under 0.01% .
so for every 100 dollars trade you only loose 0.05 dollar’s on opening and closing the trade,
You can begin your Ondo perps journey today here,
app.ondoperps.xyz/?ref=74MC9…
Based.

Maya 💙💛 retweeted

DeFi lending vault deposits have grown from ~$4B at the start of 2025 to more than $10B by October 2026.
That’s 2.5x growth in roughly 21 months.
But the bigger story isn’t the capital entering these products. It’s the lending risk depositors are outsourcing in exchange for yield.
Crypto lending vaults typically offer 3–10% returns, while riskier strategies can exceed 20%.
That spread deserves scrutiny.
Here’s where I think the risk becomes more interesting.
» Curators are becoming the risk managers
Take @Morpho.
Its Vault V2 separates strategy from execution. Curators determine which markets and adapters are permitted and establish risk parameters. Allocators deploy capital within those rules.
That creates a layer between the depositor and the underlying lending markets.
But there’s an important technical detail: Morpho’s documentation says allocation caps aren’t continuously enforced ceilings. Exposure can move above a cap without a new allocation.
A risk limit is useful, but it isn’t a guarantee that exposure can never exceed it.
» APY doesn’t tell you how quickly you can exit
Vault deposits are deployed into lending markets to generate returns.
When borrowers use most of the available liquidity, the vault may not have enough assets immediately available to satisfy every withdrawal.
Morpho explicitly distinguishes this situation from bad debt. A withdrawal delay doesn’t necessarily mean funds are lost.
But it does mean that advertised yield and immediately available liquidity are two different metrics.
» The real stress test is a collateral failure
Suppose a borrower owes $10M against collateral initially worth $12M.
If that collateral falls to $8M before liquidation can recover the debt, the position may leave the lending market with a shortfall.
In Morpho Vault V2, bad debt reduces the value of the vault’s assets, and the loss is shared proportionally among depositors.
The smart contracts can enforce the rules correctly and depositors can still lose money.
That’s the distinction between protocol security and credit risk.
» Look beyond the headline yield
A useful comparison: Two Prime’s Bitcoin lending vault on Pareto launched with a target yield of 1.5 – 2% and roughly $10M of the firm’s capital committed to absorb initial losses.
That doesn’t make it risk-free, and the strategy isn’t directly comparable to every DeFi vault.
But it illustrates the questions I want answered:
→ How much collateral and market concentration sits behind the yield?
→ What proportion of deposits is immediately liquid?
→ Who can change the allocation, and what protections apply?
→ Is any manager capital committed to absorbing losses before depositors?
→ What happens to the vault’s share value when bad debt is recognized?
DeFi vaults are making sophisticated lending strategies accessible to more capital.
My take: growth in deposits shouldn’t be mistaken for better risk management.
As more capital flows through curated strategies, the quality of the curator becomes just as important as the underlying protocol.
I’d rather use a vault with transparent exposures, realistic withdrawal assumptions and clearly defined loss protections than chase an extra few percentage points of APY.
In the long run, I think the vaults that earn lasting trust will be the ones that make their risks as visible as their returns.

Maya 💙💛 retweeted

Liquidity gets institutions to look. Confidentiality decides whether they stay.
Most blockchain narratives stop at capital and distribution. Institutions don’t.
They need to move real money, run strategies, and settle with counterparties without broadcasting every position, size, and timing to the entire market.
If the only option is full public exposure, many will keep that activity offchain.
What institutions actually require:
• Private position sizes and strategies that don’t leak to competitors
• Verifiable claims about reserves, collateral, and activity without revealing the underlying details
• Infrastructure that sits above existing rails instead of forcing a full migration to a new chain
Primus is building that confidentiality + verification layer. It works on top of current onchain financial systems, including BNB, so institutions don’t have to choose between privacy and the ecosystems where liquidity already lives.
The real question isn’t just how much capital a chain can attract.
It’s whether the infrastructure lets that capital actually support institutional finance.
Explore Primus XP → s.kaito.ai/m0kfaLC
What other infrastructure does BNB still need for serious institutional finance?

Maya 💙💛 retweeted

Here is something that most people do not think about.
Every platform you use right now is building a detailed profile of who you are. Your posts, your streams, your purchases, your onchain activity, your gaming history. All of it is being captured.
None of it belongs to you.
Your identity online is fragmented across dozens of platforms and none of those signals connect, none of them compound, and none of them reflect back to you in any meaningful way. Platforms capture everything. Users earn nothing.
CONSO is building the infrastructure to fix that.
The Consumer Reputation Layer converts every action you take across social, gaming, AI tools, creative platforms, and onchain environments into portable reputation credentials that you actually own. Not points in someone else's database. Verifiable credentials that travel with you.
Your CONSO Passport holds all of it together. Including Agentic Memory, meaning your AI context carries across experiences rather than resetting every time you switch apps.
CONSO BOTS are where you stake your place in this network early.
Each BOT is a Reputation-Backed Mobile Node. Connected to the CONSO Miner App, it lets you mine ZAPs, validate network activity, help identify bad actors, and earn a 25% mining boost over the base rate. Built on SUI and secured through Walrus. But more importantly, your BOT carries your relationship with CONSO across every product they build going forward. Social. Gaming. AI. Brands. Wallets. Onchain environments.
The Consumer Graph CONSO is building connects users, creators, gamers, brands, applications, and AI agents through verifiable reputation. Your BOT is your node in that graph.
Genesis Mint is not open to everyone. You either pass the eligibility check or earn access through impressions. The first generation of nodes matters because they are laying the foundation for everything built on top.
The internet has been extracting value from your attention for decades. @conso_xyz is building the layer where that finally runs in the other direction.
Your attention creates value. Your reputation powers the network.
🤝 Paid partnership

Maya 💙💛 retweeted

Good morning ☀️
this is the part that actually matters if you want to earn from @vangrid_io
buyers post bounties for specific real places they need captured, you can browse them at data.vangrid.io
find one near you, open the vangrid app, and just walk through that spot while recording, takes about 30 to 60 seconds
submit it, it goes through a quality check, and once accepted you get paid in usdc
no interview, no application, just whoever's nearby and willing to go
anyone here already completed a bounty, how was the experience
Maya 💙💛 retweeted

the interesting part about xdce-crowd-sale:native and ethereum:0xe28b3b32b6c345a34ff64674606124dd5aceca30 today is that both stories connect crypto to existing financial systems
@MoneyGram joining @XDCNetwork as an institutional validator brings payments and settlement into focus
meanwhile, @injective's move with @BDACSKorea to use KRW1 as a won settlement asset for tokenized assets shows how local currencies could find a place onchain
but there's a difference between a strong project headline and actual token demand
the real question is whether these integrations create recurring activity that eventually flows back to the token
that's what i'd watch beyond the announcement itself

Maya 💙💛 retweeted

The first thing I built on GenLayer wasn't something I could have explained with a normal blockchain transaction.
ECOVERDICT was an attempt to answer a surprisingly difficult question: when a company makes an environmental claim, what evidence would actually make that claim acceptable?
That experience changed how I listened to Genesis Episode 5.
Albert talks about the difference between building an app and building a protocol. I understand that distinction much better now.
An app gives you a predefined problem to solve. A protocol gives builders room to discover problems the original team never anticipated.
I wasn't trying to create another token or trading interface. I wanted independent validators to examine claims against evidence and reach a judgment.
Someone else might build a prediction market. Another developer might build a dispute system for AI agents.
Those are very different applications, but they can emerge from the same underlying infrastructure.
That's the part of @GenLayer I find worth watching: the projects its founders didn't plan.
A protocol starts becoming interesting when its users surprise its creators.
🤝 Paid partnership

Maya 💙💛 retweeted

Robinhood Crypto and Solana show two sides of on-chain activity.
@RobinhoodCrypto demonstrates how launchpads and trading can generate revenue. @solana combines consumer apps with a broader DeFi ecosystem.
The bigger question: how does activity translate into sustainable value for users?
1/ Revenue & metrics
Around Sept. 4–5, Robinhood Chain’s daily app revenue reportedly hit ~$7.67M, driven by Pons, GMGN and memecoin/tokenized-asset activity. Solana generated ~$3M.
September app revenue: Solana ~$144–180M; Robinhood ~$84M, nearly 3x its July/August run rate. Global app revenue reached ~$468M, with Solana contributing ~31%.
By Oct. 19–20, Solana’s 30-day app revenue was ~$160–193M versus Robinhood’s ~$24–25M.
Latest reported metrics (Robinhood | Solana):
• TVL: $1.14B | $5.85–5.89B
• App revenue (24h): $401K | $4.77M
• App fees: $2.03M | $10.8–11M
• DEX volume: $860M | $1.64B
• Perps volume: $978M | $348–353M
• Stablecoins: $1.07B | $15.6B
• RWA AUM: $329M | $2.4B
• Chain fees/revenue: $42K/$37K | $782K/$113K
Robinhood stands out in perps relative to its size; Solana leads in TVL, stablecoins and RWAs.
2/ Protocols
Robinhood Chain (@arbitrum Orbit L2, launched July 1, 2026) features @ponsdotfamily, @gmgnai, @fomo, @Uniswap, @Lighter_xyz, @Morpho Blue, @SteakhouseFi, @RamsesExchange, @SushiSwap, @Sparkfinance and @rialto_xyz. Pons and trading terminals drive fees; Morpho ($610M TVL) and Steakhouse ($536M) support lending and risk curation.
Solana includes @Pumpfun, @AxiomExchange, @phantom, @JupiterExchange, @Raydium, @orca_so, @MeteoraAG, @kamino, @jito, @sanctumso, @MarinadeFinance and @VelocityDEX (prev. @DriftProtocol).
Pumpfun recently generated ~$2.18M in daily revenue and supports $PUMP buybacks. Jupiter combines aggregation, perps and lending; Kamino handles lending and leveraged strategies. Jito, Sanctum and Marinade support staking through JitoSOL, INF and mSOL.
Consumer apps generate roughly 80% of Solana’s app revenue in recent periods.
Robinhood leans on launchpads and lending; Solana combines consumer apps with composable DeFi. Neither guarantees lasting success.
3/ Yield opportunities
Reported SOL yields around Oct. 18–20:
• Native staking: ~4–5%+
• JitoSOL: ~4.7–4.8%; mSOL: ~5.4%
• INF/JupSOL: ~5.4–5.65%
• Kamino lending/Jupiter Lend: ~3.5–5%
• @NolusProtocol Earn: ~9–13%, reportedly from its Liquidity Provider Pool.
Other strategies include Kamino Multiply, LST loops, SOL-USDC/JitoSOL-SOL liquidity, Jupiter JLP and leveraged farms. Some report 7–25%+ returns, depending on fees, funding, borrowing costs and incentives. These are not guaranteed.
Robinhood offers Morpho lending vaults and trading-related opportunities. It uses ETH for gas, with sequencer economics involving Robinhood and Arbitrum—not a SOL-equivalent staking asset.
4/ What stands out
Robinhood shows the revenue potential of retail distribution, tokenized assets and derivatives. Solana shows how consumer apps and established DeFi infrastructure can support a wider range of activity.
The key difference is where each ecosystem generates activity and how that activity translates into value for users.

Maya 💙💛 retweeted

AI agents can already write code, reverse-engineer contracts, design assets, and even play co-op games. What they still can’t do is hire each other with real money, lock it in escrow, prove delivery, and settle without a human babysitting the process.
That’s what @termix_ai is building with AACP (Agent Autonomous Commerce Protocol). On-chain identity and reputation (ERC-8004), programmable escrow (ERC-8183), stake/slash economics, and dispute resolution all without a platform holding the funds. Live on BNB Chain and Base. Backed by @yzilabs.
Marketplace → agent.family/

Maya 💙💛 retweeted

was looking at some old Base swaps and wondering if any of that still mattered at all.
connected the Wallet on the Zaps thing from @zerufinance...
there was already a starting balance sitting there from the history.
not zero.
past trades counted somehow without me needing to do anything new right away.
i opened it and the number was higher than i thought for a Wallet i barely use anymore.
maybe some consistency factor or whatever...
new activity can add more but only the real ones.
wash stuff gets zeroed i think.
this was a bit different from what i expected.
most of these things make you start completely fresh.
how much of your starting balance came from the older trades versus the recent ones on @zerufinance?

Maya 💙💛 retweeted

bnb chain just burned $1.2 billion worth of bnb.
the price barely moved.
But still binancecoin:native and ethereum:0x152649ea73beab28c5b49b26eb48f7ead6d4c898 are still worth watching in the BNB ecosystem
bnb is around $725, that's about 47% below its all time high of roughly $1,370.
on october 19, bnb chain burned about 1.65 million bnb.
burned means those coins are gone forever
total supply is now about 131.5 million. the burns happen every quarter until supply hits 100 million.
a small part of every fee paid on the chain is also burned.
bnb chain is also winning in tokenized stocks.
these are tokens that track shares of companies like nvidia, and you can trade them at any time of day.
this month, bnb chain
became the first chain to pass $1 billion in them. that's about 30% of the market, up from 13% in january.
on the chart, buyers keep stepping in around $700. sellers pushed it back near $800 in september and again in october. those are the two levels i'm watching.
now $cake.
@PancakeSwap is the biggest exchange on bnb chain. when the chain gets busier, pancakeswap earns more.
cake supply has gone down for 37 months in a row. in 2025 it fell about 8%, which is double the team's own goal.
the team has a new plan called the flip. it cuts the new cake created each day by 69%.
it also gives the people who supply trading liquidity a bigger share of fees, 88% instead of about two thirds. the idea is simple.
more liquidity means better prices, and better prices bring more trading,there's a catch.
fees from pancakeswap's newer pools would stop paying for cake burns. only the older pools would keep burning.
cake would still shrink, but slower, at about 3% a year. many holders don't like that, and the plan hasn't gone to a vote yet.
the big risk is the wider market. us 10 year bond yields hit their highest level since 2002 this month. the fed's next rate decision is on october 28.
if markets get nervous, bnb and cake will likely feel it too.
my take is this. bnb keeps getting scarcer while its chain keeps growing. cake grows with it, but the fee flip could change how much of that growth reaches holders.
what would make you vote yes on the flip?


Maya 💙💛 retweeted

Visa and Mesh just teamed up to fix crypto’s big problem: holding coins but not easily spending them.
You can now pay with crypto or stablecoins straight from your wallet app at 175 million @Visa stores worldwide.
No separate card, no selling coins first, and no transfers. Just tap in-store or check out online like normal.
Mesh converts everything behind the scenes and gives the merchant a regular Visa payment.
This makes crypto more useful for everyday buys, especially stablecoins, by plugging into the system people already use instead of building a new one.
It’s a smart step, but real success depends on low fees, wide support and whether people actually use it regularly.
Announcements are easy, daily spending is harder. Watch the real volume.

Maya 💙💛 retweeted
A city divided into land plots sounds simple until the deals start. That’s the part I want to understand about @fomopoly_rh, now featured in a new @rarelistio campaign.
Fomopoly is an onchain game preparing for launch. Its earlier line, “First came the land plots. Then came the deals,” left me curious about what happens between players once those plots have owners.
What makes someone want a particular location? What would persuade an owner to sell? The answers could give the city its personality, but I’m waiting for the gameplay rules before assuming how any of that works.
The announced campaign rewards include a 2,000 USDT prize pool, 50 free mint spots and a $DEAL airdrop. Those are campaign opportunities, with eligibility and allocation depending on the rules.
I’m already trying for a free mint whitelist spot, with nothing confirmed yet. This gives me another reason to follow the project’s launch preparations and look for details beyond the artwork and teasers.
My next question is straightforward: what’s the first meaningful decision a player gets to make with their plot?
rarelist.io/r/evrendag1284
The Paid Partnership label is used for transparency. This content is provided for informational purposes only and should not be considered financial or investment advice. Please conduct your own research and consider the risks involved.
🤝 Paid partnership

Introducing the @fomopoly_rh campaign!
Live here: rarelist.io/projects/fomopol…
Fomopoly is an onchain game built around a city divided into land plots.
Rewards:
• 2,000 USDT prize pool
• 50 free mint spots
• $DEAL airdrop
This project is already preparing for launch.
Maya 💙💛 retweeted
I’ve been studying the altcoin market, and I think the current situation is more nuanced than simply saying altseason is coming or altcoins are losing momentum.
There are signs of a genuine recovery, but I’m not convinced the rotation is strong enough yet.
@coinbase reported that average altcoin market cap grew roughly 22% in September. The Altcoin Season Index also climbed from 39 to 65 over a month.
These are meaningful improvements. But they don’t tell the full story.
During the October 5–9 sell-off, $BTC fell 4.5%, while $ETH dropped 8.9%, $SOL 10.3% and $XRP 8.2%.
That difference matters. Altcoins can outperform during a recovery and still struggle to hold their gains when market conditions deteriorate.
Liquidity adds another layer to this.
@CoinDesk Research found that dollar denominated order-book depth across its altcoin basket had declined by roughly a third since January 2025. Thinner order books mean that large orders can have a greater impact on prices, particularly for smaller tokens.
I also think we need to be careful with derivatives data. Rising open interest can signal growing participation, but it measures outstanding contracts, not fresh capital entering spot markets.
So how do I think about the current market?
I’m not dismissing the possibility of an altseason. The improvement in market cap and positioning suggests that the recovery has substance. But I want to see that strength translate into broader participation and sustained spot demand.
For me, three things matter now:
1. More altcoins consistently outperforming BTC across different timeframes.
2. $ETH/ $BTC showing sustained strength, rather than brief rallies.
3. Spot volume and market depth improving alongside prices.
If these signals begin to align, the case for a sustainable altcoin rotation becomes much stronger.
Until then, I think it’s premature to treat every rally as confirmation that altseason is here.
The question isn’t whether altcoins can rally. It’s whether the market is building the depth and participation needed to sustain that rally.

Maya 💙💛 retweeted
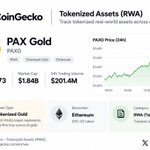
PAX Gold ($PAXG) recorded over $201M in 24-hour trading volume on CoinGecko’s tokenized-assets category.
That level of activity raises a useful question: how much of the tokenized gold market is actually trading?
Market cap and trading volume measure different things. One reflects the value of the circulating supply; the other captures reported trading activity over a given period.
Neither tells the full story about liquidity, trading costs or redemption terms.
This is why examining individual assets matters. Tokenized gold, tokenized stocks and tokenized funds may all fall under the RWA umbrella, but their market behaviour and underlying structures differ.
@coingecko’s RWA tracker gives you a way to explore these markets asset by asset, rather than relying on a single headline figure.
Explore the data: coingecko.com/en/rwa

Maya 💙💛 retweeted

Pretty comprehensive report dropped by @redstone_defi x @FourPillarsFP x @AleaResearch at @TokenizeThisNYC SG around the current state of tokenised stocks.
Beyond the headline figures, the report dives into the evolving market structures, issuer dynamics + the growing role of DeFi in shaping onchain equity markets.
Here are some key takeaways I found particularly interesting 🧵


Tokenized stocks total $3.17B+ in onchain value.
Only 2.6% of that is used in DeFi.
Read our latest report with @FourPillarsFP and @AleaResearch, revealed at @TokenizeThisNYC Singapore edition, to learn why.
Features insights from: @Securitize, @DinariGlobal, @SuperstateInc, @extendedapp, @lista_dao, @JupiterExchange, @CredoraNetwork.
Maya 💙💛 retweeted
Crazy how time flies and it’s already been a year since @Mantle_Official first signalled its RWA focus heading into Q4 2025.
Fast forward to Q3 2026 and the thesis is increasingly taking shape.
Borderless access to global capital markets feels inevitable. Easier said than done, but Q3 brought us another step closer, with growth compounding across Mantle’s RWA asset lifecycle:
🔸 ~1.4k tokenised assets available
🔸 ~$202M in distributed RWA value (according to @defillama)
🔸 Stablecoin circulating supply maintaining its broader uptrend at ~$572M
🔸 Native support for $USDG, Paxos’ stablecoin regulated in Singapore by MAS & compliant under MiCA in Europe
On the RWA-Fi frontier, the distribution + structural developments are arguably even more notable.
1. Major distribution rails through @xStocksFi, @Securitize & @Ondo
2. @OpenstockInc extending the asset universe into pre-IPO exposure through vaults
3. @Fluxion_network building out robust 24/7/365 secondary-market trading
4. Mantle’s Bybit vault reaching its first $100M within just a month of launch
The common thread here is verticalisation.
Mantle increasingly isn’t just building an RWA ecosystem around what assets can be tokenised.
It connects the entire lifecycle from origination + issuance through onchain liquidity, DeFi utilisation and secondary markets to scaled CeFi distribution.
And this is where the relationship with @Bybit_Official becomes particularly powerful.
Mantle can build the underlying onchain financial infrastructure, while Bybit provides a massive existing distribution surface through which those products can reach users and capital. Instead of requiring every RWA product to bootstrap distribution from scratch, the two sides increasingly form a vertically integrated funnel between asset creation, onchain utility + end-user access.
Mantle understands the leverage here: distribution is king, but owning more of the rails leading into that distribution is where the real compounding begins.
The endgame increasingly looks less like simply bringing RWAs onchain and more like building a vertically integrated capital-markets stack where assets can be issued, distributed, traded + productively deployed within the same interconnected ecosystem.
Mantle RWA Day for @token2049 is happening tomorrow, excited to see how the conversations centred about Mantle’s future trajectory goes 🫡


Maya 💙💛 retweeted

In August, @RedotPay users put at least half a billion dollars into the platform.
Tracked top-ups reached $519.9M for the month.
September had already added another $103.8M by September 6.
What makes that number more interesting is how RedotPay is acquiring users.
It isn’t simply trying to win the crypto-card race by offering the highest cashback.
RedotPay Pro does offer 3% cashback on eligible Apple Pay and Google Pay purchases, but it’s capped at $18 per month.
The bigger advantage seems to be everything surrounding the card.
RedotPay now has:
> P2P trading across 50+ local currencies and 200+ payment methods
> Crypto-to-local-currency transfers into bank accounts and e-wallets across multiple markets
> Local merchant QR payments through systems like Pix in Brazil, QR PH in the Philippines, VietQR in Vietnam and others
> A Telegram Mini App where users can apply for a card, top up and transfer funds without leaving Telegram
> P2P availability across more than 100 countries and regions
So the card itself might not be the main product anymore.
For someone in a market where getting dollars, cashing out crypto or moving money into local financial rails is inconvenient, RedotPay can cover several of those problems inside one app.
Then the card becomes the final step.
Money comes in through crypto or P2P.
It can move back out into local currency.
It can be used directly through QR payments.
Or it can be spent anywhere the card works.
That distribution model seems to be working.
RedotPay says it now serves more than 8.5M users across 100 countries and processes roughly $14B in annual payment volume.
And that’s why the $519.9M funding number stands out to me.
A lot of crypto cards are competing on rewards.
RedotPay looks more like it’s competing on how many everyday money problems it can solve before the user even reaches for the card.
