




Pinned Tweet
$NUAI Thesis
I know you’ve probably been seeing $NUAI across your timeline recently, and was wondering what the deal with the company is. When I first saw this micro-cap stock on my timeline, I was extremely hesitant. But, after looking deeper I started to draw parallels to companies like $IREN and $APLD before the markets inevitably priced in what they could be worth. For those of you who have been in $IREN you understand that a 10x means speculating on an asset before its true value becomes obvious to the market, and seeing a vision for a company that plans to transition to something different. I believe $NUAI is the next 10x opportunity at $4.60, and here’s why.
Introduction
$NUAI’s flagship site is called TCDC, or Texas Critical Data Centers, that is 1.4GW Gross or ~1GW Critical IT load, in Ector County near Odessa, TX. I believe the market is completely missing the scale of what is happening at the TCDC site. If you haven’t been paying attention closely it’s easy for the recent announcements to fly under the radar. Since the beginning of this year $NUAI has put out announcements every couple weeks forging partnerships with energy generation partners, hiring significant industry leaders, and working meaningfully to prep their site for their hyperscaler client.
Following the Breadcrumbs
At the beginning of the year $NUAI closed the acquisition of the remaining 50% stake of TCDC from SharonAI, their original JV partner on the project. This was to have total control over the land to build new partnerships, and likely at the hyperscaler clients request to bring a new JV partner to the table.
In late February $NUAI announced a 450 MW Behind-the-Meter Generation Plan at TCDC with Thunderhead Energy and TURBINE-X Energy to generate power for the project. They have a SPV/venture where they have partnered with a private equity firm to fund the capital required to source, install, and run 450MW of gas turbines. They will generate an ROI as they sell power to NUAIs TCDC tenant. This equipment is normally extremely difficult to source, and $NUAI was able to grab these 2-3yr long lead time items in an extremely supply constrained environment, showing the connections of the upper management. The notable thing about this partnership is that they don’t have to put any capital upfront for this equipment, allowing them to start generating revenues while loaning the equipment without huge dilution (~70m).
Then, in mid-March $NUAI hired Ted Warner, ex head of the Energy, Power, and Digital Infrastructure at Northland Capital Markers, where he successfully structured and managed more than $7 billion in financing solutions specifically for large-scale data center developments. This was the signal that caught my eye and made me significantly up my position in the company. Something notable is his PSU’s, or Performance Stock Units, which reward him significantly for “Entering into a binding commercial agreement with a hyperscaler for a minimum of 200 megawatts”. Judging by his history I put him as an A+ hire, and you can see more about his notable achievements here.
xitter.cf/litigious_dulce/status…
Now, to get into the most recent developments that completely change this company from just a speculative random micro-cap to a more credible multibagger infrastructure play. On April 1st, $NUAI secured an LOI with Stream Data Centers. Originally, $NUAI was slated to co-develop the TCDC site with other partners (first Sharon AI, then Primary Digital Infrastructure). However after back and forth for months the unnamed hyperscaler tenant likely mandated that their own preferred execution partner handle the physical construction and operation. Stream is one of the top data center
This project with Stream will be done in a GP/LP fashion, where instead of issuing billions in new stock to pay for construction, the deal utilizes a heavily levered GP/LP (General Partner / Limited Partner) joint venture structure, operating at roughly 80% Loan-to-Cost (LTC). The roles exist as such:
The Originator ($NUAI): $NUAI acts as the local sponsor. They bought the TCDC 438-acre site, secured the initial power footprint, navigated local Texas politics, and laid the development groundwork. Originally I had thought that this agreement would mean passing up the GP role fully to steam and forfeiting their GP revenue streams as the originator. After contacting IR they said “we expect the final structure to reflect the contributions from each (NUAI as a project originator + local relationships, Stream as the developer)”
The Operator (Stream): Stream Data Centers steps in as the development manager and operator. They bring the engineering blueprints, the construction expertise, and the direct, trusted relationships with the hyperscaler. The hyperscaler obviously has a preference for this developer and has likely worked with them before.
The Institutional Capital (The LP): An unnamed institutional investor (99%+ confidence being Apollo, given their majority ownership of Stream) acts as the Limited Partner, writing the massive equity checks and leading the project financing. Apollo Global Management is consistently ranked among the top, most influential, and pre-eminent firms in private equity globally. It is commonly considered part of the "Big 4" of the PE industry and a mark of validation for this project that shouldn’t be looked past.
What this structure does is it protects $NUAI shareholders from the dilution that is so costly to shareholders in a company like $IREN, which long term (2-3 years) has potential to grow into a 100B+ market cap giant, but will need to dilute massive equity to get the cashflow flywheel going (as shown by 6B ATM). A 1.4 GW campus costs upwards of $12 Billion to build, and $NUAI cannot fund that on its own balance sheet. I expect this LOI to be facilitated into a binding agreement in the next 2-6 weeks.
The second piece of news that is the most convincing is the $290M credit facility from Macquarie. Just to put it out, in case it isn’t obvious already, Apollo and Macquarie don’t blindly gamble on some random micro-cap without doing extensive underwriting and due diligence on the parties involved. They deemed $NUAI worthy enough at a $250 million market cap to receive a $290 million multi-tranche facility that shifts the risk profile of the entire TCDC project.
The structure goes as follows: a $20M committed Term Loan A-1 to kick off development, followed by $30M and $40M tranches, with a massive $200M Delayed Draw Term Loan waiting for execution milestones. That’s already impressive in itself, and likely came from Ted Warner’s existing relationship with Macquarie, but an even stronger validation is the equity kicker. Macquarie took a direct $5 million equity stake at a 20% premium to market share price, taking their entry at exactly $5.00 per share. They also have a tranche of warrants that will have an exercise price of $5.00. The warrants will be issued across the first $50 million drawn on the Facility.
When one of the largest infrastructure lenders in the world is taking an equity stake at a 20% premium to the market’s price, it should tell you everything you need to know about the asymmetry of this setup. You have to ask yourself, would Macquarie offer a loan of this size to a random microcap without doing extensive due diligence and underwriting of an advanced hyperscaler LOI or term sheet?
Luckily, we got the answer to that hidden in the SEC filing of the Macquarie term loan agreement without a formal press release from $NUAI. $NUAI currently has an LOI in place with a hyperscaler tenant as of March 24th, 2026. I believe the reason it was not put in the form of a press release was at the hyperscalers request, and you can read more about it below from @kamikazzzi1981
xitter.cf/kamikazzzi1981/status/…
Now that all of the pieces of the puzzle are starting to come together that a hyperscaler deal is imminent, what should the company actually be worth?
Stock Price Projections
Firstly, I'd like to get out of the way that if you believe that $NUAI will secure a hyperscaler deal in the first place the announcement alone will probably put the stock around 2x higher than the current prices, or around $9-$10/share. This is by giving Stream, one of the most reputable data center builders hand selected by a hyperscaler, around a 60% chance of execution from the math below. If you want to, from that point, you can decide whether you want to sell, or if you believe they can execute the numbers start to get pretty wild.
From Phase 1 alone, with super conservative assumptions (more likely to be ~$1.50M EBITDA/MW)
Phase 1: 200 MW x $1.35M EBITDA/MW = $270M project EBITDA.
At 50% ownership, that is $135M to NUAI.
At a 14x-16x EBITDA multiple, that suggests $1.9B-$2.2B of value, or $14-$16/share on 135.5M fully diluted shares.
Northland’s analysis used a 19x EBITDA multiple in their analysis, 14x-16x is extremely conservative. At a 19x multiple you get a share price ~19$/share
If they can fully execute on Phase 1, the full TCDC 1.4GW campus can be modeled out as done by @ThePrudentWhale
xitter.cf/ThePrudentWhale/status…
• $34.51 Price Target in a 100% success case.
• $25.91 Probability-Weighted PT (applying a 25% execution risk haircut).
And here is super conservative bit of the model: this entirely excludes Behind-The-Meter power generation economics for phase 2+, GP stream revenues, 7 GW New Mexico development pipeline, and the reinvestment of cash flows into the futures phases of the projects for more equity.


Updated the $NUAI model. Added an EBITDA multiple based valuation alongside the NOI / cap rate valuation. Both screenshots below reflect base case assumptions.
View v19 here:
docs.google.com/spreadsheets…

ALT NOI / Cap Rate Valuation Base Case

ALT EBITDA Multiple Valuation Base Case
Compute retweeted
This is a really good question and I’ve done a lot of thinking on this myself. In theory, the cost of intelligence drops down to the cost of an electron as a function of time. So the question is, where is the value accrued at if it’s a race to the bottom?
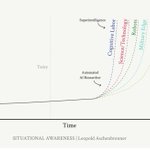
First it’s important to look at the frontier labs as they are on everyone’s mind and it seems like a headline comes out every day talking about how they are going to fail. It’s important to see that they currently capture their value from the differential of intelligence over its competitors. As time goes on, assuming that these behind them are catching up that differential closes, especially with open source on their tail. Obviously the heads of Anthropic and OpenAI know this, and it’s the reason why they have been so heavily focused on preventing distillation from taking place. It was important that they cracked down on this, despite causing an interim flatlining in revenues, because their entire value proposition relies on it. The next step is to reach full RSI (Recursive Self Improvement) where the models train themselves. I included a graph from Leopold Aschenbrenner’s Situational Awareness paper here to demonstrate what happens when AI’s reach RSI. This will likely be the breaking point away from open source models, and it will give the frontier labs such a decisive lead in the intelligence race.
Now, the question is how much are OpenAI and Anthropic willing to spend to get to this point as soon as possible? The truth is, from a game theory perspective, their entire business model relies on it. On the other end of that curve is the cure to every single illness, physics problem, robotics, etc and that’s where the true value is accrued. How much do you believe they are willing to spend on compute here for the time being?
This brings me back to the original question you asked which was what does it mean for the price of compute/power. It depends on how much value you believe is on the other side of this and how fast they can achieve this. That’s why short term power is so valuable right now. The problem is on the capital side for the time being where many of these projects are not going to be completed due to power, driving up the $/MW and financing rates. But this then goes back to more capital for Anthropic and OpenAI to pay to fund their future commitments. For these reasons don’t see how the price can peak unless lenders stop lending, which the Gov can’t let happen in the current economic state.

Couple of my thoughts on the current stage of the AI buildout, frontier labs, and GPU pricing.

This is a really good question and I’ve done a lot of thinking on this myself. In theory, the cost of intelligence drops down to the cost of an electron as a function of time. So the question is, where is the value accrued at if it’s a race to the bottom?
First it’s important to look at the frontier labs as they are on everyone’s mind and it seems like a headline comes out every day talking about how they are going to fail. It’s important to see that they currently capture their value from the differential of intelligence over its competitors. As time goes on, assuming that these behind them are catching up that differential closes, especially with open source on their tail. Obviously the heads of Anthropic and OpenAI know this, and it’s the reason why they have been so heavily focused on preventing distillation from taking place. It was important that they cracked down on this, despite causing an interim flatlining in revenues, because their entire value proposition relies on it. The next step is to reach full RSI (Recursive Self Improvement) where the models train themselves. I included a graph from Leopold Aschenbrenner’s Situational Awareness paper here to demonstrate what happens when AI’s reach RSI. This will likely be the breaking point away from open source models, and it will give the frontier labs such a decisive lead in the intelligence race.
Now, the question is how much are OpenAI and Anthropic willing to spend to get to this point as soon as possible? The truth is, from a game theory perspective, their entire business model relies on it. On the other end of that curve is the cure to every single illness, physics problem, robotics, etc and that’s where the true value is accrued. How much do you believe they are willing to spend on compute here for the time being?
This brings me back to the original question you asked which was what does it mean for the price of compute/power. It depends on how much value you believe is on the other side of this and how fast they can achieve this. That’s why short term power is so valuable right now. The problem is on the capital side for the time being where many of these projects are not going to be completed due to power, driving up the $/MW and financing rates. But this then goes back to more capital for Anthropic and OpenAI to pay to fund their future commitments. For these reasons don’t see how the price can peak unless lenders stop lending, which the Gov can’t let happen in the current economic state.
Compute retweeted

Beyond our project in Hawesville ( Justified) - 2027 is simply not available. Scarcity! That’s why we were able to lock in a great customer on great terms so quickly for Justified. And I agree - the opportunity for customers is huge. They are not nickel and diming the collocation partner because they need compute yesterday. If anything, they are prepared to spend what it takes to accelerate already contracted projects.
Bond market is already sniffing out $CRWV running into issues being a buyer of GPU’s without owning the physical infrastructure. Spreads for investment grade colocation deals despite this remains tight. The market is going to have a rude awakening once it understands that the scarcity comes from the power, labor, permits, and capital that allows the chips to be brought online. Equity markets shoot first and take down the colocation/neocloud sector without differentiating and understanding the implications. $IREN $CIFR $WULF $NUAI





$IREN New Partnership with Real Madrid
They now sponsor the Golden State Warriors, Real Madrid, and Sydney Swans. Quite the marketing spend.
realmadrid.com/en-US/news/cl…

Compute retweeted

Blackwell Ultra (B300) GPU rental prices up 17 consecutive days to a new all-time high, according to Compute Desk's index of verified transactions from U.S. neoclouds.

Compute retweeted

Doomberg AI of course mangled the message. It is this kind of reporting that discredits their brand. Well filtered X (control your inputs!) is far superior.
Hock said compute demand exceeds supply into 2030
The casino line came during a discussion on OAI capital raise, and Hock rejected the idea that it's overvalued. He blamed investors who set extreme expectations w/o understanding the tech. Down in the actual text of the article it reports him saying OAI has a viable biz model at 50bn ARR and that the losses are training spend.


Compute retweeted

“Small public companies are first discovered by smart retail, then by small institutions, then by large institutions, and then finally by dumb retail.”
— @iancassel
Compute retweeted
Last week I shared 10 takeaways from our recent investor meetings. The response was tremendous, and so were the follow-up questions.
Many were with respect to the market; price action, volatility and sentiment. Interest rates. Geopolitics. Financing concerns. Rising costs. Community opposition. There's a lot weighing on the sector.
Listen - I can't control the market. But I can drive how we build this business, allocate capital and create shareholder value.
So let's address a few things head-on.
Compute retweeted
$IREN returns after being on the longest red streaks in the past. Now 7 red days in a row going into Friday.
Average returns:
1 day out: +12.0%
1 week out: +15.5%
1 month out: +15.3%


$IREN returns after being on the longest red streaks in the past. Now 7 red days in a row going into Friday.
Average returns:
1 day out: +12.0%
1 week out: +15.5%
1 month out: +15.3%
Compute retweeted

$nuai @StreamDataCentr JV probability decreases daily
Evidence continues to pile up suggesting that $nuai will build its own team in house to complete construction rather than partner with Stream.
Jose Rodriguez and Evan Pierce specifically played a more significant role in the prior earnings call as management wanted to signal to the market that $nuai possesses in-house talent with hyperscaler backgrounds.
The hiring of Doug Hofmockel, who most likely worked with Evan and Jose at ByteDance, as well Doug’s recent LinkedIn post seeking electrical engineering expertise to design hyperscaler data centers paints a picture of a firm evolving in real time and looking to adopt the $iren $cifr $wulf approach of in-house DC construction rather than rely upon third party contractors as heavily.
Lastly, consider how the company commented on negotiations in the past few weeks:
NUAI is actively discussing lease arrangements directly with multiple potential anchor tenants, including one of the world's largest consumers of AI infrastructure. (Most recent 8-k)
That is why I find the most recent analysis from sell side shops that claim 45-50% JV interest to be incorrect as it $nuai appears to be looking for more economic upside post PPA.


Compute retweeted

We heard big news from the Ector County Commissioners Court today about $NUAI and its TCDC project! The judge said that now that the 200 MW power deal is signed, "this is starting to become a reality." New Era asked for no tax breaks and will pay the full rate, which could mean HUNDREDS OF MILLIONS in property taxes, back to the community. The county is getting ready for this to be built, and it's a huge win for the local community. @LovedropV @fnitefiend

Compute retweeted

Built a $NUAI TCDC valuation model with @optionology & @lovedropv.
We modeled 3 lease rates across P1+P2, using 12x after signing & 15x stabilized.
Base case: $22.99 → $33.69/share.
Directional model, not a PT. Assumptions below 👇

Compute retweeted

$NUAI at $7. The asymmetry here is fucking enormous and I don't think the market has figured out what this could become.
I've followed it since Jan. It was quite literally a different co then.
The thesis is simple. AI needs an obscene amount of power and power is the bottleneck.
493 acres in Texas, permits in hand, and a path to 757MW of BTM power. The land and the power to build a massive AI data center campus w/out sitting around waiting for the grid.
Phase 1 has 207MW contracted under a 20 yr PPA w @VistraCorp. Signed. Not classified, not conditional, not pending a study, actually signed.
That's the distinction people are missing. $CIFR just got conditional Batch Zero classification on 3.2GW and ripped 9%. Conditional means projects can still be removed if they fail verification, and ERCOT's final transmission plan for that group isn't due until fall 2027.
Contracted power and conditional power are not the same asset.
Now they need one thing. A tenant.
Mgmt. has guided to an investment grade hyperscaler. That's a small universe, all of whom have said time to power is their number one constraint.
Sign one for a meaningful chunk of the site and this stops being a speculative land + power story and becomes contracted AI infra. Completely different co.
I own plenty of $IREN, $NBIS and the other names everyone already knows. Nothing wrong w/ crowded trades. But this is one of the few I've found recently where the gap between what it is and what it's priced as is this wide.
I own 103,138 shares and the Jan27 $7.50s and wonder if it's enough.
Compute retweeted

I think one of the best things you can do to become a better investor is to learn about everything.
The more you understand history, economics, technology, science and even engineering, the better you understand how the world works and how it is changing. History gives you context, economics helps you understand how money moves through the economy, while science, technology and engineering help you understand what is being built and where the world could be going.
You don't need to become an expert in any of them. You just need to keep learning, because the more you understand about the world, the easier it becomes to connect the dots and recognise opportunities before they become obvious to everyone else.
Compute retweeted
The presumption that the Fed raising short-term rates reduces inflation is predicated on the belief that higher rates reduce demand and investment.
But what if higher rates don’t reduce demand and investment because the demand for intelligence and energy is unaffected by higher rates because winning the race for super intelligence has a near infinite ROI and the demand for compute will remain incalculable.
Why won’t higher rates at this unique moment in history therefore lead to more inflation as interest costs are embedded in everything?
And the problem is compounded as the more the Fed raises rates, the more inflation we will have and the more the Fed will need to raise rates further and so on.
But what if the old models don’t apply to the current paradigm and the Fed is wrong?
I think the Fed might have just made a mistake. Am I right or am I wrong?
Compute retweeted

The ATM solves for the Macquarie covenant. It doesn’t automatically mean they need to sell $100mm in stock. No dilution has happened yet.
Macquarie has to make a credit decision to handle the LOC and wrap it in the deal. That’s the next announcement before Oct 9th.
The real focus should be what they said in the filing today:
“
The Company has prioritized negotiating towards one or more transactions directly with a tenant partner and is focused on discussions with multiple potential tenants, including one of the “world’s largest consumers of AI”infrastructure to serve as its anchor tenant for its flagship project pursuant to a direct lease.
If we enter into a letter of intent with a tenant, it will be non-binding…
“
—Additionally, the Company may continue to explore joint ventures with development partners.
…particularly in the event of a direct lease without a development partner.
Don’t be surprised if NUAi attempts to do this without the JV, taking 100% of the deal and recapitalizing the company with help from Macquarie or the HPC directly.
The JV is no longer the required wrapper for $NUAI.
“Think Bigger”
That’s exactly what the mgt team is doing.

$NUAI announced a new $100M ATM program today.
My view: this is neither purely bullish nor purely bearish.
An ATM is a financing tool, not an immediate $100M dilution.
The company is not obligated to sell any shares, and management can decide when, how much, and at what price to issue.
That said, the market is right to price in some near-term pressure:
• potential future dilution
• additional share supply on rallies
• uncertainty around how aggressively the ATM will be used
At ~$7/share, fully using the program would require roughly 14M new shares, so the dilution is not trivial.
But the other side of the equation matters too.
$NUAI is moving from development-stage planning into actual execution:
• Phase 1 power is now contracted
• permitting continues to advance
• construction readiness is improving
• future project capital requirements are becoming more real
Having access to equity capital reduces financing risk, even if it introduces dilution risk.
For me, the interesting part is how this interacts with my options strategy.
Most of my earlier short puts are now close to expiration or have already captured nearly all of their premium.
So if the ATM announcement creates short-term pressure on the stock — while the underlying thesis remains unchanged — it may create another attractive put-selling window.
That is exactly the type of setup I look for:
temporary price pressure + elevated IV + improving fundamentals
I am not trying to predict whether $NUAI trades at $6.50, $7, or $7.50 next week.
I am asking a different question:
At what effective price would I be comfortable owning more shares if assigned?
If the market gives me attractive premiums at strikes where I am willing to own the stock, I am happy to let volatility work for me again.
The ATM may create a short-term ceiling.
But it may also create the next volatility opportunity.
The key questions now are not simply “Is there dilution?”
They are:
How much is actually issued?
At what price?
And what value does that capital create?
Personal investment view, not financial advice. $NUAI