

G2AI tracks the US-China(G2) AI stack
Joined April 2026
- Tweets211
- Following34
- Followers1.6K
- Likes93






Terafab won't buy from China. And it's shopping in Korea
According to new report from TheElec, Tesla and SpaceX have started sourcing Korean materials, components and equipment suppliers for "Terafab," Musk's semiconductor project targeting 1 million wafers per month.
Roughly 10 Korean companies have reportedly signed NDAs, and more than half are already in product-spec talks. The names surfacing: Eugene Technology, Jusung Engineering, HPSP, Hanmi Semiconductor, Techwing, Simmtech, ASFLOW, SKC. Tesla and SpaceX reps met them directly during Semiconductor Week in Silicon Valley (Nov 13–15).
The scale: a $16.8B site in Texas, an initial facility around 100k wafers/month, ramping toward 1M — with SpaceX already acquiring a fab in Bastrop.
The NDAs are the real story. They reportedly cover specs, volumes, pricing, joint development, even exclusivity. One supplier said they signed on the spot, minutes after landing.
Why Korea? Price competitiveness and speed. Why the anxiety? Musk's first instinct was reportedly Chinese suppliers — and they're still in the mix.
Lam Research and Applied Materials have stood up Terafab task forces too. The supply-chain scramble is on.
Link: thelec.kr/news/articleView.h…

GS raise global servers TAM by 31% / 45% in 2027 / 28E across general servers
and AI servers to reflect the ongoing generative AI infrastructure investments and
specification upgrades:
(1) General servers: raised value by 17% / 11% in 2027 / 28E with both shipment and
ASP raised. GS expect general servers shipment to grow at 20% / 12% / 8% YoY in
2026-28E.
(2) AI servers (NVL72, powered by NV & AMD): shipment raised by 5% / 1% to 110k /
164k racks in 2027 / 28E.
(3) AI servers (8-GPU, powered by GPU & ASIC): shipment raised by 10% / 29% to
2.7m / 3.3m servers in 2027 / 28E. GS new AI servers shipment forecasts imply AI
chip demand of 18m / 29m / 38m in 2026-28E, or a ~60% / ~50% ASIC penetration
rate globally / global-tier in 2028E. GS continue to see a rise across CSP capex,
fabless shipment, and foundry capacity, driving an AI infrastructure upcycle.


In China, an 8-GPU B300 server with the 3TB configuration now costs more than RMB18 million, while monthly rental rates have exceeded RMB400,000. Token prices, however, have remained largely unchanged, putting sustained pressure on the gross margins of “token factories.”
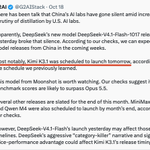
There has been talk that China’s AI labs have gone silent amid increasing scrutiny of distillation by U.S. AI labs.
Apparently, DeepSeek’s new model DeepSeek-V4.1-Flash-1017 release yesterday broke that silence. According to our checks, we can expect more model releases from China in the coming weeks.
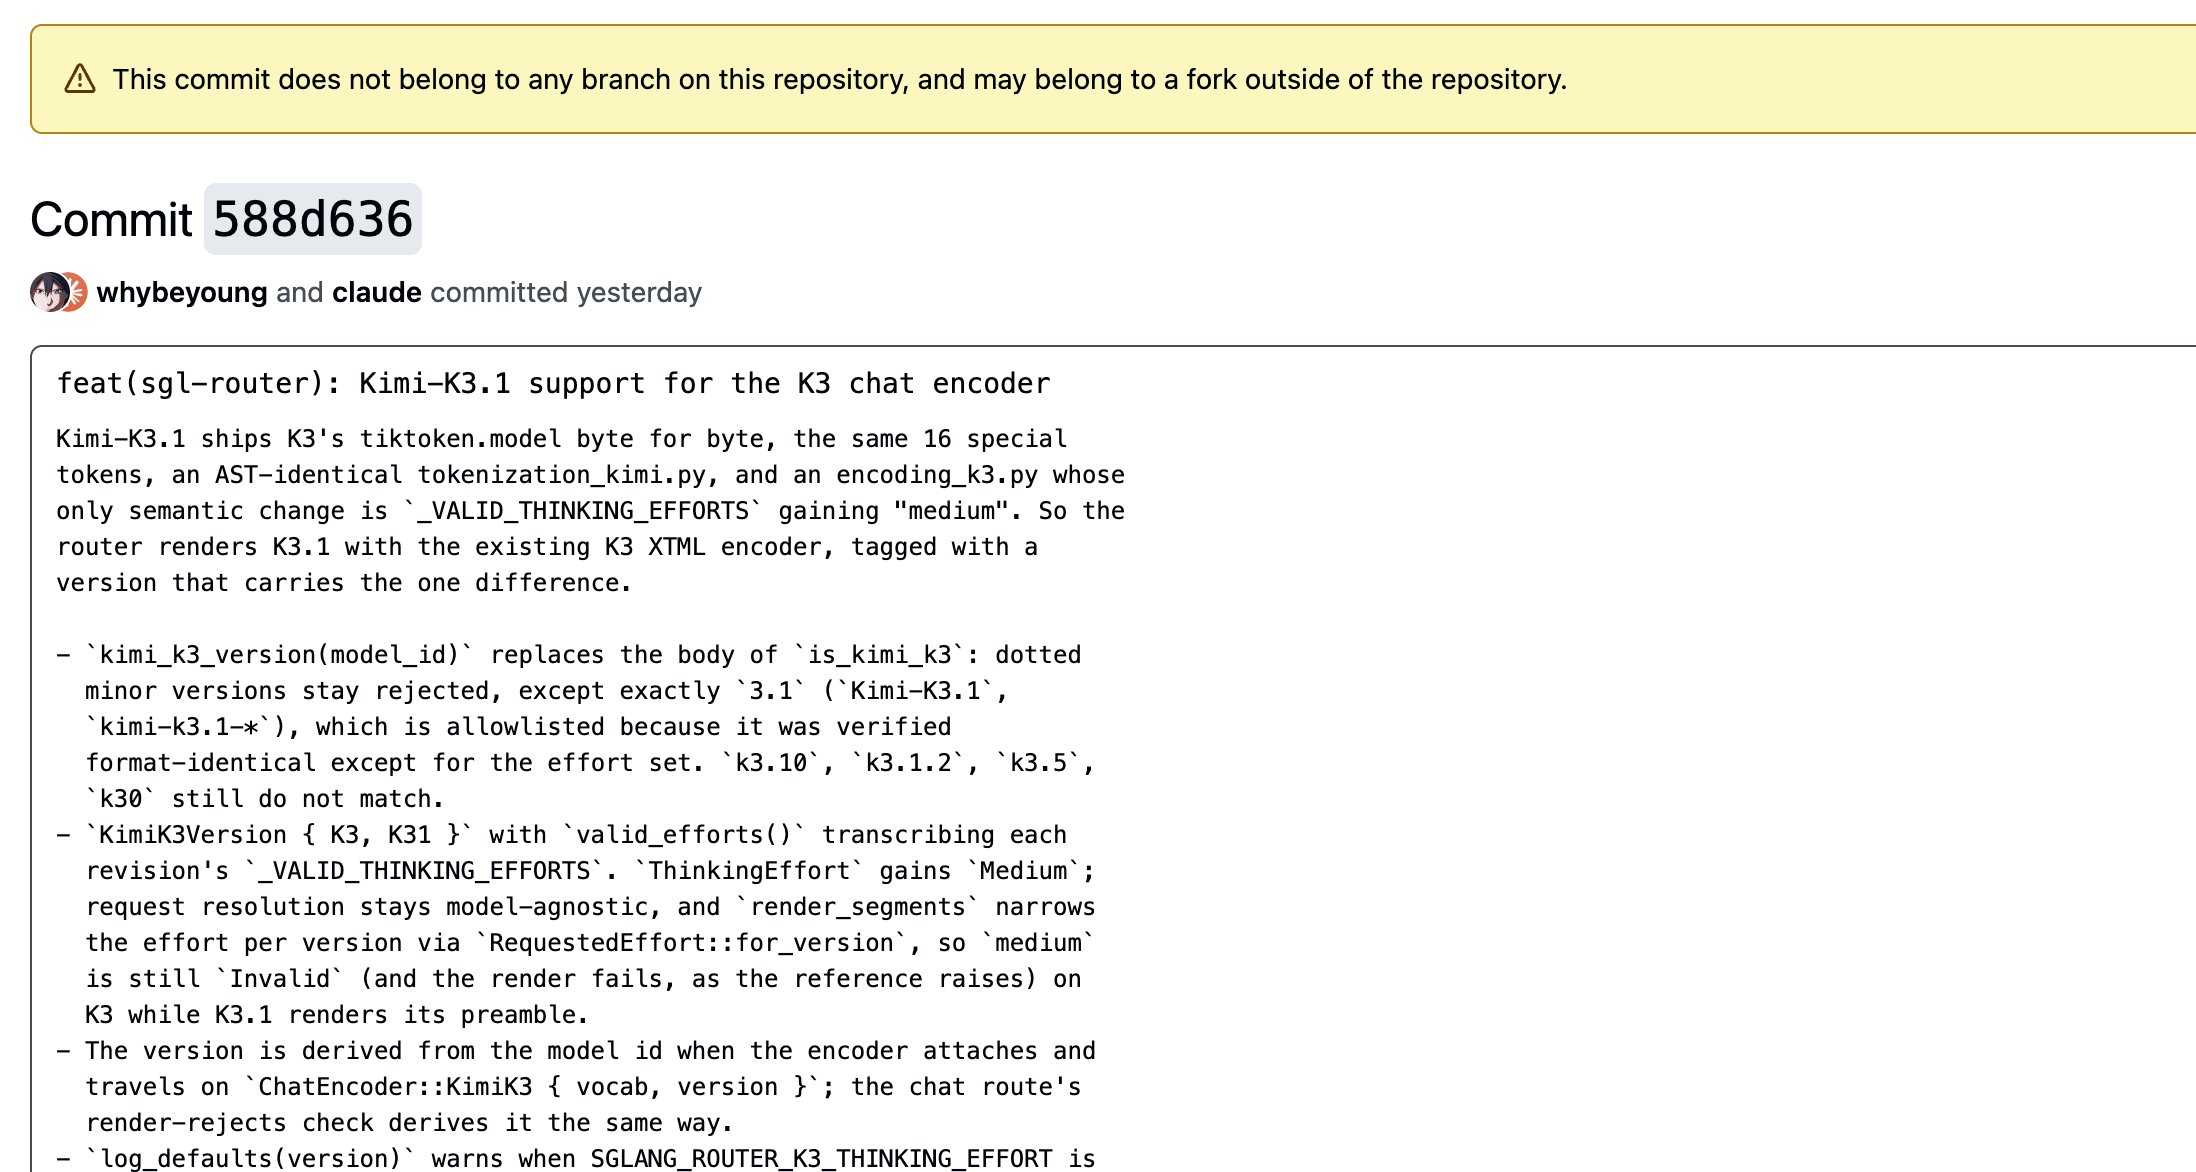
Most notably, Kimi K3.1 was scheduled to launch tomorrow, according to the schedule we previously learned.
This model from Moonshot is worth watching. Our checks suggest its benchmark scores are likely to surpass Opus 5.5.
Several other releases are slated for the end of this month. MiniMax 3.1 Pro and Qwen M4 were also scheduled to launch by month’s end, according to our checks.
However, DeepSeek-V4.1-Flash’s launch yesterday may affect those timelines. DeepSeek’s aggressive “category-killer” narrative and significant price-performance advantage could affect Kimi K3.1’s release timing.

🚀 DeepSeek-V4.1-Flash-1017 is here!
Stronger benchmark performance, faster task completion, and shorter outputs than the previous version—a Pareto improvement in performance and cost. Now live on our website, app, and API.
🛠️ Optimized for @DeepSeekHarness, Tencent CodeBuddy, WorkBuddy, and more. Upgrade to DeepSeek Harness v0.2.1-rc.1 or later for the best experience with the new model.
1/4


(Repost)
You can clearly sense that DS is changing—from what used to feel like a lab-style organization into a more commercially driven company.
1/ This is probably the first time it has officially used this kind of “kill line” narrative in its marketing.
2/ DS, which previously placed little emphasis on front-end experience or visual modeling capabilities, has followed the community’s preferences this time—making it more likely to go viral—and strengthened these areas in the latest iteration.


While improving performance, it also reduces model runtime and input length
🚀 DeepSeek-V4.1-Flash-1017 is here!
Stronger benchmark performance, faster task completion, and shorter outputs than the previous version—a Pareto improvement in performance and cost. Now live on our website, app, and API.
🛠️ Optimized for @DeepSeekHarness, Tencent CodeBuddy, WorkBuddy, and more. Upgrade to DeepSeek Harness v0.2.1-rc.1 or later for the best experience with the new model.
1/4
For CXMT, Morgan Stanley was significantly more bullish than Goldman Sachs, with the company’s actual results landing somewhere in between.
Revenue and net profit both beat Goldman’s estimates, but clearly missed Morgan Stanley’s forecasts.
More notably, the net margin fell short of even Goldman’s relatively conservative estimate, suggesting that while revenue delivery was solid, earnings conversion was weaker than expected—potentially due to costs or minority interests.


Compared with the 2020 rules, the new framework is far more precise. Broad descriptions have been replaced by measurable thresholds covering model size, training compute, agentic task complexity, and cluster interconnect bandwidth.
The bigger shift is in enforcement: temporary pre-export registration, exemptions for open-source and academic work already in the public domain, and streamlined licensing for overseas computing centers and offshore chip tape-outs.
China proposed export controls on 23 AI technologies on Friday, including those involving models, agents and computing clusters, its latest move to limit transfers of tools it views as vital to national security and geopolitical competition with Washington.
The proposals cover overseas deployment of AI models containing restricted technology, but exclude access through application programming interfaces (APIs), websites, apps and software-as-a-service platforms
reuters.com/world/asia-pacif…
Why widening credit spreads matter for the AI trade
1/ The AI selloff isn’t just about ARR, valuations or demand. Widening credit spreads add another important dimension to the story: AI infrastructure growth is inherently credit-dependent.
2/ Companies are borrowing heavily to finance data centers, GPUs, power and networking. If credit spreads widen, financing becomes more expensive—and sometimes unavailable. Strong demand alone cannot sustain growth without capital.
3/ The sequencing matters: credit weakened before equities. Stress initially appeared in CCC debt, then spread into the broader high-yield market while Treasuries and the S&P 500 were still relatively stable.
4/ CoreWeave is the clearest example. With its bond yields rising above 15%, the equity had to reprice. At those levels, either the bonds or the stock had been mispricing the company’s financing risk.
5/ The entire AI trade assumes future growth will fund today’s leverage. Wider spreads challenge that loop:
Higher funding costs → slower infrastructure buildout → weaker growth → greater credit risk.
6/ Investors should watch high-yield spreads, refinancing costs and new issuance alongside GPU demand and ARR. The credit market may be the earliest warning that the AI capex cycle is becoming harder to finance.
This is consistent with the data we obtained.

According to TMT Breakout, Anthropic’s ARR was around $7.8–8.0 billion at the end of September. However, our industry checks suggest it had not yet reached $7.8 billion, though the gap was relatively small.
We’ll soon release data models covering OpenAI, Anthropic, Zhipu AI, Kimi, and DeepSeek. Stay tuned.


Nomura--Wire & cable Optical devices
1/6
The AI optical component cycle may be stronger—and last longer—than the market expects.
Lumentum’s CEO says active optical products are fully sold out through early 2029, while some customers have already started locking in orders for 2030. $LITE
2/6
The supply gap is significant:
• For some products, Lumentum may be unable to meet 70% of demand through end-2027
• For others, around 30% of demand may remain unmet through end-2028
• Capacity is expanding rapidly, but remains well below customer requirements
3/6
The next wave may be even bigger.
Lumentum expects demand for lasers used in next-generation AI systems to accelerate around 2029, creating a market potentially “another order of magnitude” larger than today.
Nomura believes ultra-high-power lasers for scale-up CPO will be a key growth driver.
4/6
Nomura highlights Sumitomo Electric $5802 as a potential beneficiary:
• Progress on NVIDIA qualification for CPO lasers expected in FY3/27
• Meaningful CPO laser sales could begin in 2H FY3/28
• Resolving current production issues could unlock further earnings upside
• Potential indirect exposure through InP substrates and other supply-chain links
Some of these supplier relationships are Nomura’s estimates rather than officially confirmed arrangements.
5/6
Furukawa Electric $5801 could also benefit:
• Optical-device yields are stabilizing
• Its FITEL products business has turned profitable
• DFB laser sales are expected to increase
• Lumentum expects pump-laser volumes to quadruple over the next five quarters
Furukawa is a major pump-laser supplier alongside Lumentum.
6/6
Fujikura $5803 does not manufacture the relevant laser components, making it a less direct beneficiary of this specific trend.

Rubin shipment expectations have been cut from roughly 10,000 systems to around 5,000, mainly due to yield and capacity constraints affecting GPUs, orthogonal backplanes, power systems, and related components.
Our checks with ODMs confirm that Rubin shipments are indeed falling short of expectations.
GS--HBF: Cracking the AI Memory Wall
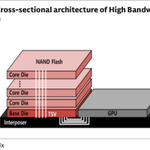
GS sees high-performance NAND (esp. High-Bandwidth Flash) as a real fix for the AI inference memory wall—and a CapEx saver.
TAM ~$40–150bn by 2030 at 15–50% GPU adoption
~30% lower cost of inference throughput → potentially hundreds of bn in hyperscaler CapEx savings
Bull case: HBF on 50% of XPUs by late 2028 → ~4% of NAND bits but ~9% of wafer capacity (HBM-like die penalty)
Near term: tight NAND stays tight; HBF could extend the cycle
Risks: latency, endurance, thermal, manufacturing intensity
Favor SNDK & SK Hynix on HBF tech lead; Samsung well placed; Micron less of a NAND beneficiary
HBF is early at system level—but the economics look attractive even at a big premium to commodity NAND.


