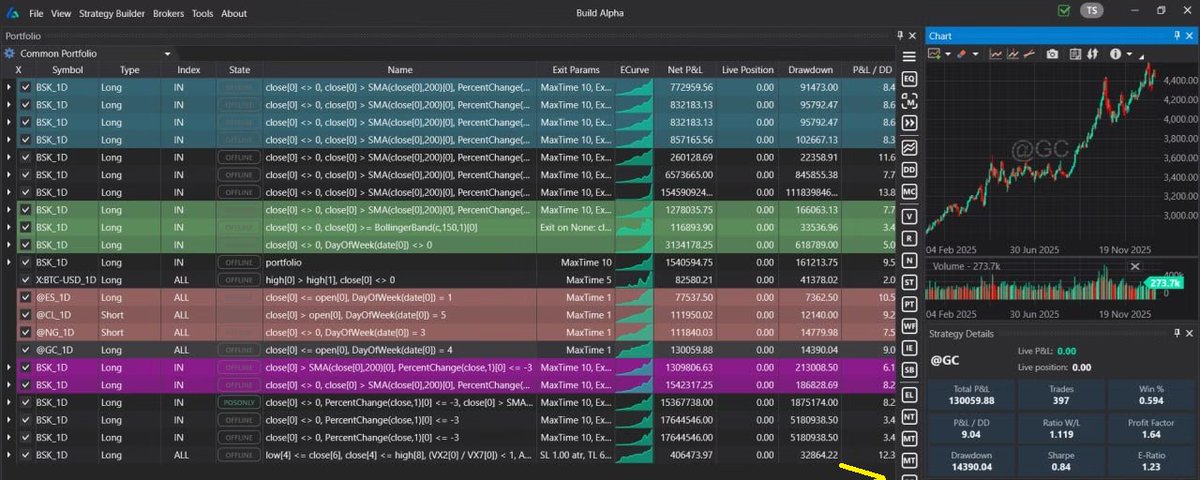
Quant Trader for High Frequency Trading firm. Mostly C++, Python, and Charts. Checkout Build Alpha @buildalpha software below
Joined April 2011
- Tweets4.3K
- Following123
- Followers11.2K
- Likes6.2K





Dave Bergstrom retweeted

I am convinced prop firm trading is an entirely different ballgame than trading cash accounts.
Traditional metrics like Sharpe, smooth equity curves and low max drawdown aren’t what you should be optimizing for to maximize prop payouts.
I actually added new fitness functions to find more prop firm compatible strategies
-probability of passing eval
-probability of first payout
-expected return per attempt
It is best to think of prop evals as a call option.
The option premium is the fee
The max loss is the fee
And the upside is essentially unlimited payouts
Options love volatility. Why are you trading the eval like it’s your retirement account?
The best strategy for your own capital is often the wrong one for an eval. Totally different games.
You may not even want the same strategies to pass the challenge as the ones you'll trade once funded.
That's why the prop firm simulator can sort by these different metrics.
I'll be showcasing more of it later this week with a full write up.
Dave Bergstrom retweeted
A weekend read with some real data and ideas to test.
A simple mean reversion strategy in SP500 that buys when price closes in the bottom 20% of the day's range and sells when price closes in the top 80% of the day's range.
Look at the impact a market regime filter can have.
Big jump in average trade and big reduction in time in market. A great candidate for a position sizing scaler (covered in the article below)


Dave Bergstrom retweeted
ICYMI full write up on detecting and using market regimes in your trading
Stat of the day: check your moving averages

Dave Bergstrom retweeted
This prop firm math post was pretty controversial despite providing the math 🙃
So I couldn't resist ha! here's prop firm math part 2
47 unsuccessful attempts. 3 payouts. Still profitable.
Consider LucidFlex 50K, assuming a $105 evaluation price.
50 attempts over time would cost:
50 × $105 = $5,250.
Suppose just 3 eventually reach one maximum $2,000 payout request.
After the 90/10 split, you receive $1,800 per payout:
3 × $1,800 = $5,400
$5,400 received
$5,250 spent
+$150 (before other costs).
The other 47 attempts fail and produce nothing.
6% (3/50) reach a max payout while 94% lose.
For this simplified one-payout model there is an
Expected profit per attempt =
Probability of reaching payout × $1,800 − $105.
So break-even is approximately 5.83%
The question is, do you think you can build strategies or (better yet) a portfolio of strategies that get to one payout 6% of the time? If so, you print.
150 on 5250 invested is 2.86% return. If you run this every month, you're north of 30% per year while failing 94% of challenges. Uncomfortable? Yes. Profitable? Yes. That's usually how trading works.
These prop firms are mostly math. Many traders build one strategy, fail and claim it is a scam. Turn the odds in your favor by understanding your numbers.
More on the BA prop simulator soon..
Prop firm math is CRAZY. A losing strategy can become a winning strategy under a prop firm structure.
Imagine a strategy that:
• Wins $200 on 90% of days
• Loses $2,000 on 10% of days
Trading your own capital, its expected daily P&L is:
90% × $200 − 10% × $2,000 = −$20 ❌
Now imagine a hypothetical prop arrangement:
• $100 total fee per attempt
• Five winning days to pass the evaluation
• Five more winning days in the funded account to receive an $800 cash payout
• Any losing day closes the account
• No additional costs or payout restrictions
Assuming independent daily outcomes, the probability of reaching that payout is:
90%^10 = 34.9%
Your personal cash outcomes become:
• Reach payout: $800 − $100 = +$700
• Fail before payout: −$100
Expected profit per attempt:
34.9% × $800 − $100 ≈ +$179 ✅
The strategy has negative trading expectancy, but this hypothetical "prop" contract gives the trader positive cash expectancy.
Why? Because you absorb the evaluation fee instead of the strategy’s full trading losses. This opens up what strategies and portfolios can look like.
It is a completely different design and optimization problem for strategy and portfolio development.
This week I will be sharing more about the prop firm simulator I've built and what it can do.
Dave Bergstrom retweeted
The last week or so I’ve covered four different signals and filters for context-aware systematic trading. Here’s a recap for wknd readers.
Gamma Exposure: option market maker positioning. Dealers will quiet directional price moves when long gamma and will extend directional price moves when short gamma.
Commitment of Traders Report: understand how different players are positioned. Large speculators are net long and retail is net short is different than large specs net short and retail extremely bullish.
Market Breadth: what’s going on under the hood. Is this rally well supported or only due to a few names. Will there be follow through?
Event Conditioned signals: sequence matters. If last hour yesterday rallied hard, what does that mean for today’s open? How we got here is as important as where we are.
Links in the comment for full explanation and example signals you can test.
If you like this type of content let me know with a comment. I have more haha

Dave Bergstrom retweeted
Markets have memory. Most trading signals don’t.
The same signal can mean something completely different depending on what happened earlier in the session.
And what happened earlier changes what happens next.
Think of a football game's score. 21–17 tells you the state of the game. It matters if the team down 17–0 has just scored three straight touchdowns, or was ahead 21–0 and is collapsing.
That’s the idea behind event-conditioned signals. A trading signal conditioned on an earlier event.
Examples:
• Yesterday’s last hour was strong → does today’s first hour follow through?
• Opening range closed higher → does the last hour tend to rally?
• Price was above VWAP at noon → does that strength persist into the close?
• Today’s opening range is unusually large → are breakouts more likely to continue?
I've added a ValueWhen function that stores what happened at a specific time or event, then we can use that information later or even the next session.
Available in the custom editor and the prompt to signal feature.
This greatly expands the types of signals and strategies possible.
I put together 168 ready-made event-conditioned signals covering:
• Last-hour behavior
• Opening-range behavior
• VWAP checkpoints
• Open / ORH / ORL relationships
• Body-to-range ratios
• High/low-of-day structure
Then you can mix them with Build Alpha’s other built-in signals and/or your own custom signals and let Build Alpha + AI test which combinations actually survive validation.
The more context your strategy has the more robust it can be.


Dave Bergstrom retweeted
The strategy that would have saved your worst drawdown is sitting in your reject pile.
You threw it out because it looked bad. Nobody keeps an ugly strategy.
This is one of the major flaws in how most strategy development works. We (system traders) typically evaluate strategies on a standalone basis.
Best profit, best sharpe, smoothest equity curve, whatever. Then just mash them together in a portfolio and pray they work together.
It’s why I built Portfolio Search
You pick a saved portfolio and instead of generating the best single strategies, it generates strategies that contribute to what you already have.
The fitness function (optimization goal) becomes marginal contribution to that portfolio instead of the strategy's own backtest.
Portfolio Lift toggles every metric so you can see the percentage improvement from adding each candidate strategy.
Portfolio View lets you click through and watch the combined equity curve change.
The ugly strategy that you discarded but actually need is now discovered on purpose and presented with data. A more thoughtful way to develop.

Dave Bergstrom retweeted
The best trading research workflow is one you don’t have to sit and supervise.
That’s the idea behind Sequence Workflows in Build Alpha.
Instead of:
Run a broad search on 10 years of data
Wait, then manually
Take the survivors and test the last 3 years
Wait, then manually run
Run Robustness Tests like Monte Carlo
Wait, then manually
Test on another date range as a final check
…you can now configure the entire research pipeline once and let Build Alpha run it end to end.
Each round can have its own:
• Date range
• Performance filters
• Robustness filters
• Advancement criteria
Example:
Round 1 → mine until you find 2500 candidates
Round 2 → first out of sample test
Round 3 → Monte Carlo Permutation
Round 4 → Noise Test, Vs Random
Round 5 → final out of sample test
You can also tell it:
“Advance when 200 strategies pass, OR after 3 hours, whichever comes first.”
No more manual babysitting. No more coding.
Set the sequence. Hit start. Come back and see either
· surviving strategies
-or-
· a clear answer where things broke down
Both are actually useful and save a lot of time.

Dave Bergstrom retweeted
What if your settings or prompts aren’t good?
That’s the next-gen backtester in Build Alpha.
Connect Claude, GPT, Gemini, Grok, Open Router, etc.
Build Alpha begins generating candidate strategies. The connected model monitors the results
• checks for performance plateaus
• changes settings, entries, and filters
• authors new signals to try
• advances winners to robustness tests
• rejects anything that fails
• exports code to NT8, MT5, TradeStation, Multicharts, TradingView, ProRealCode or Python
• stores its learnings in local memory so the software gets smarter each time you use it
Some strategies work. Most don’t. You need to find out at computer speed.
Search → test → reject → redirect → repeat. 24/7
Building a backtesting engine that never stops searching. 24/7.
The next generation of Backtesting - AutoTune update:
Automated Strategy Discovery
→ Set initial symbol(s), date range, signal universe
→ Connect any LLM via API key
→ Starts generating new strategy ideas
→ AI monitors performance for plateaus
→ AI changes settings, creates new rules, restarts
→ Profitable ideas advanced to automated validation
→ Unprofitable or failing stress tests automatically rejected
→ Export code to any major platform (NT8, MT5, TradingView, Python)
→ Memory is updated locally so next search doesn't start from scratch
Some strategies work.
Most don't.
But now we find out at computer speed.
Instead of manually hunting for the next edge, there is now a system that can search → test → reject → discover → repeat… 24/7.
Still building. Still improving.
But this has been one of the most exciting updates in a while.
Dave Bergstrom retweeted
Gamma Exposure is one of the cleanest examples of why market regime matters.
Positive GEX and negative GEX can create very different trading environments. And probably why 4,731,956 signal services exist around it 😅
When dealers (MMs) are net long gamma, their hedging tends to lean against price moves:
• sell rallies
• buy dips
• suppress volatility
• encourage mean reversion
When dealers are net short gamma, the opposite can happen:
• buy rallies
• sell declines
• amplify volatility
• extend trends
That means the exact same trading strategy either has a headwind or tailwind depending on the gamma regime. But you're not checking...
Below shows Gamma Exposure (GEX) against tomorrow's SP500 range.
The more negative GEX, the wilder the coming day‼️
Non-price-based signals and alternative data like this are useful to combine with your actual entry logic and test whether your strategies behave differently in different market environments.
Full write up below with 36 custom GEX signals to play with. Download and go. Spread between GEX calculated on SPX vs. GEX calculated on SPX components, Z-score, etc.

Dave Bergstrom retweeted
We all say the same thing about overfitting: the strategy was "fitted to the noise."
So test that directly. Change the noise and see if the strategy survives.
This is the entire idea behind the Noise Test.
Your price history has two parts. Signal, which is the part that repeats. Noise, which is the part that happened once and will never happen the same way again. Every strategy you build is fit to both, and your backtest cannot tell which one it learned.
So change the noise and re-run the strategy.
Here's how it works:
Pick how much of the data to adjust and by how much. Say 50% of the bars, by up to 25% of average true range. Opens, highs, lows and closes get nudged up or down inside that band. Same market, same trend, same volatility (and clustering) but a different roll of the dice.
Create 1,000 noise adjusted data series and re-trade the strategy 1,000 times.
Now you have a distribution instead of a single backtest.
How to read it:
PASS The noise adjusted results do not deviate from your backtest. Most (or all) stay profitable and the distribution sits meaningfully above zero. Your rules were tracking something real.
FAIL The noise adjusted results fall off a cliff. Your original backtest sits way above the distribution and the rest cluster near or below zero. No edge. You fit the one path history happened to take.
If adjusting the noise erases your edge, your edge was never there, and no amount of out-of-sample data would have told you, because your out-of-sample sample data has exactly the same problem: it is one path only.
Reminder: Passing is not proof of edge. It rules out one specific failure and there are plenty of others, which is why this test is only one of a dozen tests (all automate-able) in Build Alpha.
Build Alpha can also optimize your parameters across the noise-adjusted series instead of the single historical one, so you are selecting parameters that work across many versions of history rather than the exact history we lived.
Your price history is one sample. Your strategy should work on the others too!
Dave Bergstrom retweeted
Have a trading idea you've never properly tested?
This video shows full path from signal → simulation → export to your platform.
· prompt signal in English
· select for use in simulation/generation
· export code (NT8 shown in video)
· show matching results
No coding. Now you can automate your ideas and see the data behind them. More coming..
Dave Bergstrom retweeted
How can you tell if your exits are overfit?
System traders can overfit both entries and exits. Hard to tell which but we need to check both.
Monte Carlo only changes the order of existing trades. It preserves the profits and losses produced by the exact exit settings from the backtest.
Build Alpha’s Randomized Monte Carlo Test challenges the settings themselves:
• Keep the entries fixed
• Randomly vary exit parameters on each trade
• Repeat 1,000+ times to get a distribution
For example, a strategy using a 2 ATR stop and rolling 5-bar low as exits might change the ATR multiplier and rolling window for each trade.
No exit rules are added or removed. Just modified.
If most paths remain profitable, stronger confidence you didn't overfit the exits.
If profitability collapses, you're likely in for a rude awakening when you go live. At least you caught it first.
Your equity curve is one possibility. It shows what worked with one configuration. This test reveals how much depends on getting that configuration exactly right.
Stress test both your entries and your exits.

Dave Bergstrom retweeted
xitter.cf/jordanfogel/status/189…
CEO of Renaissance Technologies, Jim Simons, walked down to the Federal Reserve Bank and copied interest rate history on paper by hand.
Alternative Data → Question it helps answer
· VIX Term Structure → Is the market pricing fear or complacency?
· Interest Rate Curve → Is liquidity expanding or contracting?
· Economic Releases → Is today’s price action driven by macro events?
· AAII Sentiment → Are retail investors excessively bullish or bearish?
· Dark Pool Index → What are institutions doing beneath the surface?
· Gamma Exposure (GEX) → Are options dealers likely to dampen or amplify volatility?
· Market Breadth → Is the move supported by the broader market, or just a few stocks?
· Weather → Could weather materially impact supply, demand, or seasonal behavior?
· Google Trends → Is public attention accelerating before price reacts?
· Commitment of Traders Report → How are traders positioned?
Alternative data gives price action much needed context.
Better trading systems start with better questions. Take it from the G.O.A.T🐐
Dave Bergstrom retweeted
One of the biggest fatal flaws I come across is what I call "strategy hopping". So many traders make this mistake and don't even realize it.
Flip a fair coin 10 times. You might get 3 heads. Or 5. Or 6. Or 9.
No way to tell if the coin is rigged in 10 flips. A fair coin and a rigged coin produce the same range of outcomes at this sample size (number of trials).
Flip it 1,000 times and you will know if it's a rigged coin or not.
In statistics, this is known as the Law of Large Numbers. The truth only arrives once you have enough observations, and before that point you are seeing noise and mistaking it for information.
Now consider a trader who watches a few trades and decides it is broken or tweaks his strategy or finds a new strategy altogether...
This is "strategy hopping" and is an account killer.
Each change or tweak restarts the counter.
Back to the left-side of the graph you go.
The trader can be trading for four years and never leave the left-side of this graph. He's stuck in randomness and he cannot escape via strategy hopping. Strategy hopping is actually why he's stuck and bleeding.
Please do the work up front before risking capital. Validate properly, size so you can survive the bad stretch, understand the system's expectancy and where you can be in the next N trades and then stick to it.
You must let the Law of Large Numbers play out. This is the only way to escape randomness and capture the edge you've found. It took me way too long to learn this.