Pinned Tweet
Quite the move in $ACLS / $VECO today - anyone know what's going on beyond the broad strength in semicap?
I'd posted a $VECO long pitch last month (tldr solid growth outlook, too cheap relative to comps):
valueinvestorsclub.com/idea/…
Blowing up my book in chinese internet 🥴
(up to a 2%+ weight now in $BIDU)
I have a loose thesis that aggressive buybacks can, and perhaps will, be the antidote that ails the China internet sector equities. I zero in on $BABA because they've already been putting their $20B+ in annual FCF to work by buying back ~$10B/yr over the last 2 years.
($BIDU cont)
$10B for core biz ($29/shr), it's declining so 3x '27 EBITDA
$18B for Cloud/AI biz ($52/shr), 3x '27 Sales for high growth & teens EBIT margins
$4B for Apollo self-driving ($12/shr)
Total = $88B, or $255/shr
Apply whatever discounts you like, this is undervalued
1H26 +13.0%
Big contributions from semis, semicap, and tech hardware were partially offset by losses in software, hyperscalers, and China
Been broadly trimming semis/hw and adding to software; exposure to each bucket is now roughly similar w each at low 20s net % of portfolio
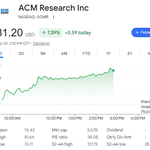
Fairly mild reaction today IMO to $ACMR's once a year backlog disclosure of +88% y/y.
Consensus has revenue growing ~30% y/y in both CY26 & CY27, which feels quite low relative to backlog growth.
Stock is still down (36%) in Q3.
Attn $CMRC board: it's time to put this thing up for sale.
You gave Travis a shot, and even tried a name change. Could have worked. Hasn't.
It's now time to reconnect with Qatalyst and put us all out of our collective misery.
Thank you for your attention to this matter.
Nice to see the $CMRC board finally waking up from their years long slumber 🥳
If we assume the $70M midpoint of cost cuts fully hit in '27 & flat revenue, they're looking at close to $1.00 in GAAP EPS!
Stock is still way too cheap & there's activist involvement now...
This announcement from $CMRC, and the implied EPS, just highlights how extraordinarily dumb it is for a SaaS name to trade at 0.5x EV/S...can always just run the PE playbook & cut your way to 30% bottom line!
investors.commerce.com/news-…
Implies >$1.50 in $SMCI quarterly EPS vs street at $0.71...so the stock is trading at just 5x RR EPS
no idea how GMs came in at 16% vs 8% guide, seems odd
BREAKING: SUPERMICRO $SMCI SAYS IT BOOKED MORE THAN $60B IN NEW ORDERS LAST QUARTER, ROUGHLY 5X ITS QUARTERLY REVENUE
The preliminary Q4 update cuts three ways:
- New orders: in excess of $60B in the quarter, pushing backlog to record levels, to be delivered over future quarters
- Gross margins: estimated 15%-17%, nearly double the 8.2%-8.4% guidance, on favorable customer and product mix
- Revenue: expected near the low end of the $11.0B-$12.5B guide
The read: fewer dollars shipped this quarter, much more profit per dollar shipped, and a demand pipeline far larger than current output.
Two caveats from the release itself:
- The figures are preliminary and unaudited, and the company notes some orders may not be firm commitments and can be canceled or delayed
- The board's previously disclosed independent review of alleged export-control issues could affect these results and prior periods
Full results land August 11.
Penciling out something like $5+ in FY27 NG EPS based on ~$69B revenue midpoint and more normalized ~10.5% GMs
When $SMCI peaked at $100+ in FY24, they did $15B in revenue, ~$2 in EPS
In FY27, they'll do ~$69B in revenue, and perhaps $5 in EPS. Stock is now at $34...interesting
Anyone else think $SPT at 1.2x Sales for 10% top line growth, 10% FCF margins is really interesting? I get that all of software is a zero, but what if it’s not 🤔
I’ve been buying this one since November…
$SPT +5.7% post-market on low volume. CEO buys $1M in shares. This comes after co-founder Aaron Rankin purchased $1M a few weeks ago. FWIW, my buyout bets post pitched $SPT as a prime 2026 buyout target and called for planned insider buys to act as a margin of safety 🤣🤣(which clearly has not been the case, still see SPT being bought out tho).
$SPT posted a modest beat/raise in Q126, but more importantly IMO, announced a $50M buyback (against a ~$450M mkt cap). At 0.75x EV/S & 6x EV/FCF on '26 for ~10% top line growth and margin expansion, this is way too cheap and it's good to see the company finally stepping up
$SPT could end up doing something like $100M+ in 2027 FCF w the benefit of $50M+ in cost savings from the July RIF. They also plan to start being active on the buyback. Stock is still only at ~1x Sales & ~6x EV/FCF on '27...still way too cheap despite the 100% rally off the lows
Parent company DoubleU Games offering to buy out minority shares of $DDI. The offer price seems way too low, and hopefully DoubleU will be forced to increase it
I wrote up a $DDI long in February
valueinvestorsclub.com/idea/…
"DoubleU offers $11.25 a share to buy out $DDI investors"
Interesting: $DDI has traded through the 11.25 offer price today…better offer from DUG on the way perhaps? 🤔
$DDI just did Q126 FCF/ADS of $0.94, ending the quarter with $10.10/ADS in net cash (up from $9.19/ADS at Q425). $11.25/ADS offer price continues to look like a joke.
In addition to the blowout acceleration in billings growth, $CMRC reported their first GAAP EPS profitable quarter with $0.05 in Q126 ($0.20 annualized GAAP EPS)
This stock should not still be trading at <1 EV/S (currently 0.87x on CY26)
Replying to @CVCResearch
Quite the move in $ACLS / $VECO today - anyone know what's going on beyond the broad strength in semicap?
I'd posted a $VECO long pitch last month (tldr solid growth outlook, too cheap relative to comps):
valueinvestorsclub.com/idea/…


