

Premium + 🇩🇪🇰🇷 Quant Value Investor
Frankfurt am Main
Joined June 2024
- Tweets54.8K
- Following4.3K
- Followers5.1K
- Likes48.1K
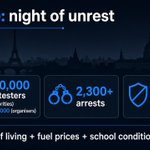






France just had its worst night of unrest in years, and the president went on TV tonight.
550,000 protesters, per authorities (organisers say 800,000). 2,300+ arrests. Limoges city hall burned.
No state of emergency. No curfew.
Here's what Macron said 🧵

2/ The response is practical, not drastic.
The prime minister chairs a crisis cell from tomorrow to speed up help for shop owners. Prefects can ban certain rallies "if necessary". Looters must pay back, he said.
1/ He split the crowd in two.
Hundreds of thousands marched over living costs, fuel prices and school conditions. He called those demands legitimate.
Then he blamed far-left groups and "numerous criminals" for looting and attacks on city halls: "Nothing justifies it."
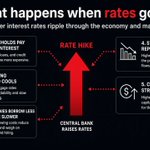
Everyone loves a rate cut.
But cheap money creates winners and side effects at the same time. Here's the full map 🧵

4/ Growth and inflation.
Spending and investment rise, so growth and jobs improve. But if inflation is already high, cutting can add fuel.
3/ Stocks and housing.
Lower discount rates lift valuations, especially growth and tech. Housing demand rises and prices follow. Debt can build up along the way.
2/ Companies.
Cheaper financing means more investment, more hiring and better profit margins. The risk: cheap money keeps weak "zombie" companies alive.
1/ Households.
Mortgage and loan payments fall, so spending power rises. But savers earn less, so money moves into stocks and real estate.
A rate hike is a single decision.
Its effects hit 5 places at once. Here's where the pain and the winners show up 🧵

4/ Stocks and bonds.
Higher discount rates push valuations down, and rising bond yields make bonds more attractive than stocks. Banks and insurers can benefit.
3/ Companies and jobs.
Borrowing costs rise. Highly indebted firms struggle, and hiring and wage growth slow. If it goes too far, unemployment rises. That's why central banks move carefully.
2/ Housing.
Higher mortgage rates mean fewer buyers. Volume drops first, then price growth slows or turns negative.
1/ Households.
Variable-rate mortgages, credit cards and car loans get more expensive. People cut spending on dining, travel and big purchases. Savers earn more.
Central banks don't cut because the economy is weak.
They cut when 4 things line up. The mirror image of the hike checklist 🧵

4/ Deflation or financial stress appears.
Prices fall too far, or debt and asset risks start to hit markets.
3/ The labor market softens.
Hiring slows and unemployment starts to rise. This is usually the signal central banks watch most closely.