

Founder and CIO of RLH Capital Tweets are not investment advice.
Joined September 2020
- Tweets3.6K
- Following510
- Followers3.9K
- Likes3.8K





Pinned Tweet
I’m pleased to share RLH SPAC Fund’s Q2 2026 investor letter, which provides an update on performance and our current positioning.
Investors often assume SPACs require making directional bets.
We think the better opportunities today look very different:
• Attractive trust-backed yields
• Structural downside support
• Optionality that the market often undervalues
Our Q2 investor letter discusses why we believe this opportunity set continues to improve and includes several real portfolio examples.
dropbox.com/scl/fi/toboze7d7…
One of the more striking trends in SPACs has been the poor trading performance of warrants and rights, particularly among announced deals.
Across 69 exchange-listed SPACs, the median warrant trades at just $0.23, while the median rights-implied share price is $1.11.
Despite these depressed valuations, I have yet to see a single insider purchase. Correct me if I'm wrong.
This is exactly what the market is desperately missing. If sponsors believe their deals are worth substantially more than the market suggests, it's time to put their money where their mouths are.
$XRPN $XRPNW @evernorthxrp Updated Estimated NAV: $8.43/share
Following this morning's 8-K, we've updated our NAV calculation. Please do your own diligence and feel free to flag any errors.
Share Count
23.64mm Class A shares
31.39mm Class C shares
22.95mm Pathfinder units
77.98mm basic shares
Both Class C shares and Pathfinder units are convertible/exchangeable into Class A on a 1:1 basis.
After accounting for warrant and convertible debt dilution based on the current trading price, we estimate 84.8mm diluted shares.
NAV Calculation
473mm XRP valued at ~$645mm ($1.36/XRP)
$75.7mm pro forma cash
$6.18mm related-party payables
~$715mm net assets
84.8mm diluted shares
Estimated NAV: $8.43/share
This calculation has been more complicated than it should be, largely because Pathfinder units were disclosed separately from Class A and Class C shares, making the total economic share count difficult to reconcile.
Sources:
Updated share count (Oct. 13):
sec.gov/Archives/edgar/data/…
Pro forma balance sheet:
sec.gov/Archives/edgar/data/…
$XRPN – A great outcome for the company, with the exercise of $XRPNW warrants starting on Monday providing additional capital at $11.50
Warrant exercises followed by an S-1 registration should also help establish a more normalized trading float
Unfortunately, outcomes like this remain the exception rather than the rule, but this is exactly what most SPAC teams hope to achieve
We estimate that over the next 4 weeks ~$2.5bn of SPAC paper will be up for redemption either as part of an extension or transaction vote
Will be interesting to see how those proceeds will be reinvested
$IVAI I learned today this is an options eligible security if it is able to attain 2,000 shareholder requirement

$IVAI
This is pretty interesting. Curious to see how the market prices it.
Structured somewhat like a SPAC (redemption rights), @DivesTech and team will have up to a year to acquire stakes in one or more private companies. @OpenAI came up frequently — unclear whether simply as an example or something they are actively pursuing.
The key question: will investors pay a premium to NAV for access to private companies they otherwise can’t own?
For that premium to persist, the market needs to believe appreciation in the underlying portfolio will more than offset the premium paid for access.
At the IPO price, the yield is roughly in line with the median SPAC, but there are no warrants or rights. Historically, warrantless SPACs have tended to trade at a premium to the broader group.
So what is $IVAI and how will it trade?
A SPAC?
A warrantless SPAC?
Or something the market prices entirely differently?
Should be interesting to watch.
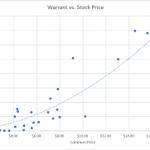
It’s been a long time since I updated our SPAC warrant regression, but the nor’easter gave me some motivation
Looking at SPAC transactions that have closed since 1/1/24, we continue to see a remarkably strong relationship between warrant prices and where the common ultimately trades post-close - 88% R² in our current dataset
Why does this matter?
Prior to a DeSPAC, the common is supported by the trust redemption floor. Warrants have no such protection and can therefore provide a useful market signal for where the common may trade once the trust floor disappears
Our current regression, for example, suggests that an $0.86 warrant implies roughly a $5.00 common stock price
Warrants aren't perfect predictors, but they can reveal information that the pre-close common simply can't.

The “MAGA SPAC” trade looks impaired, but not broken.
The key inflection may have been June 10, when Trump Media/TAE abandoned the proposed $TVA media spin-off—not TVA’s later PlusAI deal, although that deal was not well received based on the warrant price action $TVACW
Since then:
$BLUW warrants have fallen from ~42–45c to ~30c, despite Yorkville taking over the SPAC in Nov. 2025 and replacing the entire board/management team with a group that included Mark Angelo, Kevin McGurn, Devin Nunes and other Yorkville/TMTG-linked personnel.
$NWAX has also seen notable turnover: Kevin McGurn resigned as CEO/director Aug. 5 and was replaced by Chairman Kyle Wool; on Aug. 26, CFO George O’Leary resigned and Tim Ledwick became CFO, with Christopher Devall added as COO.
$MCGA replaced Kevin McGurn as CEO in April with Yorkville partner Troy Rillo, and its TMTG/Crypto.com deal was terminated Aug. 7.
$CLBR is the exception: its warrants continue to command a substantial pre-DA premium, with Omeed Malik as CEO/Chairman and a board including Donald Trump Jr., Laura Ingraham and Blake Masters.
The broad “MAGA optionality” premium appears to have compressed materially, but still priced in particularly for $CLBR evidenced by both its lower YTM and higher warrant prices


$TVA third time's the charm?
Self-Driving Firm PlusAI to Go Public Via Yorkville SPAC Merger
RLH Capital retweeted

$CNGL
the saga continues
love that 2nd paragraph confirming backstop
think redemption is NOT automatic so you have to redeem via your broker

SPAC IPO Update
140 SPAC IPOs have raised ~$24.9bn through Aug. 9.
The market is clearly healthier than it was in Q1 — but healthier does not mean every IPO works.
The data still argues strongly against indiscriminate participation.
1/4
Even that 55% arguably overstates the actionable opportunity set: some of the strongest SPAC IPOs, including certain Leerink and Jefferies-led deals, were largely placed outside the traditional SPAC investor base.
We believe the opportunity remains in security selection, not SPAC beta.
3/4
We also expect the setup for SPAC IPO investors to continue improving
With investors remaining selective, sponsors are increasingly being forced to offer better terms to clear new issuance
If that continues, we would expect IPO performance to improve further — even without a broad return to indiscriminate demand
4/4
$IGTA definitive proxy to extend to 62 months!
They have been making monthly contributions and publishing 8-k's monthly, which we appreciate, however the contact phone number is out of order...