



After a good night's sleep and going through the earnings call, I can safely say: Man, what a crazy quarter SpaceX just had!
A few interesting takeaways that caught my attention:
♦️AI Compute Pricing: Currently estimated at $30–50 per watt, an important benchmark to keep in mind for future valuations and assessing returns on AI infrastructure investments.
♦️ Tesla Merger: Things are getting interesting! Both Tesla and SpaceX have established special board committees to explore a potential merger. Nothing confirmed yet, but definitely a development worth watching.
♦️ Backlog: Climbed to $63B from $47B last quarter, with most of it expected to convert into revenue over the next 12 months.
♦️Capex: The spending spree isn't slowing down. Q4 capex is projected to nearly double from Q3, potentially reaching ~$40B.
♦️ Revenue Growth: And the growth story is far from over. Management is projecting a staggering $33–37B in revenue for Q1 2027 alone!
The numbers are extraordinary, but what interests me most is whether SpaceX can translate this explosive growth and massive infrastructure spending into sustainable free cash flow in the long run.
🚀 $SPCX Q3 2026 is impressive!
📈 Revenue +161% YoY to $14.6B
🛰️ Starlink subscribers: 7.2M → 13.6M YoY
But here's the catch:
💰 9M 2026 net loss: $413M
🏗️ 9M 2026 CapEx: $48.1B
Explosive growth, but massive investment requirements.
Is the valuation justified?
🎥 My full Space Economy breakdown on YouTube is out 👇
youtu.be/kYHU_v63sxk?is=KgeO…


So $SPCX reports this Tuesday.
It's 6M revenue; it came in at a total of 12.5 billion.
What kind of numbers do they need to report for stock price action to continue validating its premium or even increase it?
I just couldn't watch from sidelines anymore, decided to take a small position for a swing on $NBIS.
This selloff is getting ridiculous.
Tesla just unveiled its first flying car yesterday!
Yes, you read that right. A flying car! And if you ask me, those thrusters look like they might have a little SpaceX DNA in them. 🚀
And what better time to dive deep into the space economy than right now?
From rockets to satellites and beyond, the opportunities are getting harder to ignore.
Enjoy the deep dive! 🌌
Out on Substack now 👇👇
time24trader.substack.com/p/…
When people ask what kind of synergies $TSLA and $SPCX can offer...well like the ones in the video 😅

I haven't been so much active this week (job what can you do), but I catched up with the bloodbath that is ongoing this week, especially within AI related names.
Neoclouds are getting absolutely smashed.
Macro is getting shittier with inflation making more pressure on FED.
I am seing eventually danger for future financing that has not yet been secured, but then again as long as demand remain strong long term thesis should not be breaking down, yeah margins might be less attractive but it's not the end of the world.
Funny how $NOW and $DUOL are having strong days today.
"From this day onwards, you shall refer to me as Mr. Hylord."
Now all that's left is for the @hylo_so team to continue cooking.
Hylish. 💪

Yesterday I decided to enter a swing position in $AVGO.
Depending how things will evolve I might turn it into long term position.
This is a risky one from the perspective that it's only ~28% down from all time high, but on the other side it's the one in bed with $NVDA as the one of the names selling picks and shovels for this AI cycle.
They are one of the key players in making customized chips for data centers (like Nvidia is making generally good chips for everything and Broadcom is designing chips for specific use to make it more efficient depending on the use case).
Now the thought behind interest in them is simple for me, if we will continue to have demand for data center creation then $AVGO will be one to continue to benefit big from it (I think we will at least based on information now).
While their RPO (179B) is not on the levels of $ORCL (664 Billion), if I am bullish on Oracle as the one building data centers how couldn't I be bullish on Broadcom, which plays one of the crucial role in data center buildout all the while not having Capex & FCF burden which Oracle carries.
To be clear market is already pricing that in, as Broadcom sits at 3x larger market cap (1.7T+) compared to Oracle (420B+).
Both companies are having impressive growth targets with Broadcom targeting 200B in AI revenue by 2028.
So Broadcom is projecting strong growth, all the while keeping low Capex and strong FCF conversion (for now).
Now the recent weakness came related you guessed it, Open AI annualized revenue miss, and as Broadcom is rumored to be in talks with OpenAI like it already has with Antropic to act as a kind of backstop in providing guaranteed money, no suprise market fire torched them.
I saw this catalyst as an opportunity to start a position in $AVGO and now what kind position will it be depends how will fundamentals develop with time, either to make the thesis stronger or weaker.
To make this position turn from a swing to a long term position,for start I want to see managment giving clues about demand post 2028 demand & data center buildouts.
Next I will focus on how their margins hold as they ride through this expansion and probably some things I am even not aware of now.
AI cycle continues in full swing, and so does the increase of uncertainty with macro headwinds.
Happy weekend everyone!

While SpaceX is falling today, some major developments are happening beneath the surface.
The FCC just cleared $SPCX to deploy up to 15,000 Direct-to-Device satellites, essentially pushing Starlink toward a global mobile network that can connect directly to ordinary smartphones.
At the same time, Starship just took another major step forward with its recent successful orbital mission and payload deployment.
Put the two together:
Starship → cheaper, higher-capacity deployment
15K D2D satellites → massive constellation expansion
Starlink → connectivity increasingly moving from terminals directly into everyday devices
The price can fall while the underlying infrastructure keeps moving forward.
FCC deployment deadlines:
♦️50% of the 15,000 D2D satellites by October 2032
♦️The remaining 50% by October 2035
$MCD is attempting that bounce.

I decided to start a swing position in McDonald’s $MCD.
What I like:
The stock is sitting near an important multi-year support area and looks stretched from a technical perspective.
At the same time, the business still generates strong free cash flow, the franchise model remains highly cash generative.
What I don’t like:
Debt is high, U.S. traffic has weakened, and recent comparable sales have slowed materially.
The biggest risk is that what currently looks like an execution issue turns into a more structural demand problem.
What I’m watching most closely:
U.S. comparable sales and guest count.
If comps stabilize and guest count turns positive again, that would materially strengthen the thesis. I’ll also keep an eye on FCF, margins, interest expense and debt.
My first decision point is around ~$260.
If the stock reaches that area while fundamentals are improving, I may continue holding toward higher technical ranges or even the 50-week EMA.
If comps/traffic keep deteriorating, or the current support zone fails, I’ll look to trim or exit.
For now, this is a starter swing position, not a long-term conviction position yet.
$MCD
This is not a financial advice.
The AI opportunity for ServiceNow may be much bigger than selling copilots.
Today $NOW launched AI Workflow Factory + Autonomous Engineer.
The interesting part isn't another AI feature.
It's the architecture.
Enterprises will have dozens, potentially hundreds of agents across different models, clouds and applications.
Someone still needs to:
📌 orchestrate them
📌 connect them to enterprise
workflows
📌 control permissions
📌 track what they did
📌 provide governance & auditability
ServiceNow wants to own that layer.
In other words:
The more fragmented enterprise AI becomes, the more valuable the control layer could become.
That's the part of the $NOW thesis I'm watching.
It is a good day for neoclouds today.
I decided to take a look at projected annual revenue for ex-Bitcoin miners based on their contracts and duration.
$MARA is not on the list as it still doesn't have a big contract like the rest.
What's interesting to me is that in the case of extreme dilution, $IREN stands at 68%, which is the highest amongst the ones I compare it with ($WULF is a close second with 61% projected dilution), and it still looks attractive from a P/S perspective.
Take into consideration I excluded optionality in $WULF ( potentially an additional +23B) and $CIFR (+4B) in case their contracts are expanded from the original plans.

Looks like green Friday is upon us.

SEPTEMBER NONFARM PAYROLLS MISS BADLY:
- Jobs added were +29K vs +84K expected
- Unemployment rate increases to 4.2% vs 4.1% expected
The 10-year treasury yield just fell 0.77%, the $SPY is up 0.88%, and $BTC is almost at $87K on this news.
Why are yields falling and risk on assets going up if we are seeing unemployment go up and missing on the expected jobs number?
Well, that means the economy might not be as hot as the Fed thinks and we may not need to hike as aggressively as expected.
Bad news, in the eyes of the macro, might be good news again…
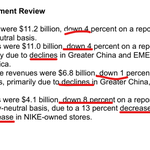
As the one who got absolutely smoked in the first part of the year by $LULU, and I am still paying for that lesson, $NKE certainly wants to take the lead in a bad way.
In a market where AI companies are punished for Capex, despite aggressive growth, a company with so many words like "down" and "decrease" is setting itself up for trouble.
Despite the record lows in price, there is an opportunity cost in parking money with them now.
