

Self-Independent stock research Deep self-built fundamental database Unique alpha generation
Joined April 2025
- Tweets195
- Following180
- Followers54
- Likes103



Who Is Bankrolling the AI Buildout?
The crucial gap is between construction spending, customer cash receipts and debt repayment.
An English look at hyperscalers, neoclouds and SpaceX—with five charts and links to company disclosures.

AI 扩张,谁在垫钱?
比“借了多少钱”更重要的是:项目回款能否赶上建设支出与债务偿付。沿着现金流、债务到期、预付款与债权顺位,拆解大型云、Neocloud 和 SpaceX 的信用差异。
含 5 张图表与公司原始披露链接。

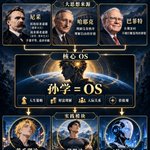
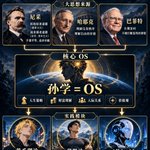
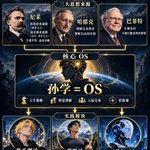
孙学 黄毛 薄肌三大理论的终极理解
本质上是人生系统:孙学是 OS,AI 是执行杠杆。
上层思想来自三个人:
尼采:摆脱奴隶道德,追求卓越。
哈耶克:理解自发秩序,珍视自由。
巴菲特:长期复利,不做打断复利的事。
孙学这个 OS,决定人生策略、财富理解、人际关系和价值观。往下落地成三个模块:
🛡️ 黄毛理论:建立对他人的防御机制,不吃压力。
💪 薄肌论:让身体持续复利,减少健康问题带来的中断。
🤖 All in AI:所有能用 AI 做的事,就用 AI 做。
用 OS 决定方向,用边界保护自己,用健康守住复利,用 AI 放大执行。


我认为侠义的创造价值就是两种:
1: 提供更好的产品
2: 提供更好的服务
于是很多人包括金融从业者困惑与金融投资到底创造了什么价值?
我认为成功的交易者赚到的价值来源于他提供了一种广义的商品:定价的模型
我们的资本市场是通过价格传递信息,信息到了每个市场参与者那里,他们再分析处理,作出对应的商业决策。所以,价格的有效性决定了千千万万参与者的决策有效性,间接影响了社会的总生产效率。
投资者之所以可以赚钱,就是他们自己的投资决策模型背后的定价模型比市场更有效,因为他们赚到了钱,从而影响市场采用新的视野和纬度参与市场定价,反过来加强整个市场的定价效率。
巴菲特之前的市场没有人关注基本面分析 巴菲特的巨大成功将基本面分析变成了市场的主流,从而增强了金融稳定性和市场有效性,巴菲特提供定价模型这种商品,投资回报是他应有的报酬。





无论承认与否,现代社会仍然建立在资本主义市场体系之上。
而自由交换产生的贫富差距,本身就具有正当性。
消费者购买 iPhone,并不是为了让苹果股东成为富人,只是觉得这个产品值得这个价格。当数亿人分别作出同样的选择,巨大的财富自然产生。
市场本质上是一场永不停歇的、无意识的分散式投票。
所以真正的问题从来不是“为什么有人这么富”,而是他的钱是怎么来的。
靠自愿交易、竞争和价值创造获得财富,与靠权力、寻租和特权获得财富,是完全不同的两件事。
市场不负责制造平等,它负责让亿万人的选择决定资源流向。
而价格,就是这些选择产生的信息。
读懂价格和价格之间的相关性变化,就是读懂市场正在告诉你的知识;知识帮助资源配置,这就是投资者能赚到的钱:帮市场实现更快更高效的资源配置。
未来可能更有可能的是XPU TAM 加速变大, AVGO虽然 Compression 但是速度要低于预期,或者可能只是停止Expansion。
目前Broadcom 的 v8i 已经开始生产出货,而 MediaTek 的 v8t 版本反而落后,尽管后者启动得更早。

The Big Four are still raising capex, so I don’t see much evidence yet that the hardware cycle is slowing. I’m mainly tracking $NVDA and $MU here. Many models have not yet included Space X
What’s interesting is that since Q2, software growth has started to pick up as well. $PLTR is still the main name I’m watching on that side.
$APP is another one worth studying. The market seems to be pricing in a pretty sharp slowdown, while the business is still benefiting from AI and growth has actually been accelerating.
So the question for me now is whether we’re starting to move from the infrastructure phase of the AI cycle into the monetization phase.
As long as Big Tech capex keeps going up and software growth is only starting to follow, I don’t think this cycle is close to being over.

$PLTR Q2 13F is not “institutions bought.”
Holder count fell. Reported ownership rose.
That is the tell: a lot of names left the register. A smaller set absorbed the stock.
In the active-manager sample, the net add is dominated by one quiet buyer: Arrowstreet.
They nearly doubled PLTR to 20.5M shares / $2.39B. Not a fly-by. They have been scaling it for several quarters.
This is not a DCF shop waiting for cheap. Arrowstreet is a systematic fundamental-momentum engine. Valuation is only one input. If earnings, revisions, and fundamental trend are violent enough, the model will score an expensive name very high and keep buying.
13F reported holdings which ends June 30th, so which means Arrowstreet made a huge win, but everyone else sold too early.
