




Pinned Tweet
Fundamental equity research in software is challenging due to limited alternative data to support a thesis and complement your research mosaic.
That's changing.
repvue.com/data


Why is average tenure in tech sales 18-24 months?
Well its really hard.
$NET


based.

Five quick SaaS takes:
1) $WCLD is now +72% in the last six months (!!) which is by far the biggest run in % terms since the pandemic.
2) The dispersion is violent- cyber/infra names like $TEAM, $OKTA, $GTLB, $SNOW, $CRWD, $DDOG et al are up 150%+, while companies without clear AI stories yet like $KVYO, $HUBS, $PCOR, $ZM, $TYL etc. are up <20% (some are down!).
3) I don't know how else to put this, but if you find yourself more bullish on SaaS overall than six months ago, something's not right with your process/investment mindset. Aside from a quarter or two of on-trend results, absolutely nothing has changed- if anything, the SaaS bear case has strengthened materially as AI model improvements have continued. You can now effectively one-shot simple SaaS apps. A big question for the future is whether infra is next- I'm skeptical but it isn't impossible to imagine a world in 2-3 years where someone can one-shot, say, Datadog and replicate it based on their current set-up. P(weird) in software has definitely, definitely gone up in the last six months.
4) So far, the most relevant cut is apps vs. infra (cyber counts as infra given how it is packaged/sold). Even Five9 (!!) is up 81% YTD now. In general, pure app vendors have done fine results-wise but have no answer for driving real AI acceleration yet. Their business models need to be re-architected for it (switch to consumption pricing, etc.) and tbh most productivity improvements have driven value for OAI/Ant vs. the app layer, even if the app layer hasn't lost relevance per se. The big test for the next year is whether some app vendors find their legs or not- I don't think the lack of progress so far is dispositive, but in a year that will be a different story.
5) As far as I can tell, while there is dim awareness of this, this mean reversion hasn't impacted sentiment/interest in software in Silicon Valley in the slightest. Interest in anything resembling traditional software remains remarkably low and skepticism remains high, in part because of the pace of model improvements. The valley is anchored to AI optimism and (to them) that naturally leads to software pessimism. The good news for the public/mature names is that there isn't a wave of well-funded competition coming- but it remains nontrivial for SaaS companies without clear AI stories to get funded, even if their public comps have done well in the last six months.

At this point @Benioff it might make sense to rebrand to…
“Salesforce”


Anthropic continues to gain market share among corporate GTM teams
We ran a poll in June -
"Does your company provide a license/budget for AI Tools?"
Yes-Claude was 47%
Yes-ChatGPT was 13%
Yes-CoPilot was 15%
Yes-but pay out of pocket was 25%
ran the same poll this week...
Yes-Claude is 56%
Yes-ChatGPT is 11%
Yes-CoPilot is 16%
Yes-but pay out of pocket is 16%
N=2,252 and counting


In Q1 2026 the take was simple: AI kills SaaS.
Quota-carrying reps didn’t see it that way in the aggregate.
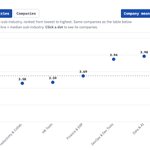
AI impact on the business went 3.76 → 3.75 by Q3.
Flat.
Useless.
But there was a sorting happening underneath...
Under the flat 3.75:
61 companies cleared the ratings bar.
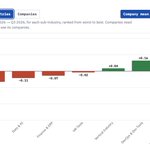
Median company +0.06.
59% improved. 1
3 moves cleared two standard errors;
7 up, 6down.
Panel ratings rose from 4,463 in Q1 to 5,775 in Q3.
More data, same aggregate, wider split.
I think this is just reflection on ‘early adoption’ and how much TAM there actually is - as mass market adoption proliferates
Which is obviously is the same take as investors and operators trying to justify valuations.
But those reading this need hear we live in a bubble.
Normies not there yet.

The top 1% of AI spenders now outspend the bottom 50% combined
They spend an average of $903/month, while the median customer spends just $25
More charts in our Top 100 Consumer AI Apps breakdown: a16z.news/p/top-100-consumer…

I've been a Sigma client for over 2 years - it still has a place in a few of my workflows - but this year Claude has 100% become my defacto for nearly all data analysis and visualization work.
Not much of a surprise then to see this 'AI Impact' decline among the sales reps at Sigma.
Seeing the same at Tableau - and even worse at Alteryx

Q3 in the books - so taking a step back and looking at Company Future Outlook Sentiment among quota carrying sales reps on RepVue from Q4-25 to Q3-26.
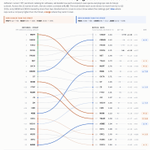
Across every current employee quota-carrying RepVue rating at public companies, outlook went from 3.45 in Q4 2025 to 3.37 in Q3 2026. At ≥30 ratings (N) a quarter, the median company moved −0.09 and 12 of 38 improved. 15 moves clear two standard errors: 5 up, 10 down.
A short thread with the 5 best future outlooks in Q3-26, the 5 worst, and the 5 biggest positive and negative movers.

