Payment infrastructure for global businesses. Receive, move, convert, settle, accept, and spend money across borders in fiat or stablecoins.
stealth
Joined June 2025
- Tweets363
- Following4
- Followers376
- Likes811




stableyard retweeted

over the past 3 months, i’ve spoken to a lot of fintech founders building remittance and payout companies.
and have found these 5 problems in current fintech
1. you get more customers, but now you need more of your own cash sitting with payout partners just to handle their payments.
2. run low on funds with a partner after friday’s bank cut-off, and you could be waiting until monday to top up.
3. you send the money, a bank takes its fee along the way, and now you’re explaining why the recipient got less.
4. a customer asks where their money is. you know it left your account, but you’re still waiting on a partner to confirm it arrived.
5. every partner sends a different report. your team ends up in spreadsheets trying to work out which payment matches which entry.
i feel like stablecoins are particularly useful here.
settlement funds can move 24/7. partners can be funded closer to when payouts happen. fewer intermediary hops can reduce deductions, and an on-chain settlement record gives teams something consistent to reconcile against.
you still need good FX, compliance and reliable local payouts to make the whole thing work.
the more i look at this, the more i think stablecoins reach the masses through the financial apps people already use.
someone sends money home or receives their salary. underneath, their provider uses stablecoins to settle the payment.
they benefit without ever needing to think about the infrastructure.

Remittances are a lifeline for millions of families across the global economy.
but moving that money is still an expensive business.
to give you an idea:
> $728.6B reached low- and middle-income countries in 2025
> sending $200 cost an average of 6.36% globally in Q3 2025
for remittance apps and payout providers, serving that demand means keeping money ready across different markets.
and adding another corridor can mean another account to prefund, another partner to manage and another balance to reconcile.
capital sits waiting while teams deal with banking cut-offs, FX charges and settlement delays.
stablecoin settlement can help these businesses move funds around the clock, replenish balances faster and reduce how much they need to park in advance.
to make that useful, it needs to connect with how businesses collect and pay out today.
with Stableyard, providers can collect through USD and AED accounts, convert between fiat and stablecoins, and make local payouts in supported markets through one integration.
from collecting money to getting it into a recipient’s bank account, there are fewer systems to piece together.
stableyard retweeted

Stableyard launching an AED Business Account for UAE-focused businesses, neobanks and payment platforms.
AED ↔ USDC/USDT, on/off-ramps and local payouts through one integration.
Built for companies that operate in the Gulf and need stablecoin rails.
$𝐑𝐓𝐗 𝐑𝐞𝐦𝐢𝐭𝐭𝐢𝐱 stays on the receiving side after the crypto is sent.
Crypto leaves the sender.
Local fiat lands in the recipient’s existing bank account.
No new business account, no extra wallet and no stablecoin holding required for the person receiving to use the funds.
@remittix
#RTX #AED
Your business runs on the Gulf🇦🇪.
Your payments should too.
Introducing the Stableyard AED Business Account.
For businesses, neobanks, remittance apps, and payment platforms serving the UAE.
→ AED ↔️ USDC / USDT
→ seamless on/off-ramps
→ local payouts
From UAE collections to global payments, connect your business and your users to the dirham through one integration.

stableyard retweeted
🚨 Pay with stablecoins. No Visa. No Mastercard.
We built a true stablecoin account that works on the POS terminals merchants already have.
Tap a card at a POS running our SDK and the payment settles in seconds. It goes stablecoin to stablecoin, without touching a card network.
What changes for the merchant:
→ better economics, with less card-network fees in the middle
→ same-day settlement
→ global coverage
→ they get paid in stablecoins or supported local fiat, whichever they choose
What changes for the customer: they pay straight from their stablecoin balance, and the tap feels exactly the same.
Underneath, @stableyardfi handles the whole flow, from account to acceptance to settlement.
For fintechs, wallets and banks, this is infra to offer stablecoin accounts people can actually spend.
I have shown in the demo how it works
If you're building in stablecoin fintech, DMs are open
stableyard retweeted
biggest fintech insights i found at token2049:
> a lot of stablecoin fintechs are building the same thing with more or less the same partners. if one shared provider goes down, everyone relying on it feels it
> doubts about stablecoin adoption feel like yesterday’s conversation. stablecoins are becoming boring, which might be the clearest sign they’re going mainstream
> everyone was selling to everyone. more integrations are opening up, but who handles the local payout still matters
> showed @stableyardfi merchant acceptance demo to @DinersClub and @BVNKFinance and got a really good response
> met a few partners we’re onboarding this coming week for business accounts and other business offerings
> relevant inbound for @stableyardfi and @dopepayme, with potential integrations and partnerships to work through
> met folks from @Ripple , @circle and @NiumGlobal at their offices,
and the @JamieZammitt from bvnk team. also caught up with friends @0xAishwary from @0xPolygon , @_ryandesouza from @arbitrum and @AhaanRaizada from @base .
great catching up with old friends and meeting new faces.
came back with stronger opinions on which payment products people will keep using, and how much will change as the industry matures, regulations develop and banks get more involved. glad i made the trip.

stableyard retweeted
we’re have 3 product categories at @stableyardfi
1. Accounts & Money Movement
> Global Business Accounts
> Virtual Accounts
> Universal Payment Account
> White-label Accounts
> Stablecoin On/Off-Ramps
> Local Payouts
> Cross-chain Transfers
2. Payments & Settlement
> Online & In-app Payments
> Merchant acceptance
> Tap-to-Pay & POS
> Fiat & Stablecoin Settlement
> Currency Conversion
> Vaults & Spending Policies
> Bank, PSP & Acquirer Network
3. Developer Tools
APIs & SDKs
Multichain Deposit Widget
White-label Integrations
KYC/KYB & Webhooks
from day one, our vision has been to connect accounts, payments and settlement
so founders can build global financial products without building the infrastructure from scratch.

stableyard retweeted
stablecoins could take over finance without replacing the companies running it.
> are we watching fintech’s early days repeat?
> who wins when everyone can use the same rails?
> does cheaper settlement mean cheaper payments?
stableyard retweeted
Stableyard is coming to token2049 singapore 🇸🇬
(ft @0xavinash & @Rjparab)
if you’re building in stablecoins, fintech, settlement, defi or payments, let’s meet.
would love to exchange cool ideas & market insights.
also: shill us the side events we absolutely shouldn’t miss
dms open.


stableyard retweeted

We have integrated @stableyardfi into MoneyMoves.
Stableyard provides stablecoin payment infrastructure that makes it easier to move stablecoins across different chains and payment rails.
For MoneyMoves, this means we can support more assets from more chains and give users more ways to receive and move crypto directly within MoneyMoves.
It also gives us a stronger foundation as we expand our B2B and B2B2C infrastructure.
More assets. More chains. More ways to move money.

stableyard retweeted
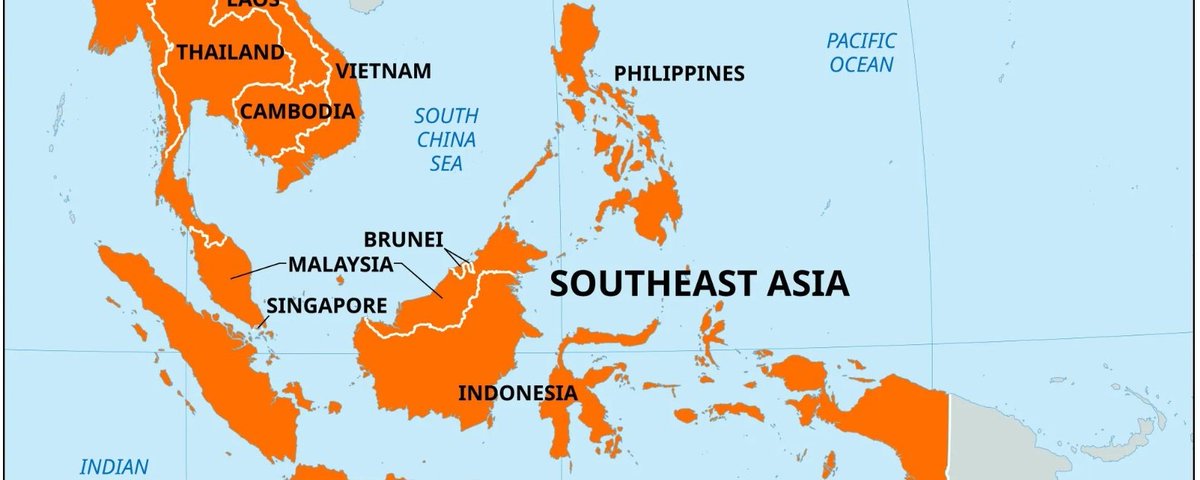
SEA trades $4 trillion (approx.) in goods every year.
(🇸🇬 🇮🇩 🇵🇭 🇻🇳 🇹🇭 🇲🇾 )
And that is before you count
Payroll, remittances, vendor payments
marketplace settlements.
But the money behind all this trade still moves badly.
stableyard retweeted
Looking to connect with people from:
@FireblocksHQ, @DinersClub , @blackbird and a few other teams working across wallets, cards and merchant payments.
Ideally looking to connect with someone on product partnerships.
We’re working on a few new distribution and payment opportunities at @stableyardfi and would love to explore where the right technology or product partners can fit in.
stableyard retweeted

The hardest part of stablecoin payments is no longer moving dollars onchain. It is making them usable in the local systems people already rely on to get paid, pay suppliers, and run a business.
The last mile is where the real infrastructure work is.


stableyard retweeted
if you're in Delhi on 22nd aug
come say hi to me at Road to Devcon: Delhi!
will be sharing my insights on CBDCs vs. DeFi.
See you on the 22nd!

hosting Road to Devcon: Delhi - on 22nd Aug (Saturday)
2 panels. 6 stacked builders.
CBDCs vs. DeFi Panel
@0xAishwary, @0xavinash, @goelrishabh
Information Markets vs. Traditional Media Panel
@rachit, @manangouhari, @sakshimiishra
come w your hardest questions. i'm confident you'll get your answer.
stableyard retweeted
90% of stablecoin payment companies will die soon
cuz they think payments = moving money from A to B and giving tx hash.
it's def not otherwise, your nearby cafe would be taking crypto payments
real-world payments are about who
> creates wallet
>approves what size payout
>rotates keys
>updates policy
> exception handling
traditional finance has all of this. not because banks love bureaucracy, cuz you can't run real money without it.
EY found the top adoption blockers are accounting and operational complexity. not fees. not speed.
meanwhile the whole industry keeps shipping endpoints. more cards. more wallets.
tempo is one of the few who get it
we've also observed the same thing while talking to merchants
that'why we are trying to build these things @stableyardfi. controls, identity, exceptions across every chain your money touches.
if you're interested in this boring yet crucial part of payments, stay tuned. exciting things are coming soon.


stableyard retweeted
Robinhood Chain is live on Stableyard.
Accept deposits into the @RobinhoodCrypto ecosystem from multiple chains
One tap for users. One integration for builders.
Go: widget.stableyard.fi/
stableyard retweeted
Been working in payments for the last 1.5 years,
and honestly, I've been seeing the same pattern Claudia talks about here.
A lot of crypto builders forget that some of the biggest crypto users live in regions where cards never really became the default
and these are also some of the biggest remittance corridors in the world (Asia, Africa, Latin America)
People are already receiving global money in USDT or USD accounts, but they're not spending it directly.
They have to convert it into local fiat because their payment system have evolved differently.
>Because a lot of merchants don't have card terminals everywhere.
>Because most of the commerce runs on QR rails.
Stablecoins have already proven the global money movement, but the last mile is still broken.
Most merchants don't care whether the payment came from a card, bank account, or stablecoin.
They care about one thing:
"Did I receive my money instantly?"
The real opportunity is to make stablecoins interoperable with whatever local payment system already exists, whether that's QR, cards, bank transfers, or something else.
That's what we are building @stableyardfi