Elvi$ (@robelvis101) header
Elvi$ (@robelvis101) profile picture

Jesus is king, ‘’HEIS’’. NGX | US filings. Clean cards. No noise. I follow the Filings, not the Narrative. DYOR.

Nigeria | US Earnings
Joined July 2024
Photo by Elvi$ (@robelvis101)Photo by Elvi$ (@robelvis101)Photo by Elvi$ (@robelvis101)Photo by Elvi$ (@robelvis101)Photo by Elvi$ (@robelvis101)Photo by Elvi$ (@robelvis101)Photo by Elvi$ (@robelvis101)Photo by Elvi$ (@robelvis101)Photo by Elvi$ (@robelvis101)Photo by Elvi$ (@robelvis101)
Replying to @robotaxitracker
+92.4% in ONE expansion. 31 → 59 sq miles. Nearly doubled Miami overnight. Same playbook as Austin: Launch small → Learn fast → Double the map. Austin hit 438K miles/week. Miami is on the same curve. Miami Beach is next. Berlin is building 1M Cybercabs/year to fill it. $TSLA isn't testing. It's scaling. xitter.cf/robelvis101/status/211…
$TSLA Q3'26: TRIPLE BEAT 🟢 Revenue $28.05B vs $27.88B est BEAT Adj EPS $0.48 vs $0.43 est BEAT Adj EBITDA $3.90B vs $3.71B est BEAT GM 19.6% +160 bps YoY $TSLA
1
341
Bought at $115 and $126. I'm holding regardless. But this disclaimer right after the pump post is crazy 😂 $ORCL
Replying to @Oracle
Forward-Looking Statements Disclaimer Statements in this post relating to Oracle’s future plans, expectations, beliefs, and intentions are “forward-looking statements” and are subject to material risks and uncertainties. Many factors could affect Oracle’s current expectations and actual results, and could cause actual results to differ materially. A discussion of such factors and other risks that affect Oracle’s business is contained in Oracle’s Securities and Exchange Commission (SEC) filings, including Oracle’s most recent reports on Form 10-K and Form 10-Q under the heading “Risk Factors.” These filings are available on the SEC’s website or on Oracle’s website at oracle.com/investor. All information in this post is current as of November 20, 2026 and Oracle undertakes no duty to update any statement in light of new information or future events.
61
Nov 14: I called it. Failed at MA28 $84,904 -> washed to $72,842. Then lost $72k. Then below $64k. I said Next: $60k? Today: BTC LOST $60k. Now $59,520. $68k lost. $65k lost. $60k lost. $BTC #Bitcoin 👇
Update Nov 14: Called it. Failed at MA28 $84,904 -> washed to $72,842 target. Then lost $72k. Now below $64k. $68k lost. $65k lost. Next: $60k? Below EMA7 + MA7. Monthly squeeze still live. $BTC #Bitcoin
1
1
116
Still below EMA7 + MA7. Monthly squeeze still live. $60k is now resistance, not support. Reclaim $60k = bounce to $62.2k. Hold below $60k = $57.8k next, then $53.7k.
1
25
I don't guess tops and bottoms. I follow levels. Nov 14 price: $64,634 Nov 20 price: $59,520 Levels don't lie. People do.
11
$BJ just beat on EVERYTHING — and still fell -7%. EPS: $1.73 vs $1.26 expected Revenue: $6.28B vs $5.97B expected Comp Sales ex-gas: +4.1% vs 2.9% expected Guidance: RAISED to $5.10-$5.30 from $4.60-$4.80 So why is the stock down? Because $240M of that profit wasn't from selling more stuff. It was a one-time credit-card settlement. Market didn't buy the headline. It read the fine print. 👇
1
47
Strip out the settlement and the real story is still strong: Membership Fee: $138.4M, +9.5% YoY Net Income: $219.5M, +44.4% YoY Comp sales accelerated from +3.1% to +4.1% BJ's is compounding members like Costco. That doesn't disappear because of one settlement.
1
22
This is why $BJ is a trader's trap and an investor's opportunity. Traders see -7% and panic on the settlement. Investors see raised guidance + record membership + accelerating comps. Which side are you on?
9
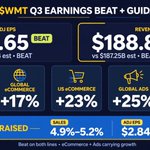
$WMT Q3: Beat + Raise EPS $0.65 vs $0.64 Revenue $188.84B vs $187.25B US eCommerce +23% Global Ads +25% Membership +17% Raised FY guidance too. Stores are slowing. Digital is carrying Walmart now.
1
95
The beat was NOT from stores. US Comp Sales: +2.9% US eCommerce: +23% Global eCommerce: +17% eCommerce + Ads + Membership = the new growth engine.
1
59
Why stock still down? Valuation. $WMT trades at ∼46x earnings. At that multiple, a $0.01 beat isn't enough. Market wanted a blowout. Fundamentals = strong. Price = expensive.
40
$BABA Q2 FY27 is out — and it's a clean beat. Revenue RMB 271.5B, +10% YoY Adjusted EBITA RMB 32.6B, +260% YoY Net Profit RMB 64.5B, vs 23.5B expected Cloud is the story 👇
1
1
1,725
And the bottom line confirms it: Net profit RMB 64.5B vs RMB 20.99B last year, vs RMB 23.52B expected. That's a 3x YoY jump and a massive beat. The core is working AND the investments are paying off.
1
45
My read: $BABA is turning from an e-commerce story into an AI / Cloud story. If Cloud keeps compounding like this, the re-rating comes from Cloud, not Taobao. What's your read — is Cloud enough to carry $BABA?
82
$TSLA Q3'26: TRIPLE BEAT 🟢 Revenue $28.05B vs $27.88B est BEAT Adj EPS $0.48 vs $0.43 est BEAT Adj EBITDA $3.90B vs $3.71B est BEAT GM 19.6% +160 bps YoY $TSLA
1
1
1,065
Everyone is focused on deliveries down -2%. Look at the real story: Storage 13.7 GWh +10% YoY FSD Subs 1.74M +67% YoY FSD is becoming recurring revenue. Storage is scaling. That's the future margin. $TSLA
1
37
And the bottom half is why you hold: Robotaxi Cybercab rides started Sept 3 Austin Optimus production in Fremont Megafactory Texas 50 GWh planned Deliveries are the past. Robotaxi + Optimus + Energy are the future. That's the $TSLA thesis.
57
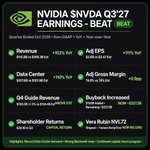
$NVDA Q3'27 EARNINGS - MASSIVE BEAT 🟢 Revenue $115.8B vs $109.3B est EPS $2.68 vs $2.47 est Data Center $107.6B vs $101.9B est Q4 Guide $130B vs $124.4B est AI is NOT slowing down. $NVDA 👇
1
1
1,422
Bears said AI bubble. $NVDA just printed +103% revenue growth and raised guidance. This is why you hold the leader. $NVDA $TSM $AAPL
1
77
This is the number that ends the debate. Frontier labs = only 15% of Data Center revenue. 85% is from cloud, enterprise, sovereign AI, and industrial customers. It's NOT 2-3 labs propping up NVDA. It's the entire world rebuilding on NVDA. Plus cloud backlog just jumped $500B in 3 months to $2.5T. Demand isn't concentrated. Demand isn't slowing. Demand is everywhere. $NVDA isn't a bubble. It's the infrastructure. $AAPL $TSM
23