

Get AI-powered stock analysis, DCF calculators, earnings calendars, custom KPIs, portfolio insights, and 30+ years of financials - all in beautiful charts.
Joined May 2025
- Tweets1.2K
- Following1
- Followers37.9K
- Likes26



Barclays estimates a free consumer agent costs 10x the free ChatGPT tier to run.
Winning means being willing to burn something like $40B a year in extra compute to give the product away.
That's why Meta is the favorite, and it's not about whose agent is smarter. Meta and Google are the only two with ad businesses printing enough cash to subsidize a free tier indefinitely. Apple could afford it but won't spend it. OpenAI basically has to charge.
The winners will be whoever can afford to lose the most money the longest.
$META $GOOG

Texas Roadhouse is selling more food than ever.
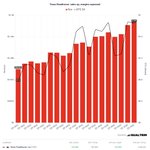
Q2 revenue up 11% to $1.68B. Comps up 6.2% on real traffic growth. Average weekly sales over $175K, a record.
EPS: $1.85. Down from last year.
Beef inflation ran 7% and ate the entire gain. Restaurant margin fell to 16.4%.
The chart says it all: the bars go up, the line is flat for over a year.


Agentic commerce is a bloodbath for the middlemen
Everyone's hyped about AI that buys stuff for you. But think about what gets skipped. No Google ad gets clicked. No Pinterest board gets scrolled. Nobody opens Booking com. The agent just buys the thing.
YTD:
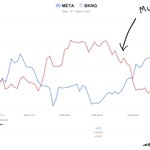
The Trade Desk -66%
Chewy -44%
Pinterest -31%
Booking -23%

Everyone's staring at Meta's $140B capex bill. Look at the cash engine underneath.
Q2 free cash flow collapsed 91% to $784M. But that same quarter revenue grew 28% to $60.8B. The business isn't broken, the cash is just being reinvested.
Off trough FCF/share of $16.08, at 30% growth on a 40x multiple:
2027: $944/share
2028: $1,190/share
2029: $1,500/share
$META


Bill Ackman estimates Netflix can compound EPS by 19% annually.
He's not alone.
These are the projections from top firms:
1. Pershing Square: 19% CAGR
2. JPMorgan: 24% CAGR
3. Evercore: 20% CAGR
4. Jefferies: 20% CAGR
Assign a 25x multiple, and it returns 22% per year.
$NFLX


