

Autonomous mortgage infrastructure empowering fintechs, brokers, and lenders to make 102bps+ more per loan
Palo Alto, CA
Joined March 2019
- Tweets92
- Following29
- Followers533
- Likes141





Originators never see the real cost of capital.
Their rate sheet has already passed through aggregators, correspondent channels, and trading desks, each adding markup along the way.
Originators and borrowers pay for every layer.
1
5
233
Pylon cuts out the middlemen so originators can take back 75-200bps.
Learn how Pylon fixes the broken capital model. pylonlending.com/resources/b…

3
152


Brokers often think of Pylon as a wholesaler with smarter tech and tighter margins.
But wholesalers are intermediaries.
Pylon cuts out the middlemen and lets you broker directly to Wall Street.
We give brokers access to capital sourced directly from institutional investors.
1
5
194
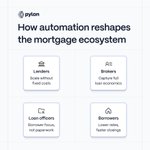
And instead of marking up the cost of human-driven mortgage manufacturing, our mortgage rails automate mortgages end to end.
Faster, cheaper, and better.
That's how we cut out the middlemen and give brokers access to rates that are 75–200bps better.
pylonlending.com/resources/b…

2
112


Most loans are structured by habit. 80% LTV ➡️ move on. But that’s not how pricing works.
Mortgage is a dynamic market shaped by investor demand that changes daily.
This creates inefficiencies. It also creates opportunities. 🧵
1
8
218
Our system runs every eligible scenario across lenders, pricing grids, and constraints.
It surfaces where demand is mispriced and finds pockets where one takeout investor will pay more for the exact same loan.
Then it structures the loan to capture that value.
1
4
178
Sometimes this means a better rate for the same cash to close. Sometimes it’s the same rate with less cash out of pocket.
Pylon turns loan structuring into market making.
Learn more: pylonlending.com/decisioning…

5
134
The future of mortgage infrastructure gets decided in the next 6-12 months. Join us.
Pylon careers: pylonlending.com/careers/
2
116
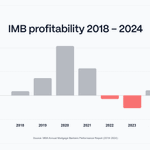
As mortgage tech advances, efficiency is supposed to go up. Instead, it’s gone down.
Point solutions added vendors to manage. APIs led to closed ecosystems. AI got bolted onto the old assembly line.
The tools got better, the architecture stayed the same, and the price went up.


4
7
203
The White House signed an executive order on mortgage credit last Friday. Here are some highlights for mortgage lenders and operators. 🧵
1
6
189
QM and supervisory reform: broader safe harbors for portfolio loans and a correction-first approach to good-faith compliance errors. These provisions are framed around community banks, though the MBA has argued they should extend to IMBs and brokers.
1
2
128
Most provisions will require their own rulemaking or guidance process. First concrete deliverable: a 120-day FHFA report on housing finance efficiency, due July 11.
We break down the full EO here: pylonlending.com/resources/m…

4
129
Mortgage innovations follow an unfortunate pattern: arrive with promise, get absorbed by the assembly line, and fail to lower costs.
Digital applications, point solutions, and API- and AI-driven tools have each delivered real improvements within a narrow domain. But…👇
1
4
147
Each adds complexity: more systems to connect, more handoffs to manage, and more humans to coordinate it all.
We look at the four recent waves of mortgage innovation and why none of them actually made mortgages cheaper: pylonlending.com/resources/m…

3
123