


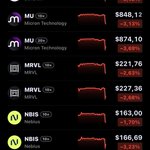




Revolut might just lost 40% of their valuation


We might see some more pain in the market, but I genuinely believe we won’t see some of these stocks at these prices again for at least 2–3 years


I think the market is seriously underestimating how much memory AI will require over the next decade.
$MU, $SNDK, Samsung and SK Hynix have been selling off following China’s CXMT announcement of its new 4F² DRAM architecture. Investors are worried that China could eventually flood the memory market with cheap supply, putting pressure on prices and margins.
And honestly, that’s a legitimate concern. Elon Musk recently pointed out that once China figures out how to manufacture a product efficiently, its ability to scale is often greater than the rest of the world combined. We’ve already seen this happen with solar panels, lithium batteries and electric vehicles. There’s no reason to assume memory will be completely different.
But here’s where I disagree with the market’s reaction. CXMT announcing a new architecture and actually manufacturing it at scale with competitive yields, reliability and costs are two very different things. Its planned DDR5 server memory is impressive, but we still don’t know how competitive the final product will be. And more importantly, DDR5 and HBM are not interchangeable. Advanced HBM requires complex stacking, packaging, thermal management and close collaboration with customers like NVIDIA.
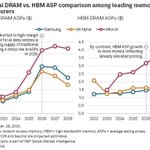
What I think investors are overlooking is how fundamentally AI is changing memory demand. We’re no longer talking about just smartphones, PCs and traditional servers. AI training requires enormous amounts of HBM, while inference increasingly depends on memory capacity and bandwidth to handle larger models, longer context windows and more concurrent requests. As AI agents, robotics and autonomous systems become more capable, the amount of data that needs to be stored and accessed could increase dramatically.
And this is what makes the current situation so interesting. Historically, memory has been an extremely cyclical industry. Manufacturers increase capacity, supply eventually catches up with demand, prices collapse and the cycle repeats. I don’t think that cycle has disappeared, but I do think AI could make this expansion different from previous ones.
China is absolutely going to become a much bigger competitor. CXMT already accounts for roughly 9.5% of global DRAM revenue according to TrendForce, and that number could continue growing. Ignoring that would be a mistake. But assuming that increased Chinese production automatically means the end of the memory bull market is equally questionable.
The biggest risk to my thesis isn’t China producing more memory. It’s supply growing faster than demand and eventually destroying pricing power. That’s what I’m watching closely.
Because at the end of the day, the question isn’t whether China can scale memory manufacturing. We already know it can.
The real question is whether the world can manufacture memory fast enough to keep up with what AI is becoming.
I’m still extremely bullish on memory over the next decade.


