

Asymmetric Alpha | Deep Tech, Critical Minerals, Nuclear Tracking retail momentum & hottest tickers on X
Joined March 2026
- Tweets359
- Following67
- Followers522
- Likes10.8K





Pinned Tweet
$AMPG is the best asymmetric small-cap setup in the market.
AmpliTech is, at its core, a pure-play American hardware engine for the fastest growing technology sectors today.
After months of research, this article explains my complete thesis.

Olyth retweeted

We're giving away a Hogwarts Legacy custom wrapped NVIDIA GeForce RTX 5090 to celebrate its official release with DLSS 5 🪄
To enter:
🟢 Share this post
🟢 Comment #RTXON
Terms and Conditions: nvidia.com/en-us/geforce/con…

Olyth retweeted

I bought today more $AMPG at $2.15.
Here is why:
- Market cap: $64.77M
- Cash: $33M
- Backlog: $52M and increasing.
- 2026 revenue estimate: ~50M
- Only publicly traded American O-RAN radio manufacturer
- $SPCX and $NOK investing to 5G and AI-RAN
- Trading 1x NTM sales.
🔥🚀

Today’s $AMPG press release has some interesting information:
- Full $52M million backlog is fulfilled during the remainder of fiscal 2026 and fiscal 2027.
- Existing cash resources are sufficient to fund planned operations through the end of fiscal 2027.
- AmpliTech also announced that it has received all remaining technical documentation and design deliverables required under its amended asset purchase agreement with Titan Crest.
- AmpliTech is now focused on translating the intellectual property acquired and developed independently over the past two years into additional revenue in 2026 and 2027 through repeat and new orders from TELUS and other major mobile network operators (MNOs).
- AmpliTech has also submitted responses to several large requests for proposals (RFPs).
Incredibly bullish for AmpliTech! 🔥🚀
Olyth retweeted
AI-RAN is in the news again and I see this as a bullish announcement for the whole ecosystem and $AMPG.
$NVDA and $NOK are turning telecom networks into distributed intelligence platforms using AI-RAN and Nokia O-RAN compliant anyRAN software.
At GTC Berlin today they announced:
- T-Mobile completed the first AI-RAN call on a commercial network
- BT, Deutsche Telekom, Elisa and Orange are moving to live trials
- Nearly 20 operators have now announced AI-RAN collaborations with Nokia and NVIDIA
- Commercial services are targeted for 2027
AI-RAN runs on GPUs, but every cell site still needs radios and AmpliTech is well positioned as an American O-RAN hardware vendor to support these deployments.
We have already seen large purchase orders coming in from Asia over the past few months.
Remember that AmpliTech works on the same project with Nokia in Indonesia, and this is where the orders are coming from.
AI-RAN just moved from the lab to live networks and AmpliTech is one of the few small caps directly exposed to it.
nvidianews.nvidia.com/news/n…

Olyth retweeted
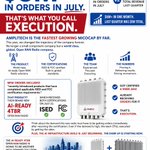
BREAKING: $AMPG just received the biggest purchase order in company history, after already booking $17M in orders in Q3.
That brings total orders to nearly $40M over the past 3 months.
Market cap is only ~$70M, with zero debt & $30M in cash.
R/R looks extremely attractive! 🔥

$AMPG: AmpliTech just landed a record $21.7M purchase order, the largest in company history.
It's a follow-on order from an Asian mobile operator under its $78M 5G O-RAN LOI.
Cumulative orders under that program are now about $34M, nearly 44% of the LOI, and total backlog is above a record $51M.

Olyth retweeted

About damn time $AMPG
Record order volume of 21 million ✅
web.quartr.com/link/pressrel…

Olyth retweeted
BREAKING: $AMPG HAS RECEIVED $17M WORTH OF ORDERS DURING THE THIRD QUARTER OF 2026!
I think everyone should pay more attention to what AmpliTech is currently doing right now. This $80M market cap company faced customer-side delays during the first half of 2026, which resulted in them pulling guidance, but they have just posted more orders than anyone was originally estimating and are not only on track to meet the original guidance, but to exceed it significantly.
What’s best is that they are seeing continuous orders landing from their customers:
“We are pleased with our third-quarter order performance, which reflects continued purchasing activity from established customer programs and growing commercial experience with our O-RAN technology and product portfolios across our divisions.”
- Fawad Maqbool, CEO of AmpliTech
They have now received over $30M worth of orders this year and have around $30M of cash. Market cap is $80M.
I am personally a buyer at these prices🔥🚀
globenewswire.com/news-relea…

Olyth retweeted

Después de una jornada de trabajo, tuvimos el gusto de recibir en nuestra casa al secretario de Estado de los Estados Unidos, Marco Rubio, y a su esposa, Jeanette Rubio, para compartir una cena en familia.
Un encuentro cercano y fraterno que fortalece no solo la alianza estratégica entre nuestras naciones, sino también los lazos de amistad que nos unen.
Gracias, @secrubio, por su visita y por permitirnos compartir lo mejor de nuestra tierra: nuestra gastronomía, nuestra alegría y el inigualable calor humano de Barranquilla.
¡Esta siempre será su casa!
¡Firme por la patria!
¡Viva Cristo Rey!
(A.D.L.E.) 🇨🇴🐅


Olyth retweeted

This is my absolute favorite CNBC moment of all time. He never gave a shit even when it wasn’t popular…
Absolute legend! Happy retirement .@RickSantelli 🐐


Olyth retweeted

$AMPG won 3 design wins recently.
The end customer appears to be the Government of Canada. 🇨🇦
Amplitech would be selling to Farcast.
Farcast to $TSAT.
And TSAT is funded by the Government of Canada to deploy Lightspeed.
Now let me prove each line, bottom-up, because three of the four links are documented and one is my deduction.
Link one, TSAT and Canada: documented.
Ottawa put $1.44 BILLION into Telesat Lightspeed ($790M loan + $650M preferred equity + warrants), later a $2.14B loan, plus $400M from Quebec and $109M from Ontario.
A 198-satellite sovereign LEO constellation.
Built on public money.
Link two, Canada as CUSTOMER, not just funder.
Separate from the loans, the Government of Canada signed a $600 MILLION agreement to BUY Lightspeed capacity, which it resells at subsidized rates to ISPs serving rural and Indigenous communities.
Telesat's own website: governments purchase the capacity pool.
It's already live: Northwestel signed a multi-year contract in April drawing from that exact government pool, with "Arctic sovereignty" in the press release.
Ottawa isn't just financing the network.
Ottawa is anchoring the demand.
Link three, Farcast and TSAT: documented.
Telesat invested $5M in Farcast, took a board seat, and signed them to deliver the enterprise flat-panel terminal for Lightspeed, "ready for volume production," terminals available 2027. The ramp is now.
Link four, AMPG and Farcast: my deduction, at roughly 60%.
Three reasons, work shown.
The architecture demands it: Farcast's differentiation is a full-duplex single-aperture antenna, transmit and receive through the SAME aperture.
That isolation problem has no catalog chips.
Compare AmpliTech's PR: "not off-the-shelf components... demanding RF challenges".
The wording fits: the PR stresses "cost objectives".
Farcast's entire pitch is SWaP-C, where C is Cost.
The PR says production comes "as the customer's program advances".
Farcast's ramp is 2026-2027, on Telesat's clock.
The fingerprints: within days, two people from Farcast liked the AGMDC president's LinkedIn post about the win. The startup's RF & antenna team lead and a senior production engineer. Not sales people. The one who selects the chips and the one who builds with them.
Could I be wrong?
Absolutely.
The strongest alternative is a disciplined customer whose engineers are forbidden from liking anything.
Silence is also a strategy.
That's why it's 60%, not 95%.
Why it matters if the thread holds: terminals are the VOLUME game of satcom.
Constellations need tens of thousands.
Three chip sockets per terminal, designed in, qualified, sticky.
Swapping a qualified MMIC mid-ramp costs the one thing a startup on Telesat's clock doesn't have: time.
Four links.
Three documented.
From Ottawa's treasury to a chip bench in Plano, Texas.
If the thread holds.
Not financial advice. I'm long $AMPG. DYOR. 📡

$TSAT: Telesat LEO today announced that it has signed a $2.3 billion Telesat Lightspeed services contract with Canada’s Defence Investment Agency (DIA) to deliver secure Military Ka-band (Mil-Ka) Arctic connectivity to the Canadian Armed Forces (CAF) under the Enhanced Satellite Communications Project – Polar (ESCP-P) program.
The contract also includes two five-year option periods valued at approximately $200 million each, bringing the total contract value to $2.7 billion. All amounts are in Canadian dollars unless otherwise noted.

Olyth retweeted
$AMPG
TLDR: We are in a time where true quality matters
I think we are just at the beginning
We are just now seeing a company moving from research and development only beginning to go into commercialization.
Was the stock ahead of itself in the past? Yes
Is it ahead of itself now? Absolutely not
The same people who sold in order to save on a 10% or 30% loss will be the same people who will sell way too early when they truly start to scale at 50% or 70% gains 🥱
Slowly becoming all too familiar with companies who have superior products and the market finally catches up to them.
This is now the Case for $AMPG: Not because they have products that everyone else has & can mass produce; but because they have the best in class solutions, that do that little bit more that companies are being forced to choose based on customization capabilities and added value.
All that to say, happy investor, let management execute, let’s see where we are in a year 🙌🏽


Olyth retweeted
$AMPG I am getting excited again. This is amazing news.
The reason why stock tanked 48% is now largely resolved.
Algos are still sleeping because this PR landed middle of the trading day.

Did $AMPG just completly reverse the damage from last earnings?
AmpliTech pulled the $50M FY26 number and said volume shipments on one international 5G program had slipped.
Stock price tanked ont this news.
Bureaucracy/deployment timing in Asia.
Not cancelled demand.
The large overseas LOI was still active.
Today they announced over $7.3M in follow-on O-RAN 5G orders for an Asian MNO under that previously announced LOI, after radios were already deployed at end-customer sites.
They also noted separate North America follow-ons.
Delayed Asian account, now reordering.
Validation of the “timing, not cancellation” story.
Demand is there and the company is still following through.

Olyth retweeted
$AMPG $13.3M orders have landed during this quarter. That is almost double to previous quarter.
These are all purchase orders, not LOIs.

Hello, everyone.
How is everyone doing?
Market sold $AMPG because they pulled guidance.
They pulled guidance because they were struggling with Asian bureaucracy.
Asian bureaucracy is solved.
$7,300,000 just landed.
Add the $6,000,000 from the North American (Telus).
They're back on track.
I'm long $AMPG.
This is not financial advice.
Do your own research.

Did $AMPG just completly reverse the damage from last earnings?
AmpliTech pulled the $50M FY26 number and said volume shipments on one international 5G program had slipped.
Stock price tanked ont this news.
Bureaucracy/deployment timing in Asia.
Not cancelled demand.
The large overseas LOI was still active.
Today they announced over $7.3M in follow-on O-RAN 5G orders for an Asian MNO under that previously announced LOI, after radios were already deployed at end-customer sites.
They also noted separate North America follow-ons.
Delayed Asian account, now reordering.
Validation of the “timing, not cancellation” story.
Demand is there and the company is still following through.
Olyth retweeted
TODAY: $AMPG's MMIC design center just won THREE competitive design slots in an advanced phased-array satellite communications platform.
All three components.
Against competition.
Selected on performance.
The CEO just bought 12,247 shares in the open market.
Days after an earnings report where the $50M full-year guide came off the table, reset to a softer floor of "above FY25 revenue".
Fawad's insider record over five years: four buys, zero sells. He just bought the post-earnings dip with his own money.
Why pull a hard number?
My read, framed as the question it is: because the contract picture is genuinely uncertain, in BOTH directions.
The $78M LOI's timing is unknowable right now (supplier delays, customer schedules).
But remember what else is on the table: new MNO deals signaled to go straight to POs, a freshly FCC and ISED certified AI-Ready 4T8R radio cleared for commercial North America, brand-new AI-RAN Alliance membership, $6M+ in follow-on orders in July alone.
You don't personally buy the dip if you think the uncertainty resolves badly.
That's my inference.
Now, today's news.
A customer competitively sourced three newly developed custom GaAs MMIC components for its phased-array satcom system.
AmpliTech's AGMDC division designed against demanding RF specs and cost targets, and won all three sockets.
Orders received, and AGMDC is now established as the supplier of these components for the platform.
Why design wins matter more than their initial size: in RF, a design win means your chip is designed INTO the platform.
If the program scales, those sockets are yours for the production run. It's how small RF houses end up inside every unit of somebody else's product.
Sticky.
Recurring.
High-IP.
And phased arrays are the beating heart of modern satcom: LEO terminals, gateways, defense.
The space boom runs on exactly this class of silicon.
In Fawad's words, these are "not off-the-shelf components".
The customer brought hard RF problems; AmpliTech's engineers solved them and got picked.
Honest framing: the customer is unnamed, no dollar figure was disclosed, and additional production depends on customer demand, program schedules and future purchase orders. A door opened on merit, not a backlog number. And it's the satcom division, not the ORAN line. Which is exactly the point after a rough Q2: this platform has more than one engine.
The CEO bought the uncertainty.
The design center keeps winning sockets.
The ORAN story sets the ceiling.
Not financial advice. I'm long $AMPG. DYOR. 📡

BREAKING: $AMPG CEO BUYS SHARES AFTER QUIET PERIOD ENDS!
Fawad bought the dip yesterday. Own money, open market, first day the window opened. I think it was the right call.
The ER was bad and the selloff is justified, but it's overblown.
He's buying below what shareholders paid in the rights offering a month ago.
I am with Fawad here. Let's go 🔥🚀
Olyth retweeted
BREAKING: $AMPG SUBSIDIARY AGMDC WINS THREE COMPETITIVE DESIGN WINS FOR A PHASED-ARRAY SATCOM PLATFORM
AmpliTech today announced that its AmpliTech Group Microwave Design Center division has received orders for three newly developed custom Gallium Arsenide (GaAs) components for use in an advanced phased-array satellite communications system.
In summary:
✅️ All three were competitively sourced. AmpliTech won on performance against the customer’s technical requirements.
✅️ The parts go into an advanced phased-array satellite communications system.
✅️ AGMDC is now established as the supplier of these components for the customer’s platform.
✅️ Future production depends on customer demand, program schedules, and purchase orders.
CEO Fawad Maqbool commented:
“What makes this strategically important for AmpliTech is that these are not off-the-shelf components. Our engineers were asked to solve specific, demanding RF challenges, and their designs were selected.
We believe wins of this nature can deepen our participation in next-generation satellite platforms, strengthen long-term customer relationships, and create opportunities for additional recurring production as customer programs progress.”
Winning all three sockets in a competitive process tells me that their design team is real. Design wins are usually sticky. Once your custom chip is qualified into a platform, you usually stay for the life of the program.
Phased arrays use many chips per system. If this platform reaches production volume, three sockets can turn into recurring orders. 🔥🚀
Source:
globenewswire.com/news-relea…
Olyth retweeted
BREAKING: $AMPG CEO BUYS SHARES AFTER QUIET PERIOD ENDS!
Fawad bought the dip yesterday. Own money, open market, first day the window opened. I think it was the right call.
The ER was bad and the selloff is justified, but it's overblown.
He's buying below what shareholders paid in the rights offering a month ago.
I am with Fawad here. Let's go 🔥🚀

$AMPG insider action here small buy
AmpliTech Group: Fawad Maqbool (Director, CEO, 10%+) Buys 12,247 Shares @ Average Price of $3.48 (Form 4)
Olyth retweeted

Can someone explain me how $ampg goes from the most favorite company on X to the worst from just one earnings report
Olyth retweeted
JUST IN: $AMPG just published the press release the market begged for on Thursday.
Numbers.
Dates.
And one line that changes the shape of the whole story.
THE HARD NUMBERS the call didn't give you:
➟ ~$17 MILLION in current backlog. Open orders. Not LOIs, not forecasts. Purchase orders on the books.
➟ MORE THAN 2,000 RADIOS shipped and in service with a Tier-1 mobile operator. The first unit count in company history. Two thousand American-designed open RAN radios on live towers. This is not a story stock anymore. It's an installed base.
➟ Over $17M in ORAN shipments since the program began. $6M+ in new orders in July alone.
THE LINE THAT CHANGES THE SHAPE:
A Tier-1 telecommunications infrastructure EQUIPMENT provider has sent AmpliTech an RFP for its ORAN 5G radios.
Management's sizing: "tens of millions of dollars" if awarded in full.
Read the word again.
EQUIPMENT provider.
Not a carrier.
An OEM.
One of the handful of companies on Earth that BUILD networks is formally asking the $118M Long Island design house to quote radios.
That's the open-socket thesis stepping out of the slide deck and into a procurement process.
The name is under NDA, and I won't guess in public.
The category is enough: there aren't ten companies that fit the description.
THE MARGIN MYSTERY, SOLVED IN ONE SENTENCE:
The company disclosed it "strategically accepted approximately $2 million in reduced profit" on the initial North American program to win qualification with a major carrier and build the reference deployment.
Translation: they BOUGHT the anchor customer with margin. On purpose. And they say that phase is "substantially completed", with future orders at "improved economics",
The 27.9% wasn't decay.
It was the entry fee.
Now you know the price of the ticket.
THE DATES, for the first time ever:
➟ Positive EBITDA: Fiscal Year 2027.
➟ Margin improvement: beginning 2027.
➟ Titan Crest: closed and cleaned up. Price cut from $8M to $7M, rights and claims fully intact.
HONEST FRAMING, and today it's heavy, because the same release also lands the plane:
➟ Guidance is back only as a FLOOR: 2026 revenue "expected to exceed FY2025". That's above $25.2M.
➟ The Asian program: active, uncancelled, but "a portion may extend into 2027". Officially slipping into next year.
➟ Under $120M market cap, ~$33M pro forma cash, zero long-term debt.
Thursday the market sold a company with no backlog number, no profitability date and no visibility.
Monday that company has $17M in open orders, 2,000 radios in the field, a profitability date, and a Tier-1 equipment maker asking for a quote.
Same company.
Better paperwork.
The delay was real.
The machine was never broken.
Not financial advice. DYOR.
Still long $AMPG.

The $AMPG sell-off looks overdone when you look at the sequence of information and what management actually said.
The stock dropped hard in after-hours right after the press release hit. That was an algo sell off based on the numbers alone.
Investors immediately panicked.
I heard a lot of people saying the thesis is broken.
Many long term investors sold.
I did not sell and if I did I would have looked at it as an emotionally driven decision not a rational one.
I wanted to take some time to think it through and not let my emotions cloud my judgement.
I don't believe the thesis is broken.
It is playing out.
You can't deny all the progress management has made over the past year transitioning the company into the only American 5G O-RAN player.
But that's what a lot of people have done.
This quarter was a key part of that transition. Not on the product side but the company side.
Many reacted to the bigger loss number before hearing the full context on the call: these were deliberate, forward-looking investments to win and support larger telecom/5G Open RAN customers.
When they announced the $10m share buyback a major criticism was that they should be investing in growth not buybacks.
Now they make an investment in growth and they are punished for it.
I will admit they did a horrible job explaining this on the call.
They also should have been upfront about their expectations going forward.
Scaling a real 5G O-RAN platform requires exactly this kind of upfront spending on technology, production capacity, commercial reach, and the infrastructure larger carriers demand.
You can give them grief for not anticipating this in advance, but I won't treat these investments into the company as a negative.
That is a long term benefit. One that will take AmpliTech to the next level.
These investments are necessary steps to achieve the growth and scale required to fully realize the O-RAN buildout and convert the pipeline into sustained higher-margin revenue.
Management explicitly called Q2 an “investment quarter.” The spending was not uncontrolled cost overrun, it was intentional preparation for bigger opportunities.
At the same time, the underlying business showed sequential progress: revenue +51% to $8.07M, gross profit +161% YoY, gross margin expanding to 27.9% from 7.8%.
July brought over $6M in follow-on orders, LOIs remain active, and the balance sheet was strengthened by the rights offering.
Markets often punish the near-term P&L hit from growth investments before fully pricing the strategic rationale.
Yes the 30% haircut sucks but I believe it is way over done. The investments they made are a required bridge to the scale the 5G O-RAN opportunity demands.
Treating that deliberate spending as pure negative news, without the context, looks like an over-reaction on the day.
The thesis is still intact and actually advancing to the next level IMO.
The timeline may have been extended, that's to be determined, but the thesis is still playing out, not broken.
