

Independent data-driven macro research. Providing macro regimes for monetizable market insights.
Joined June 2023
- Tweets729
- Following85
- Followers46
- Likes235





Pinned Tweet
Some ETFs perform mucho better than SPY during the last decade.
This is Core Thematic Portfolio building by US 🙌
More info in bio ☝️☝️
Our weekly report is now available; among other things, we break down the impact that the closure of the Strait of Hormuz is having on various 10-year government bonds.
nodeanalytica.substack.com/p…
The WTI crude oil futures contract (May '26 - CLK26) has fallen 17% today
This is due to the recent two-week ceasefire announced by Donald in the Iran-U.S.-Israel conflict
This has led to the partial reopening of the Strait of Hormuz, while negotiations continue
Our short-term outlook for oil is for a decoupling of the curve in the near term, if the ceasefire holds
We will need to closely monitor the progress of the negotiations, but it is likely that the world will begin to pay a premium for the reopening of the Strait starting today
More info in the bio
#IranWar #OilMarket

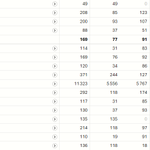
This chart is not about “who runs out of oil tomorrow.”
It shows how many days of net imports each IEA country can cover with oil stocks.
That is the key metric in an Strait of Hormuz shock.
The weak spots in this snapshot are clear:
Australia: 49 days
New Zealand: 88 days
Japan (208) and Korea (200) are far better covered on paper, while most of the European countries shown are above the IEA’s 90-day minimum.
So the immediate risk is not necessarily “empty tanks” across Europe or Asia.
The real message is:
countries with lower cover enter stress first if Hormuz stays disrupted and even countries above 90 days can still face inflation, diesel/jet fuel tightness, and logistical strain.
In an oil shock, stock levels matter.
But so do product shortages, logistics, and access.
#IranWar #Oil

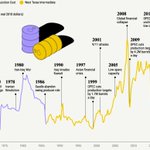
Every Middle East oil crisis hit the U.S. differently.
The key question was never just “how much did crude rise?” It was whether the shock spilled into inflation, rates, and the broader macro regime.
Credit chart to @VisualCap

Who made money from those environments?
Marc Rich exploited the post-1979 spot-market dislocation.
Andrew Hall and Louis Bacon became famous for oil trades around Gulf-war-style shocks.
The common thread: own scarcity when the market underprices disruption.
That’s why the current Strait of Hormuz crisis matters.
This one already looks faster than most post-1990 oil shocks: Brent has surged roughly 58%–59% in March 2026 and traded above $113–$116/bbl, with Hormuz normally carrying about one-fifth of global oil and gas flows.
So in speed, it looks more like an extreme wartime shock than a routine geopolitical scare.
But to become a true “new 1979,” it still needs two things: duration and second-round inflation effects.
Markets are treating Hormuz as a supply story. History says it can become a recession story.
This metric measures how far real Brent is trading above its long-term HP-filter trend. When that deviation pushes above 50%, oil stops being “just expensive” and starts acting like a macro shock: margins get squeezed, inflation re-accelerates, and demand starts to crack.
With the Strait of Hormuz disrupted, this threshold matters a lot more than most investors think.

On March 2, I shared a simple trade idea: buy CLJ26.
Not because oil “looked strong.”
Not because of a random momentum signal.
Because once Hormuz becomes a real transmission channel for macro stress, oil stops trading like a normal commodity.
We published the thesis before the situation had fully unfolded.
If you want to learn more about these trading ideas, check out the link in the bio.