

Joined January 2018
- Tweets6K
- Following2K
- Followers50.1K
- Likes11.1K



Pinned Tweet
看了一下DeepInfer的数。我觉得吧,前几天大家转载的那个SiliconData Index的价格,未来一年估计还得不回头地跌个95%+,具体什么时候影响到GPU Rental rate蛮难预测的。
这个价格体系下,梁圣买张卡估计100天就回本了。一旦有朝一日token价格真的暴跌到影响rental rate,所有股价肯定已经跌了一大轮。
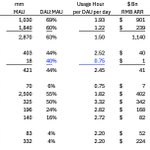
给大家几个数,所有的数都是$ / 1 mm token,基本上1mm token 95% cached = 100-150页的薄书.
- Dylan一直在说Jane Street的变现价是$100-200 USD / 1 mm token
- Opus 5.5 / GPT Astra 的价格在deepinfer的体系下大概是1-2 USD / 1 mm token,比标价便宜个80-95%
- 变态的来了,Deepseek 4.1 Flash off-peak的价格在这是1.5美分,又比SOTA便宜个90%。
- 按照一般的大B300 Cluster,根据deepinfer的计算,一个GPU大概能每小时产出2.7 Bn token, 成本换算过来大概是0.25美分 / 1 mm token,这已经比我想象中便宜很多很多了。之前算过我记得是15美分 / 1 mm token,不过没有计算cache。这个level的成本大概率是大机房+高使用率+超高存储时间,一般机房估计都做不到这个theoratical.
- 这也就是大家看到的80-85%毛利 (1.5 / 0.25)。DeepSeek要是以比这个利润率稍好的功率赚钱的话,一个B300大概2-3个月回本,而不是8个月。真是无与伦比的暴利,比贩毒爽多了,自然是砸锅卖铁也要走私B300。
- 如果B300按照break even算的话,那么成本大概是0.13美分 / 1 mm token. 然后原材料其实是B300 ~600k价格的6%不到(按照产业链毛利计算)。
- 所以最后算下来马斯克如果去完全积压的话,每1mm token的最终生产成本可能是0.01美分, or 0.0001 USD。这基本上跟免费差不了太多了。
这种屠夫版的价格我不知道你怎么看,但是when you see the headline API price of Opus @ 8/40 USD input/output,我只能感觉说只要OSS + Post-train和中国模型蒸馏大法能够持续跟随 + 没有新的breakthrough,token 价格未来一段时间应该是以断崖式的下跌。至于什么时候触碰到rental rate, maybe someone smart can tell me.


看了一下我太太工作流,飞书x豆包现在做的很好啊,tiktok/抖音私域数据 + 工作app (word, excel, etc) + 团队交流及留痕(chat + video) 一体化了。
microsoft / zoom什么的公司感觉真有点危险
5
11
2,534
A good heuristic I use is that the revenue multiples on $ANT doesn’t matter as much.
You're paying a multiple on its cumulative, depreciated compute spend, on the belief that $ANT commanding intelligence will throw off a massive spread over that cost. Ideally you size up when you pay no such premium versus prior rounds.
3
15
5,517
Robin干的事业不能投,Robin说的见解要听。
我读transcript下来就一个感受,就是看多AI原生公司。
Link:bidclub.ai/zh/e/baidu-world-…

2
17
3,533


I think even if $NVDA beat on growth & margins, raised 4Q guide, and even reaffirms FY guide + do a bigger buyback it won't be enough:
- It's always beat and raised, what's new?
- Buyback sends the wrong message. Would argue it's bad capital allocation until they have visibility post-Jensen.
- Who's gonna believe in their reaffirmed out-year guide? It just kicks the can of a kitchen-sink down the road.
I think the market would look for clarity on the following in comments & Q&A:
- Succession & clear path to fill Jensen’s shoes
- Future of vendor-financing and ecosystem investments, or at least quantified impact
- US probe and potential lawsuit re: China biz, as well as coming out on sales / margin impact
- Supplier relationship & corresponding roadmap / margin visibility
Maybe if $NVDA bleeds heavily into the print we get a pop regardless. Personally I think the pop will be faded if we get anything short of the above.
AI-induced Firing en masse requires 3 conditions:
- IQ & cost reaching a good balance
- The pilot works well and gains trust internally
- Things not going well w/ the biz
Mass unemployment is knock-in and won't happen in an up market: why fire when you can add more AI-enabled bodies going after more revenue?
...then it's going to happen like an avalanche across all firms all at once when demand slows.
5
14
2,812
This is a rather good point. Would you rather own a leaderless $NVDA today or would you rather own $SPCX + $ANT + $INTC run by winners and still have some spare change.
By owning the latter 3 one can argue it’s the eventual full integrated 5-layer cake Jensen talked about.


NVDA without Jensen means the company is going from max-aggro risk-on to being risk-neutral / risk-off. Making the odds of it double-missing in the future much higher.
7
28
5,339

On this point, I also think mosaics and mental frameworks across history can be developed. There isn’t that much new under the sun around microeconomics and business models. Boil the ocean with experts post-training and a proprietary harness / model may actually perform better than most analysts.

i suppose one has to take a view on where this is all going. my view is that as grunt work gets automated, people will need to look for totally new ways of developing a thesis/angle and a static webapp doesn't really allow you to do this well or at scale
coding agents will be the powerhouses for a lot of this work, especially when connected to best in class infra
4
8
2,532

了解了一下他们要做的产品,市场很大,切入点蛮巧妙的。做好了现金流可以很不错。值得关注下12月

Today, we commit $30 million to build new products on MegaETH, starting with AI inference.
mega.holdings
3
30
4,901