

Founder and CEO of Frec. Reach me at [email protected] Frec disclosures: https://xitter.cf/t.co/QMfm2vK0fl
San Francisco, CA
Joined February 2023
- Tweets281
- Following502
- Followers895
- Likes271




Pinned Tweet
Frec has crossed $1.5 billion in customer assets. That’s another $500 million since we announced $1 billion just a few months ago 🚀🚀🚀
We’re marking the occasion with @Nasdaq . Thank you to the Nasdaq team for featuring @frecfinance on the tower in Times Square! We’ve also been working together on something new for Frec customers that we’re excited to share soon.
Thank you to our customers for trusting us with their money, and to the Frec team for getting us here!

My sister messaged our family group: “Mo are you aware of this?? Frec is in a Netflix documentary!”
I had no idea.
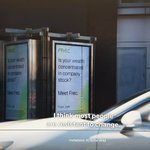
Sure enough, our Market St. billboard—“Is your wealth concentrated in company stock? Meet Frec”—shows up in the first minute of Netflix's Instadocs: AI Gone Wild.
The documentary opens with the line: “There’s this saying, the future happens first in San Francisco.” The camera pans past a Waymo, then Frec’s billboard.
The billboard was part of our first experiment with outdoor advertising. The ROI is hard to measure, but I’m counting our unexpected cameo in a Netflix documentary as a win.
As for the episode’s narrative, I see things differently. I believe society will figure out the right guardrails to make AI work for us, helping individuals and organizations become more productive. I’m optimistic those benefits will reach every corner of the economy, creating more wealth and opportunity than we’ve ever seen before.
And as AI creates a new wave of wealth, Frec will be here to help people manage it effectively so they can focus on building the future.
We’re flattered to make the cut. Thanks, Netflix!

The Treasury and the IRS just put some ETF-conversion strategies involving Exchange Funds under scrutiny, as outlined in Notice 2026-62.
In the same notice, they acknowledged that traditional capital loss harvesting can reduce taxes in a manner “consistent with the intent of Congress.”
Frec Diversify is built around capital loss harvesting, not ETF conversions. It’s a scalable alternative to Exchange Funds, designed to gradually diversify concentrated stock through capital loss harvesting. Instead of contributing your shares to a pooled fund, you keep ownership of them in your own Frec account.
We build a long extension that fills in the rest of your chosen index. A short extension helps hedge some of the risk from your concentrated position.
With those extensions in place, capital losses are generated as we rebalance the portfolio. Those losses can offset gains as we gradually sell down your concentrated position, working toward its target weight in the index.
You choose your index and can customize your holdings. There’s no seven-year holding requirement and no waiting for a fund to assemble the right mix of other investors’ contributions. The portfolio is built around your preferences - not around what a pooled fund happens to need.

Source: IRS Notice 2026-62. See Section 2.03 for the exchange-fund transactions discussed, and Section 3.01 (pages 16–17) for the acknowledgment of established loss-harvesting techniques.irs.gov/pub/irs-drop/n-26-62…
A friend in Canada texted me asking what tax-loss harvesting was. Then he told me something I had to look up to believe.
In Canada, you can use investment losses to recover taxes you paid on capital gains in previous years. Net capital losses can be carried back up to three tax years, or forward indefinitely.
Here’s a simple example. You realize a C$100,000 capital gain in 2024 and pay tax on it. In 2026, you realize C$100,000 in capital losses, with no capital gains that year.
You can apply those losses against the earlier gain and potentially get the tax you paid on it refunded.
For individual stock investors in the US, unused capital losses carry forward. You can’t carry them backward to offset gains from previous years.
My friend told me he’d used losses after Covid to recover taxes on gains he’d realized during Covid.
I thought this was fascinating. More of a reason to use direct indexing in 🇨🇦!
What happens to ETF inflows when AI agents start managing our money?
This weekend, I read Apollo Global Management, Inc. Chief Economist Torsten Slok's note on a potential “agentic bank run.” Once people trust agents to move money, idle cash could shift from low-yield checking accounts into higher-yield alternatives.
Could a similar shift happen in investing from index ETFs toward direct indexing in taxable accounts?
Owning the underlying stocks opens up more opportunities to harvest capital losses, which can be used to offset capital gains, with unused losses carried forward. You can also customize holdings and vote your shares.
Switching from one index ETF to another in a taxable account means realizing any embedded gains in the shares you sell. With direct indexing, you can retain overlapping stocks and adjust the rest, potentially reducing the tax cost of switching indices.
The tax benefits can extend into retirement withdrawals, too: unused losses can offset gains as you sell investments to fund spending.
For many investors, ETFs are the default. A trusted agent could weigh the tradeoffs and put the next dollar into direct indexing.
Apollo bank run report: apollo.com/wealth/insights-n…
Frec white paper on direct indexing benefits extending into retirement: frec.com/resources/blog/whit…
This is not tax advice; consult your tax advisor about your situation. Direct indexing may involve account minimums.

Our $100k demo account gained about $19k in roughly a year, net of financing and management fees. It uses a value-tilted 140/40 direct indexing strategy based on the Russell 1000. For comparison, a $100k investment in a Russell 1000 ETF over the same period would’ve gained about ~$445 less. And here’s the kicker: it also harvested ~$27k in capital losses while appreciating in value. This is a real account, not a backtest - anyone can inspect every position and trade on our website (link in my comment). It’s worth noting that the long short direct index carries a different risk profile and can expect a tracking error of ~1.5%.
We chose a value tilt because many of our customers work in tech and already have significant exposure to growth stocks. We wanted to demonstrate how they could lean into value while maintaining broad market exposure.
Those $27k in harvested losses can offset capital gains elsewhere. Someone selling appreciated company stock, for example, could use $27k of harvested losses to offset that amount in gains. At a combined 30% tax rate, that could defer a ~$8k tax bill, leaving that money invested in the market instead.
We made 140/40 available starting at a $100k minimum, and customers can get started in a few minutes. We also offer 200/100 and 250/150 versions. The additional leverage allows for a stronger factor tilt and creates more opportunities to harvest losses.

Link to the demo account: frec.com/app/demo/direct-ind…
This strategy uses margin and short positions, which add risk beyond a traditional long-only investment - see Frec's Margin Disclosure before borrowing. Past performance does not guarantee future results, and this account's results may not be representative of other clients' experiences, as timing, deposits, factor tilt, leverage, benchmark, and customizations vary. Frec does not provide tax advice and tax outcomes will vary by client.
QQQ assets. Page 7 here: nasdaq.com/docs/2021/04/28/N…
Assets tracked by Nasdaq-100 here:
ir.nasdaq.com/news-releases/…
Most have heard of tax-loss harvesting. But a different version is attracting the Treasury's attention: ordinary-loss harvesting. It aims to offset ordinary income, like business earnings and, within limits, salary income. Meanwhile, gains can receive more favorable capital gains treatment.
This is different from traditional tax-loss harvesting which uses capital losses to offset capital gains, plus up to $3,000 of ordinary income each year. Frec’s Long short portfolios harvest capital losses too. One high-profile example of capital loss harvesting: The Wall Street Journal reported that President Trump’s investment accounts use direct indexing.
Ordinary-loss harvesting seeks to go much further. Treasury officials have described sales pitches advertising a $300,000 ordinary loss on a $1 million investment.
A new Tax Notes article by NYU law professor @DanielJHemel explains the distinction, using AQR’s TA Delphi Plus fund as an example of ordinary-loss harvesting.
Hemel traces the strategy to a “temporary” Treasury exception from 1988 - still in place 38 years later. It lets investors use ordinary losses from certain funds to offset income from businesses they actively run, even when they don’t help run the fund. His proposed fix is to remove that exception through Treasury’s rulemaking process.
At @frecfinance, our Long short and Diversify strategies harvest capital losses. They do not pursue ordinary-loss harvesting. We’ve worked with tax counsel in structuring these strategies, and we’ll continue monitoring developments.
These distinctions matter in how the topic is covered. CNBC's recent reporting on tax-aware Long short strategies included an “IRS crackdown” section, while noting that officials hadn’t named those long short tax-aware strategies specifically.
We’d love to see coverage make clearer which products and which types of losses are under scrutiny, especially in headlines. That helps investors understand which risks may apply to them.

Now out in @TaxNotes: How Treasury created "carried interest on steroids" -- a tax strategy that allows high-net-worth investors w/sufficient liquidity to transform potentially unlimited amounts of active business income into long-term capital gain ... 1/

“You guys found the perfect crowd. We’re all rich dads, and this is the ultimate rich dad joke.”
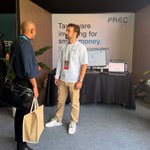
That was one attendee’s reaction to our “Long short” shirts at this year’s All-In Summit. 😂
@frecfinance was back as a sponsor this year. That’s Nolan Pecci in the photo: one long sleeve, one short sleeve. We took product marketing literally.
There’s a more serious reason we like this audience. We’re building Frec for people who want to stay involved in managing their wealth. They want access to sophisticated investment strategies without having to manage every trade themselves or hand their entire portfolio over to an advisor.
The team’s report from the booth: “The shirts are a hit.”
Thanks to @chamath, @Jason, @DavidSacks, and @friedberg for having us back. And to Nolan for committing to the outfit.


Here’s a small example of how nuanced tax-loss harvesting gets in a long short portfolio: when you close a short at a loss, the loss is recognized on settlement date. When you sell a losing long position, however, the loss is recognized on trade date - usually one business day earlier under T+1.
The reason is that, for tax purposes, a short sale is not considered complete until the shares are delivered to close the position. That delivery date also anchors the wash sale window for the short position, so a losing short and a losing long are measured from different days.
One day may sound immaterial. But when running long short portfolios at scale, a system that treats every loss as occurring on trade date can miscalculate the wash sale window and, for a December trade, place the loss in the wrong tax year.
Yesterday, Moderna rose roughly 177% in a single day after positive Phase 3 results for its cancer vaccine.
Anyone short Moderna took real losses. So our quant team immediately looked at Moderna exposure across Frec's Long short portfolios.
This is why risk controls matter.
When we construct a Long short portfolio, no individual short position is allowed to become a meaningful concentration. Positions are diversified and capped at 1-2% of the portfolio at construction, so even an extraordinary move in a single stock has a limited impact on the overall portfolio.
Long short direct indexing does introduce incremental risk versus a class direct index. A classic direct index targets roughly +/- 0.8% of tracking error, compared with roughly +/- 1.5% for our 140/40 strategy. The increase in tracking error risk is deliberate: accept a somewhat larger risk budget in exchange for factor exposure, the potential for excess returns, and substantially more opportunities to harvest tax losses.
The important part is that the additional risk is engineered and monitored rather than taken blindly.
This is what makes Long short direct indexing such an interesting financial product. We think most index investing will eventually move toward direct indexing over time, and a meaningful share of it will use Long short extensions.

We just released two important updates to Frec, and customers are already putting them to use.
𝗙𝘂𝗻𝗱 𝗮 𝗟𝗼𝗻𝗴 𝘀𝗵𝗼𝗿𝘁 𝗱𝗶𝗿𝗲𝗰𝘁 𝗶𝗻𝗱𝗲𝘅 𝘄𝗶𝘁𝗵 𝗘𝗧𝗙𝘀
Customers can now fund up to 70% of a Long short direct index with eligible ETFs, making it much easier to meet strategy minimums without selling appreciated positions.
For example, a customer can now fund a $500K Quality-tilted 250/150 S&P 500 direct index with $150K of QQQ, $200K of SPY, and just $150K of cash.
To make this work, we upgraded our risk models to understand the exposures inside ETFs. Rather than simply selling the ETF, the optimizer can account for those existing exposures when constructing the long and short extensions. If the contributed ETF is heavily exposed to technology, for example, the rest of the portfolio can be built to help offset that concentration.
We cap ETF funding at 70% (with no single ETF making up more than 50%) so the strategy still has enough cash to maintain healthy tracking. We don’t support every ETF yet, but most mainstream ETFs are eligible.
𝗣𝗼𝗿𝘁𝗳𝗼𝗹𝗶𝗼 𝗮𝗹𝗹𝗼𝗰𝗮𝘁𝗶𝗼𝗻𝘀 𝗻𝗼𝘄 𝘀𝘂𝗽𝗽𝗼𝗿𝘁𝘀 𝗺𝗼𝗿𝗲 𝗮𝘀𝘀𝗲𝘁 𝗰𝗹𝗮𝘀𝘀𝗲𝘀
Portfolio allocations is one of my favorite features at Frec. Customers can combine multiple direct indices, assign target weights to each, and have every recurring deposit automatically allocated toward those targets. They can also rebalance the portfolio with a tap.
Until now, the feature was mostly focused on our direct indices. We’ve expanded it to support bonds, international bonds, TIPS, precious metals such as gold, commodities, and cryptocurrencies through a curated set of ETFs.
This makes it possible to manage a much broader investment portfolio inside Frec while keeping target allocations automatically on track.
And we have a lot more cooking 🧑🍳
Today, every U.S. citizen has a $15M federal estate tax exemption. For a single person, the portion of a taxable estate above $15M can be taxed at 40%.
Separately, something else happens at death: appreciated taxable assets receive a step-up in cost basis. If someone bought Apple at $10 and it's worth $500 when they die, the heir's cost basis generally becomes $500. The $490 of unrealized capital gain is never taxed as a capital gain.
These are two separate parts of the tax code, and a lot of discussion about tax deferral conflates them.
One of the main benefits of tax-loss harvesting is that it can defer capital gains taxes. If those gains remain deferred until death, step-up in basis can eliminate the capital gains tax.
But that doesn't eliminate the estate tax.
If someone dies with a large taxable estate, the federal government can still collect 40% on the amount above the available $15M exemption.
This is why I think describing capital gains deferral as simply "tax elimination" is misleading, as some recent media articles have claimed.
Yes, the capital gains tax can disappear at death. But for wealthy estates, a separate 40% tax can still be collected through a completely different part of the tax code.
And frankly, that makes intuitive sense. Without step-up, someone could pay capital gains tax and then have the remaining wealth subjected to estate tax at death.
The $15M exemption also isn't fixed. It was $5M in 2011 and is $15M today. Congress has changed it before and can change it again.
It seems to me that if Congress wants to collect more tax from large estates, lowering the estate tax exemption is the more direct mechanism.