
Finance & energy drinks. Investor.
🦈
Joined December 2012
- Tweets5.6K
- Following485
- Followers1.3K
- Likes19.3K






Pinned Tweet
October Portfolio Update
Performance: -15.9% YTD, 64.4% 3Y
vs S&P500: 8.8%, 75.7%
Tilt (by Claude):
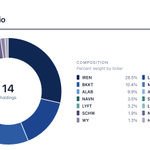
The month's two biggest decisions were close to an even swap: cutting Lyft by more than three quarters and adding to IREN, each moving about 11% of equity value. Arm and Meta were closed outright along with the small Portland General stake, and Schwab, Strive and Navan were trimmed. That capital went into IREN, a more than tripled Astera Labs position, a larger Bakkt stake and a new starter position in Lattice Semiconductor. Net effect is a more concentrated book, with the three largest holdings rising from 49.9% to 54.2% of equity value and IREN alone at 28.5%.
Memo:
The plummet of the broader AI ecosystem has been really energizing over the last few weeks, prompting me to jump back into research in a big way and stress test the conviction in my best ideas.
The result of this introspection was a continuation of last month's trimming of non-core positions in order to double, or in the case of $ALAB, triple down on positions where I see the most asymmetry.
Here are relevant thoughts related to my portfolio that I've posted over the last month:
> $ALAB – xitter.cf/jwat_5/status/21150994…
> $LSCC – xitter.cf/jwat_5/status/21136899…
> $BKKT – xitter.cf/jwat_5/status/21155902… xitter.cf/jwat_5/status/21158165…


Freed up cash to buy $IREN
At this value, market is pricing in the worst case scenario at every level
2
12
922
$ALAB - good intro to the CEO, company, and thesis youtu.be/dTA7PUyKTCA?si=4Vy8…
1
225


Congratulations to Mobileye President and CEO Prof. @AmnonShashua on receiving an honorary doctorate from the Weizmann Institute of Science.
The institute recognized Prof. Shashua for his "groundbreaking contributions to scientific research in artificial intelligence, computer vision, and deep learning, as well as his ability to translate scientific breakthroughs into technological innovations with a lasting impact on industry, society, and public safety."

1
2
262
$BKKT – Q3 Follow-Up Q&A
Respect and kudos to the IR team for getting back to me quickly after we sorted out an email filtering issue.
Before I post their responses here, I do want to preface by saying that in my experience, there is only so much IR can say outside of the quarterly materials.
But even with that said, these responses err very much on the side of zero additional color, which is sad, yet understandable.
A sell-side analyst would have received more information live on the call, which we can chalk up to the institutional advantage and the benefit of having management respond directly.
I can personally confirm this, because when I asked a question in-person at Investor Day earlier this year, Akshay went to great lengths to provide a high-quality answer.
I'll post my submitted question in bold, copy IR's response verbatim, and then add my commentary in italics. I would typically paraphrase the responses, but in this scenario I feel it's appropriate to paste directly for full transparency – and so you can make your own decisions.
Q: What happened to breaking even on adjusted EBITDA in Q4? If it slipped, why?
A: We didn’t put a break-even date in the Q3 materials and aren’t adding one here. What’s public is the cost base (opex ex crypto costs and execution fees of $16.1M, down 40% year over year) and the bridge: net revenue as contracted flows activate, with the expense base held. The volume side you’ll see monthly from December.
> I pushed back on this answer. On the Q2 call, Akshay directly said "... my expectation is Bakkt will reach adjusted EBITDA break-even at some point during the fourth quarter of 2026." In my opinion it's acceptable if this slipped, but it would be helpful to understand how Akshay feels a quarter later.
Q: Did the Q4 target for co-branded cards and neobank-as-a-service slip? If so, why?
A: The Agent roadmap is shown by status now rather than by quarter: Embedded Finance is available to partners today, co-branded cards and Neobank-as-a-Service follow, and the stablecoin card program with Thredd is planned, all subject to product readiness, client launch timing, bank and network requirements, and applicable approvals. Partner launches and MAUs (9,760 for September against ~25,000 targeted for December, reported quarterly) are the way to track it. We did have the one launch, Bakkt Payments Portal, live for business clients.
> This seems like gymnastics to say that co-branded cards and neobank-as-a-service slipped. I would have liked to understand if it's due to internal prioritization of resources or external dependencies. Again, not an issue if it's explained.
Q: What happened to US and EU tier-one telecom partners for distribution? How about other verticals? What about eSIM?
A: No update on specific partners or verticals beyond what’s been announced. When there’s something to say on distribution it comes through an announcement, not ahead of one.
> Unfortunate to not get more information here. We can only assume that telco distribution is still on. I think that other verticals are also being targeted.
Q: What types of customers are in the pipeline for payments volume? Which sectors are getting the most traction? How about larger, institutional customers?
A: The clients activating now are the institutional and cross-border ones that were integrating in Q3, using what’s already on the platform: trading execution, stablecoin on- and off-ramps, cross-border payments and Embedded Finance. We’re not breaking the pipeline out by sector or size; the thing that matters is that once they’re live, the settlement, treasury and payments flows recur. Worth a look at the commercial team we added this fall; their backgrounds tell you which markets we’re going after.
> This is somewhat interesting. Bakkt has mentioned targeting commodity sectors in the past, but their recent commercial hires are mostly non-US institutional trading and fintech distribution. Tracks with their stated objective on the call of standing up the trading desk.
Q: When do you expect to guide TTV for 2H27? Is there any visibility out that far?
A: The targets out there are ~$3B for FY26 and ~$6B for 1H27, and actuals come monthly from December. Nothing to add on 2H27 at this point. ARV month by month will tell everyone, us included, what’s recurring and what’s chunky.
> Wasn't expecting anything significant here, but would have been cool to hear Akshay say that he's feeling good about the back half.
Q: What is the product market fit for MCP? Are you seeing early customer interest?
A: Nothing to add on MCP beyond what’s public. Anything measurable there shows up in MAUs and the Engine Report over time rather than as a separate call-out.
> Good to hear that MCP will be in the Engine Report. Guess we'll see in December.
Jared retweeted

An API is a button: sewn onto a shirt, one custom integration at a time.
MCP is a cufflink: one standard fastening for any AI agent, using only the holes already cut.
With $BKKT’s production MCP server, the underlying payment rails don’t change, just how safely and fast an agent fastens to them. 👔
Learn more: docs.bakkt.com/docs/mcp
For important information: bakkt.com/disclosures
Followed up with IR. Will keep everyone posted.
I call it like I see it, and that was an unimpressive Q3 earnings presentation for $BKKT. The only valuable info was the $6B target for 1H27, and I came out of the call with more questions than answers.
> What happened to breaking even on adjusted EBITDA in Q4? If it slipped, why?
> Did the Q4 target for co-branded cards and neobank-as-a-service slip? If so, why?
> What happened to US and EU tier-one telecom partners for distribution? How about other verticals? What about eSIM?
> What types of customers are in the pipeline for payments volume? Which sectors are getting the most traction? How about larger, institutional customers?
> When do you expect to guide TTV for 2H27? Is there any visibility out that far?
> What is the product market fit for MCP? Are you seeing early customer interest?
My Take
Despite the disappointing investor relations, I see a lot of value at the current share price if you take the $6B at face value, and I'll tell you why. My base case, using napkin math, is that Bakkt does ~$15B in TTV next year, which assumes moderate QoQ growth in 2H27.
As a relative comp, BVNK, with ~$30B in stablecoin volume, was acquired by Mastercard in August for $1.8B. If you do quick math again, factoring in 50% of BVNK volume at Bakkt's share count and market cap, that gives Bakkt a buyout floor of ~$20 (!). If they hit their 1H27 TTV target and continue to grow modestly in the back half, of course.
When you add a rudimentary SOTP analysis and ascribe value to their US and EU licenses, Bitcoin Japan and Transchem, and Bakkt Agent, then you start to unpack the asymmetric opportunity that I know I invested in Bakkt for.
I call it like I see it, and that was an unimpressive Q3 earnings presentation for $BKKT. The only valuable info was the $6B target for 1H27, and I came out of the call with more questions than answers.
> What happened to breaking even on adjusted EBITDA in Q4? If it slipped, why?
> Did the Q4 target for co-branded cards and neobank-as-a-service slip? If so, why?
> What happened to US and EU tier-one telecom partners for distribution? How about other verticals? What about eSIM?
> What types of customers are in the pipeline for payments volume? Which sectors are getting the most traction? How about larger, institutional customers?
> When do you expect to guide TTV for 2H27? Is there any visibility out that far?
> What is the product market fit for MCP? Are you seeing early customer interest?
My Take
Despite the disappointing investor relations, I see a lot of value at the current share price if you take the $6B at face value, and I'll tell you why. My base case, using napkin math, is that Bakkt does ~$15B in TTV next year, which assumes moderate QoQ growth in 2H27.
As a relative comp, BVNK, with ~$30B in stablecoin volume, was acquired by Mastercard in August for $1.8B. If you do quick math again, factoring in 50% of BVNK volume at Bakkt's share count and market cap, that gives Bakkt a buyout floor of ~$20 (!). If they hit their 1H27 TTV target and continue to grow modestly in the back half, of course.
When you add a rudimentary SOTP analysis and ascribe value to their US and EU licenses, Bitcoin Japan and Transchem, and Bakkt Agent, then you start to unpack the asymmetric opportunity that I know I invested in Bakkt for.
Nice earnings call from $SLDP. I remember back when sell-side wouldn't even call in, and it would end without any questions.
Still such an early stage company, but at least there are milestones to look for over the next few quarters like:
> MOBIUS completion by EOY and associated cost savings from continuous vs batch production
> New supply agreements for MOBIUS capacity
> New JV or partnership with Samsung SDI
> Korea JV for 500 annual metric tons of production
> Commercial progress in the humanoid robotics, defense, and unmanned aircraft spaces
1
2
517
$BKKT: Bakkt Docs Update
No updates this week 💤
See ya next week for earnings!
$BKKT: Bakkt Docs Update‼️
TLDR: MCP Server is LIVE in production, making Bakkt's suite of services, including onboarding, accounts, and stablecoins available to AI agents. Other relevant changes include updates to the stablecoin and onboarding APIs, and five new BakktX/trading guides.
Product MCP Server Launched
> Live in Sandbox and Production environments with "50+ tools and resources" and "more tools and features planned for the coming weeks"
> Available tools include onboarding (user create, login/OTP, KYC), accounts (bank accounts, transactions, micro-deposits, transfer between accounts, remittance quote), and stablecoin (custodial wallets, ACH pull, off-ramp, FX convert, on-chain balance)
> Remittance send appears to be tagged PREVIEW
Stablecoin API v1.1.1
> Off-ramp fee estimates now validate the payment method against the payout currency
Onboarding API v1.0.2
> KYB applicant import via Sumsub
BakktX Guides
> Fiat Funding Onramp, Wire Funding, and 2025 Tax Season Overview, Digital Asset Reporting
Trading Guides
> FIX Protocol Specification and Tax Certification Requirements
Bakkt team has been busy ahead of Q3 earnings.
Debit card issuance, direct deposit, P2P payments, and remittance send are all still PREVIEW.
See ya next week!
3
11
1,191
Jared retweeted

🚨 $IREN's >35 GW Pipeline
They FINALLY did it.... I can't believe $IREN finally revealed the size of their massive pipeline.
For years investors were begging management to reveal the size of their power pipeline.
It only took the stock to crash 58% YTD for them to reveal this very relevant piece of info.
But honestly, wow. No other neocloud, or colo provider for that matter, even comes close to 35 GW...

Jared retweeted

First pure-play humanoid IPO $AGLT starts trading today after merging with a SPAC.
Agility's new model is designed to perform more complex work such as loading materials and working alongside people. As they go public, they have ~$465M of proceeds (before expenses) against ~$300M in "multi-year orders" from a single customer. Headcount is growing aggressively. On the SPAC, only 40% of the trust stuck around and the raise ended well short of the original target of $600M+.
I imagine they will need lots more capital and it won't be cheap. The SPAC structure also complicates the cap table.
Backed by $NVDA, AMZN, Softbank, and manufacturing partner Foxconn.
Hard pass.

$LSCC insider activity
CEO and director Ford Tamer bought 9,790 shares in the open market on November 4 in three lots at weighted averages of $101.78 to $103.40 (about $1.0 million, average about $102.52), not under a 10b5-1 plan (Form 4 filed November 4). The shares are held in a trust that holds 19,790 shares afterward; he separately reports 315,677 shares.
321
$LYFT announces new membership program Lyft Go
Lyft Go includes DashPass at no additional cost, earns 8% back in credits to use for rides and DoorDash orders, and doubles members' donations to the causes they care about
Lyft Go with DashPass ($9.99/month or $96/year): Members earn 8% back in Lyft Credits, redeemable on Lyft rides – from Wait & Save to Lyft Black – or DoorDash orders, with a DashPass membership included at no additional cost. Also includes relaxed cancellations, automatic Round Up & Donate donation matching, and lost item fee waivers.
Lyft Go Core ($4.99/month): An affordable program offering 5% back in Lyft Credits, redeemable on Lyft rides. Also includes relaxed cancellations and automatic Round Up & Donate donation matching.
investor.lyft.com/news-event…
