

Believer - Attorney - Builder | Helping entrepreneurs and families build and preserve legacies | The Lively Group Posts are general info, not legal advice
Arkansas, USA
Joined March 2009
- Tweets2K
- Following1.7K
- Followers2K
- Likes1.3K






Great first day at the @CrispGrowth summit in Atlanta. Enjoyed hearing from speakers like Crisp founder @mogill, @TheSharkDaymond, and others. Looking forward to day 2!

2
134
“You get a CFP bid, you get a CFP bid!”

Breaking: The College Football Playoff and ESPN have signed a five-year, nearly $1.7 billion deal that will expand the field to 24 teams in 2027 with ESPN as its continued broadcast partner, sources told @CFBHeather.

1
103
John Jacob Lively retweeted

Being a lawyer is just spending all week looking forward to the weekend, then spending the entire weekend worrying about all the work you have the following week over and over again until you die.
Interesting and concerning development for the Arkansas legal community.
A former Arkansas bar exam official has reportedly been charged with 65 felonies related to alleged bar exam score tampering.
I’ll be interested to see what additional information comes to light as this unfolds.
katv.com/news/local/former-a…

I just watched all nine Star Wars movies with my son, so maybe this is a me problem…
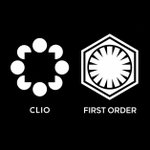
@goclio, I love you, but I have one question about the new logo:
Is the First Order getting into practice management? 👀
If you can use the Force to capture all my billable time, I’m willing to hear you out. Just keeping an eye out for @jack_newton to be “Clio Ren” 😂
On another note, the new features in Clio are awesome. Can't wait to deploy them further into our practice.
Fellow Clio users and Star Wars fans: you see it too, right?
🤖 Made with AI

1
2
205
My favorite ritual of working at coffee shops is getting my coffee, pulling my laptop out of the bag, and then having my knees bump the table to spill said coffee. ☕️
Common side effect of having long legs.
2
104


You can buy a $1 million business with about 10% down.
That’s what people hear about SBA loans. Here’s what they don’t!
An SBA 7(a) loan is one of the most common ways to buy an existing business. The SBA generally requires at least 10% of the total project cost as a down payment, and acquisition loans are typically repaid over about ten years.
What surprises first-time buyers:
1. You’ll sign personally on the loan. Anyone owning 20% or more generally has to guarantee the loan.
2. Your house may be part of it. If the business assets don’t fully secure the loan, the lender generally has to take available equity in the owners' personal real estate.
3. The lender underwrites history, not projections. Under the newest SBA rules, the business’s past cash flow generally needs to cover the payment with about 25% to spare.
4. The seller’s role has rules. A seller note can count toward your 10% equity injection only if the seller takes no payments for the life of the loan, and only up to half of it. A seller who keeps any ownership generally has to guarantee the loan too.
None of that should scare off a good buyer. It should make you careful though.
Buying a business can be one of the fastest ways to build something worth passing down. Make sure what you sign protects the family you’re building it for.
When one spouse dies, one Social Security check stops. The bills don’t.
Let's assume a retired couple receives $2,400 and $1,600 a month from Social Security, which is $4,000 total. When one of them dies, the survivor generally keeps the larger check and the smaller one stops.
That’s $1,600 a month gone. Nearly $20,000 a year.
The mortgage doesn’t drop by 40%. Neither do the utilities, the insurance, or the property taxes.
It can get tighter. A pension may shrink or stop depending on the option chosen at retirement. Taxes can go up too, because the survivor eventually files as single, often on similar income with narrower brackets.
Most retirement plans are built around “us.” The harder question is what happens to the one left.
Three questions worth asking together:
1. If one of us dies, what income stops and what continues?
2. Did we choose our pension options with the survivor in mind?
3. Does the person who’ll be left know where everything is and who to call?
Planning for retirement means planning for two people.
Planning for the survivor is how you keep taking care of the person you love most after you’re gone.
1
3
190
Busy and faithful can look exactly the same from the outside.
About three years ago, I came across Mike Foster's Primal Question framework. It’s built on seven questions that shape how we see ourselves, relate to others, and respond to life. Each person has a question that they are constantly probing the world for a "yes" or "no" response to.
Mine was clear right away: Do I have a purpose?
As a Christian, I know the answer. My purpose is rooted in God’s will for my life. Knowing that and living it are two different things though.
I can fill a calendar, solve problems, and chase good opportunities without stopping to ask whether any of it is what God is asking of me. Activity can give you a quick sense of significance; however, discernment asks more.
Three years later, my question hasn’t changed. What’s changing is how quickly I notice when I’m running on activity instead of purpose.
Now I try to pause before I say yes:
Why am I saying yes to this?
Does it serve the commitments God has already placed in my life?
Will I stay faithful if the work is quiet and the results take time?
Sometimes that means stepping forward. Sometimes it means turning down a good opportunity so I can give my best to what’s already mine to do. Other times, it's working through a season of pruning as I get clarity on where my yes should be next.
Busy and faithful can look exactly the same from the outside. Only one of them leaves something worth handing down.
Where do you need to rethink your yes this season?
2
106
A client brought me an estate plan they made online. On the surface, it looked "legal." Looks can be deceiving!
Between AI and online form sites, anyone can make a will, a trust, or an LLC operating agreement in an evening. Most of them look the part. The clauses sound official.
The trouble isn't what the software gets wrong; it's what it never had a chance to know.
It doesn't know that your son is great with money but married to someone who isn't.
It doesn't know that the farm has been in your family for four generations and your daughter is the only one who wants it.
It doesn't know that a second marriage means "everything to my spouse" quietly disinherits your kids.
It doesn't know your business partner plans to retire in three years.
A form asks the questions it was built to ask. AI answers the question you typed. Neither one asks the follow-up question where the real answer usually shows up.
I use technology every day, and it helps make good work faster! It just doesn’t replace the conversation that reveals what actually matters.
If you've made a plan or agreement yourself, online or with AI, sit down with an attorney and walk through it together. The goal isn't to start over. It's to find what the technology missed while there's still time to fix it.
1
2
96
You spent 30 years building the business. Now it’s a promissory note in a drawer.
The buyer paid part up front. The other $2 million comes in monthly payments over the next ten years.
Who gets those checks if you die in year three?
It’s a question that often gets skipped. The estate plan was built when the business was the big asset. Now the business is gone, and the biggest thing you own is the note.
Three questions worth asking after any sale involving owner-financing:
1. Who owns the note? You personally? Your trust? The company that sold the assets? Ownership affects who can collect the payments and how that value ultimately reaches your family. If you own it personally, probate may be needed to manage and transfer it.
2. Is it secured? If the buyer stops paying, what can your family actually do about it?
3. Does your family know who the buyer is, what’s owed, and how to collect?
For a lot of owners, the business is the biggest part of the financial legacy they’re building. Selling it changes what that legacy looks like: a note instead of a company.
Building it took years. Preserving it for the next generation means making sure the payments, the paperwork, and the plan all point in the same direction.
3
4
290

How do you leave several million dollars to a 19-year-old?
It’s a question I hear more than you’d think. Parents who built something of value and have a great kid who also happens to be 19.
A lot of the plans I review do one of two things. Hand it all over at 21, or lock it up until 35 and hope the trustee says yes when it matters.
Neither one teaches the child anything.
What I like better is a ramp. At 25, your child becomes a co-trustee alongside someone you trust. They sit in on the decisions. They see how distributions get made, why the investment account isn’t an ATM, and what it costs to keep the family property running. At 30, they get more say. At 35, full control.
By the time the money is theirs, managing it isn’t new. They’ve had ten years of practice with someone beside them. The ages are the clients to pick. The point is that the plan should teach, not just make them wait.
If you’re building a trust for your kids, ask your attorney one question: what will my child learn between now and the day they get control?
2
154
Your LLC cost $45. Whether it protects you is a different question.
That's the filing fee to form an LLC in Arkansas. What owners are paying for is simple: if the business gets sued, the claim stays with the business, and your personal savings stay yours.
That protection isn't automatic. It holds up when the company is run like a separate company. When it isn't, a court can decide the business and the owner are really the same thing, and the owner's personal assets are exposed.
When I practiced business litigation, this was one of the first places we looked when the other side hid behind an LLC. Did they actually run it like a company?
Here's what that usually looks like. No separate bank account, so personal and business money run together. Contracts signed in the owner's name instead of the company's. Nothing written down when big decisions get made.
Q4 is a good time for a quick checkup:
1. Does the company have its own bank account, and does every business dollar run through it?
2. Are your contracts, leases and invoices in the company's name?
3. Is your operating agreement current, especially if an owner joined, left or changed roles this year?
4. Does your insurance still match the business you run today?
Fifteen minutes now beats finding out in a lawsuit.
3
85
A $2,500 trust. A $60,000 probate bill. Same family.
I call it the false finish line.
A family pays for a trust. They sit in a conference room, sign a stack of documents, and take home a binder. It feels finished.
It isn't. A trust only controls what has been moved into it. The house has to be deeded. The accounts have to be retitled. The beneficiary forms have to be updated.
In the case I'm thinking of, none of that happened. The documents were fine. When the owner died, everything still went through probate, and the legal fees came to around $60,000.
They paid for the plan and got none of the protection.
If you have a trust, here's a check for this week. Pull one bank statement and read the name on the account. Is it yours, or your trust's?
2
4
256
Flew @Delta earlier this week. Haven’t had internet that slow since the dial-up era 25 years ago…
Was on @AmericanAir a few weeks ago. It’s internet is better than Delta but @Starlink on @united is LEGIT.
You can win the Super Bowl and still want more!
Yesterday, we had a table at The Summit where we had the opportunity to hear @TonyDungy speak.
After winning the Super Bowl, he was celebrating with his team when the conversation almost immediately shifted to:
Can we win it again next year?
As he told the story, he reminded us that no achievement is capable of providing lasting satisfaction.
As someone who is constantly setting the next goal, that one stuck with me.
Go ahead and build the business. Chase the goal. Run to win.
Just don’t confuse winning with the reason you’re running.

1
4
331
Be. Do. Have.
I heard this execution framework for the first time earlier this week. I love how simple it is.
How do you HAVE what you want?
You have to DO the things required to get there.
How do you consistently DO those things?
You have to BE the type of person who does them.
Want to be healthy? Well, you have to do healthy things! Eat right, exercise, good sleep, etc.
Want to grow your business to a certain level? You have to lead with clarity, be disciplined, and learn to delegate.
How do you do those things? You set in your mind to be the type of person who consistently does those things.
Get clear on what you want to HAVE then work backwards.
What do you need to DO?
Most importantly, who do you need to BE?
1
70
A buy-sell agreement can be perfectly drafted and still fail when it matters.
The question is simple: If your business partner died tomorrow, where does the money actually come from to buy their family out?
That’s one reason I love working alongside financial advisors on these conversations with business owners. We can tag team the planning to make sure the legal structure and funding strategy actually work together.
Sometimes that means life insurance. Sometimes disability coverage, cash reserves, or a structured payout. Often, it’s a combination.
A legal document outlining what happens is only as good as the funding mechanism backing it up.
1
3
107