
Saved by Grace
United States
Joined November 2024
- Tweets2.4K
- Following603
- Followers680
- Likes4.3K


Pinned Tweet
RC1 $RC1.AX
🏅 Market cap $12M
🙂 Debt-free
🎯 Located in the Eastern Goldfields
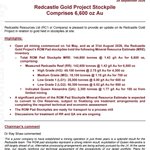
👏🏻 Already mined 6.6k ounces of gold this year! The value of the mined ore exceeds the current market cap of the entire company
🔥 42k ounces — current JORC MRE
💪 Potential to expand the resource


Investment Diary retweeted

Monument Mining Buyback Proposal: $MMY.V $MMTMF
A comparison of investing cash into Monument's own shares versus building a new mine in Australia or buying another producer. This is the bottom-line chart. The complete report is attached. A path to a 40-bagger is feasible. cdn-ceo-ca.s3.amazonaws.com/….


I just finished buying a 12M market cap Eastern Goldfields based company -
👏🏻 6.6 koz already mined this year!
🔥 42 koz JORC MRE
💪Potential to expand the resource — 2m @ 37.52 g/t Au, including 1m @ 67.70 g/t
— 5m @ 12.47 g/t Au, including 1m @ 46.90 g/t
🧐 MC 12M? HOW??? 🤫


Why buy $NST.AX while you can buy LM8


Lunnon Metals would have made $20M net this year at gold price $3500.

Why is China buying so much gold? Because it's cheap! Also, they need to accelerate treasuries sells. However, I am not buying $GDX - see what I am buying below:

I made 3X on $ALTN.L. I also made 3X on $MSA.TO. Then, I made 3X on $BCN.AX. Bought those before everyone else discovered. Now I bought Lunnon Metals:
It's time to sell overvalued $GDX and buy undervalued producing microcaps instead!
I increased Lunnon Metals - made it my biggest position. 30% shares owned by Gold Fields, selling ore to them. Lady Herial was low AISC (below 2000 USD). They made net 40M in 6 months. Now, MC 80M, cash 40M, Nickel optionality ~20M. New deposits identified. 13M exploration budget


Investment Diary retweeted

Alara $AUQ.AX breaking out. I prev wrote this up here...
rapercapital.com/2026/08/24/…
If you run-rate what they've reported for shipments this qtr, I have this - despite the move - on about 1.5x EV/EBITDA...w/ the JV rapidly reducing debt given current spot Cu pxes...or about 1-1.5x P/FCF...
Rerating just getting started imo 👊👊


Investment Diary retweeted

$ENQ.L chart is interesting
Let claude make an analysis
Its balls cheap on 2027 (and beyond) earnings

Investment Diary retweeted
$SBM.AX 😍 75cps cash + 25cps royalty + franking + XXcps on Nova Scotia (which could be upward of A$1.50/sh pending permitting outcome).. 🔥🔥


BOOM. A key risk to these "cash boxes" is mgmt blowing the cash on something stupid and empire building. This is not the case here.. mgmt is actively trying to monetise Assets and maximise shareholder returns... $SBM.AX
