

part time lycanthrope 🐺 🌕 occasional degenerative sloth @lute 🦥 full time retired goat in the previous life 🐐 👼 angel investor https://xitter.cf/t.co/w9Q8i0kzDQ
Ördögház
Joined May 2024
- Tweets2.7K
- Following844
- Followers5.1K
- Likes6.3K






Pinned Tweet
Never fade me when it comes to stocks. Just as predicted $SIVE $SIVEF is emerging as a critical chokepoint in CPO laser supply.
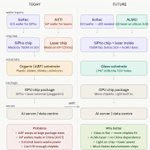
The co-packaged optics (CPO) supply chain is undergoing a meaningful structural shift and Sivers Semiconductors appears to be at the center of it.
The thesis begins upstream. Following NVIDIA's aggressive capacity commitments with Coherent ($COHR) $LITE Lumentum(COHR) and $COHR $LITE reportedly north of $2B in aggregate available laser supply for competing programmes became severely constrained. A similar dynamic played out with electro-absorption modulated lasers (EMLs) in early 2025, and the resulting bottleneck is now well-documented across the supply chain.
With tier-one laser capacity effectively pre-allocated to NVIDIA's roadmap, AMD and the broader hyperscaler ecosystem were left competing for what remained. This scarcity appears to have accelerated qualification timelines for alternative suppliers - most notably Sivers, operating through its Win Semiconductors partnership with GlobalFoundries $GFS as the manufacturing backbone.
Several data points support this:
GlobalFoundries explicitly named $SIVE and $LITE as the only two publicly listed laser suppliers within their photonics ecosystem - a notable signal given GFS's gatekeeping role in the supply chain.
Ayar Labs, a key optical I/O enabler in AMD's CPO architecture, has visibly de-emphasised Lumentum and MACOM $MTSI on their supplier documentation, elevating Sivers to what appears to be primary laser supplier status.
The downstream CPO programmes now routing through Sivers span a broad set of architectures: Marvell's $MVL Celestial platform $NVDA -affiliated, laser-less at the chip level), AMD's CPO initiative via Ayar Labs, POET Technologies, Lightmatter, and various contract programmes including Jabil's $JBL 1.6T transceiver work.
The structural read here is straightforward: when the dominant laser suppliers are fully allocated, the ecosystem routes around the bottleneck. Sivers - a ~$1.2B Swedish fabless semiconductor company has emerged as the independent, bleeding-edge alternative with the right process node access and existing design wins to absorb that overflow.
Looking ahead to early next year, the NVIDIA-driven laser bottleneck is unlikely to resolve quickly. Secondary suppliers will likely capture incremental overflow as CPO architectures standardise, but the primary demand vector points toward Sivers and its manufacturing partners. For a company of this capitalisation, the exposure to what is shaping up to be a critical infrastructure chokepoint in AI hardware.


Most people still haven't connected the dots on Sivers $SIVE. This will be another $AXT play, 10-100x or more.
This isn't just a photonics play. It's a US national security asset hiding in plain sight at a $330M market cap.
Sivers has already secured two CHIPS Act grants - a program that almost never writes checks to small caps:
- Beamformer ICs for 5G/6G infrastructure alongside Ericsson and Raytheon - Electronic warfare technology with BAE Systems and the CEO has openly hinted more CHIPS funding is coming in 2026.
Think about what that means.
The US government has effectively validated this company twice over - once for defense/national security, and again implicitly through its position in the commercial AI infrastructure stack via Marvell Celestial, Ayar Labs, Jabil, and O-Net feeding directly into Microsoft, Meta, Amazon, and Oracle datacenters.
The two biggest bear case questions about Sivers have also just been answered:
Scale vs. capex? Resolved - Win Semi partnership handles manufacturing scale without Sivers drowning in capex.
CPO timing risk? Resolved Jabil's 1.6T pluggable ramp announced at OFC means near-term revenue doesn't depend on waiting for co-packaged optics adoption.
Dual revenue engines. Government-backed. Sitting at the intersection of AI photonics and defense semiconductors. At $330M.
For context, Coherent and Lumentum doing adjacent things at larger scale trade at $45B+ combined.
The gap between what this company is worth and what the market is currently pricing it at is hard to justify once you lay it all out.
$2B+ feels conservative.


I think i've set this up correct but for those who remember my b2b 100-1000x calls, give me a follow.
Castle is officially out of retirement and I'll be using @Pumpfun to share my plays.
pump.fun/u/frankcastle

i will legit pay someone to help me get set up on the @Pumpfun app, I've been so out of the loop but for those who know me from back in the day running up e/acc from 14k to 40m, blinks 12k to 30m, moodeng from early and many more. the list goes on for the amount of 1000x+ i've fed over the years.
IRL projects got in the way the last year or so but I'm coming out of retirement for the rest of this year (for now)
someone help me pls set this shit up so i can make you all $$$$$$$$
how does one do callouts if it's not available in their region?
I have a UAE number and set my app store to UAE but it won't let me download the @Pumpfun app, says restricted.
@a1lon9 or anyone with any tips or way around this would be greatly appreciated please.
I'm ready to come out of retirement and run up 1k to 1m

The amount of payout's PF are paying out for callouts on the PumpFun app is absurd.
Can't wait to see this multiply over the next few months once market goes up.
If you don't think ur regular normie will see this and want to join the PF app, ur coping.
People go where they are incentivised and currently in a mid market, this is what PF are paying out users.
Everyone will be in the trenches.

Frank Castle (m/acc) 💀 retweeted

The benefits of abundant intelligence will accrue far outside of San Fransisco.
Spent the last year writing about capital, sovereignty, and the coming reordering of economic power.
THE COMMANDING HEIGHTS
Commanding-Heights.com

Frank Castle (m/acc) 💀 retweeted

$ZEC is an extremely misunderstood asset, which is why there's still so much upside left.
ZEC started to bottom around April 2025, when @ebfull shared a blog post about Project Tachyon. Tachyon makes Zcash quantum proof and paves the way to scale Zcash to 50k TPS. And you cannot address quantum without addressing scalability since post-quantum cryptographic signatures are going to be an order of magnitude larger.
At the risk of sounding hyperbolic, the real bull case for Zcash is to fulfill Satoshi's vision: becoming peer-to-peer electronic digital cash. What many Bitcoiners gave up on. Zcash has the same properties as BTC, except it has a credible roadmap to scale to 50k TPS at the base layer, with built-in privacy. It's extremely ambitious, but that is the vision.
At the same time, I expect Bitcoin to undergo a crisis of confidence. Crypto participants have been conditioned to blindly believe BTC will hit new highs every couple of years. I believe these assumptions will be challenged as the quantum overhang looms large, and continued underperformance will drive more flows into ZEC. I would not be surprised if BTC trades like ETH last cycle.
Peter Thiel talks about the "Last Mover Advantage." That is, it's far better to make the last great development in a market and then dominate. Facebook vs Myspace. Google vs Yahoo. Zcash has dominated a small niche (privacy), and then it plans to scale to the ambitious goal, which is peer-to-peer electronic cash.
The ZEC trade closely resembles the SOL trade last cycle. ZEC's ability to move fast challenges a slow-moving incumbent (BTC), similar to how SOL challenged the ivory tower of ETH. History doesn't repeat, but it often rhymes.
There’s a fundamental mismatch between why Zcash is going up (Tachyon + last mover advantage) and the broader market’s understanding ("just a privacy coin"). Understanding this is a form of alpha/edge. I expect this knowledge gap to close when Tachyon hits mainnet in Q1 2027.
As a result, I expect the following over the next 1-2yrs:
1) Bitcoiners will start "silent quitting" and begin hedging their holdings with ZEC
2) Capital allocators that may have full ported BTC 5 years ago, will buy both ZEC and BTC as a bet on a sovereign SoV
3) Smart crypto developers to move on from other ecosystems to start contributing to Zcash
4) As ZEC continues to outperform BTC, people will start to seriously entertain the possibility of a flippening
5) $20,000 ZEC
Zigher.


How Zcash Flips Bitcoin This Cycle
0:00 $ZEC flipping BTC?
1:20 Second Mover Advantage
3:41 Project Tachyon: Path to 50k TPS
5:39 How To Think About Zcash
13:05 How Zcash gets to $20k
15:13 Their Bias is Your Opportunity

Frank Castle (m/acc) 💀 retweeted

where do i send my money




Frank Castle (m/acc) 💀 retweeted

in the next 18 months:
- we solve cancer
- we restore fertility
- eliminate rare diseases
- we stop neurodegeneration
- we crack autoimmune disease
- make personalized medicine cheap
- fix genetic diseases at embryo level
proudly sponsored by bio/acc
