
Exploring the nexus of tech, finance, law, AI & global affairs | Decrypting hidden histories | Pioneering digital finance | Advocating for ethical health tech
USA
Joined January 2012
- Tweets3.9K
- Following877
- Followers2.6K
- Likes131K






Metaman retweeted

Why we’re not selling $IREN
$IREN has been through several brutal selloffs this year, and we (business partner & I) have held through every one of them, many of you alongside us.
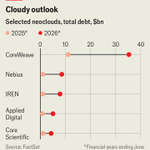
In October, fears around $CRWV's debt dragged the whole neocloud sector down, even though $IREN's position looks nothing like $CRWV's.
$IREN owns $6 billion of data centers built entirely with equity, with no debt against them, which now gives the company an excellent pool of assets to borrow against in a more selective credit environment.
Then came the fallout from the U.S. midterms, where Democrats made historic gains and several high-profile winners campaigned on tighter restrictions around data center development.
Texas was the biggest shock, electing its first Democratic governor since 1990, which spooked the market and hit Texas-heavy data center developers like $IREN especially hard.
Ironically, the new governor’s legislative proposals could end up creating a form of regulatory capture that favors experienced operators like $IREN. Nothing in the proposed changes looks like something $IREN couldn’t deal with, and in practice they appear far less radical than many are making them out to be.
The company has spent years building strong relationships with the local communities it operates in and can absorb more red tape far more easily than smaller, less experienced players. All 2 GW at Sweetwater are already locked in, and the first 1.4 GW are connected to the grid.
Last week, the selloff intensified again for reasons that had little to do with $IREN itself...
$NBIS's weak guidance, driven in part by delays at third-party colocation sites, and Jensen Huang’s resignation at $NVDA pulled every AI infrastructure name lower.
In the middle of it all, $IREN reported what looks to us like its strongest quarter yet. It contracts keep getting better, with older H100 GPUs re-signed on multiyear terms at double their original price and a new five-year contract at $22 million per MW.
It’s also becoming increasingly clear that customers are willing to prepay substantial portions of their contracts upfront, in some cases enough to cover most, if not all, of the GPU capex on their own.
That makes the funding fears from just a month ago look increasingly overblown, especially for $IREN, which still has plenty of 2027 capacity left to contract and therefore retains the flexibility to push for larger prepayments if financing conditions demand it.
Asked in a recent interview whether $MSFT's pullback from neoclouds had touched $IREN, chief commercial officer Kent Draper answered “No, we haven’t been subject to any of that”, and called the gap between demand and the share price a “very big dislocation”.
These selloffs cost us as much as anyone, because every dollar we have invested across our portfolios is in $IREN, personal savings and Agrippa’s company funds alike. Still, we haven’t reduced our position through any of this, and if anything we’ve added to it.
If you’re newer to investing, we know how difficult it can be to sit through periods like this, yet they’re where long-term returns are made and where most people sell.
You don’t need to be all-in like us. Size a position you can sit through, because the payoff goes to those still holding when sentiment turns.
We’ll keep doing the work and keep you posted every step of the way, starting with our next deep dive, “Did $IREN Just Win the Neocloud Race?”, out in the coming days.
Since I’m certain this post will age like fine wine, for accountability purposes, $IREN is trading at $16.28 at the time of posting.
And for anyone reading this today with doubts, I encourage you to bookmark this post and come back to it a few years from now.
Not financial advice, cheers! 🫶
Metaman retweeted

Scaling AI starts with infrastructure built to keep up. ⚡
@IREN_Ltd is expanding its 100% renewable-powered data centers across North America with @Lenovo ThinkSystem servers.
The impact? High-performance computing to tackle demanding AI workloads and help IREN stay ahead in the rapidly evolving cloud services market. 🚀
Discover more: spr.ly/6014ByyxVM
#SC26
Metaman retweeted

Brian, Kent's right, and if anything 7 years may be generous. Our view is new grid-connected power for data centers is largely closed across the western world unless you're already a long way into development. And even then, a lot of what's sitting in queues today won't get built.
The question we keep coming back to is what a project has to give back, to the grid and to the town around it, for people to want it there.

I know Kent personally. He's a real talent for $IREN and the AI infrastructure industry. I always listen when he talks to understand the inner loop where IREN plays.
When he says development timelines have stretched from 2 to 3 years to 7 plus in most jurisdictions. The bottleneck isn’t capital or GPUs it’s the multi-year process of securing land, power, and permits. Companies that started building that pipeline years ago have a structural advantage that can’t be compressed or bought later. That’s the game IREN is in.
Metaman retweeted
$NBIS running late in Vineland ($MSFT contract)...
Before I give you my breakdown of this topic, let me make one thing clear. This isn’t me taking a victory lap on behalf of $IREN investors.
$IREN is down 59% YTD, while $NBIS is still up 24%.
That said, I’m a fundamentally driven investor with a long-term perspective, which is the angle I’ll be taking here.
I’ve long preferred $IREN over $NBIS, and still do, largely because of the companies’ very different approaches to expansion.
$IREN took a bottom-up approach, locking in secure, grid-connected power years in advance while you still could, and subsequently building 100% of its data center footprint in-house.
$NBIS, in contrast, has relied heavily on leasing data center capacity, also called colocation, from third-party developers, which in large part explains why it was able to scale this quickly over the past ~24 months.
The problem with a colocation-heavy approach is that it’s inherently less reliable, since much of the development process sits in the hands of third parties.
$NBIS is now learning that the hard way, with its colocated Vineland site, used for its $17.4B $MSFT contract, running into severe delays.
In fact, the delay is so significant that the full deployment has been pushed back from a year-end deadline toward Q2 of next year. In other words, up to half a year.
Management now expects just over half of the $MSFT capacity to be delivered by year-end, causing full-year revenue guidance to slip from $3.2B to $3.1B at the midpoint, while the $7–9B year-end ARR target has been reduced to ">$7B" and pushed to February.
Ironically, $IREN's own >$4B year-end ARR target has also just been pushed toward January / February amid a delay in its contracted $MSFT capacity.
On the surface, these two situations look remarkably similar, yet they could hardly be more different.
$IREN's delay was caused by a request from none other than $MSFT itself to make a networking design change mid-buildout, just months before delivery, with supplier timing adding to it.
And with $IREN being “here to say yes to customers, not no,” as Co-CEO @danroberts0101 put it, they obliged and absorbed a 1-2 month delay.
$NBIS's delay, on the other hand, is being caused by the third-party developer behind Vineland, DataOne, which is now responsible for a slip of 2 quarters.
$NBIS CEO Arkady Volozh said so himself:
“This is one of the sites which we build not ourselves directly, but with the help of third-party constructors. As you can expect, many more things may go wrong in such sites.”
More specifically, this delay was caused by the inability to secure power generation in time.
Vineland is a behind-the-meter (BTM) project, meaning the power is not grid-connected but instead relies on on-site generation.
The problem with that approach, as I have repeatedly explained over the past couple of years, is that generating hundreds of MW of power from gas comes with a massive amount of baggage and strings attached.
DataOne found this out last December, when the NJ state issued a notice of deficiency on its application to run 32 “Bergen” gas engines around the clock to power the site.
In plain English, the permits weren’t coming any time soon...
The state followed up in January by questioning whether the site should be permitted together with a neighbouring business, which could have meant far stricter rules, and by March DataOne was telling regulators it was exploring alternatives.
Also notice that DataOne only filed that application three months (extremely late) after $NBIS signed its $MSFT contract, which shows how vulnerable you become when you rely on third parties.
The site’s main problem to begin with is that it sits right next to homes and farmland, which makes local approvals far harder to come by.
DataOne and $NBIS then shifted strategy in May by contracting Bloom Energy ($BE) fuel cells, a much “greener” but also costlier option, to save the project.
With no permits in hand and such a drastic change of strategy just a couple of quarters before the deadline, I knew Vineland wouldn’t be fully ramped by year-end.
I called that out at the time, and took a lot of pushback from $NBIS bulls for it.
I wasn’t alone in that either, as @FransBakker9812, @jiahanjimliu and @ilzmcfly followed the Vineland story closely throughout the year and did excellent coverage on it, flagging the warning signs as they came up.
Management’s official reason is that DataOne unexpectedly shut off its gas engines amid the transition to Bloom Energy fuel cells.
However, anyone with a brain could have seen that coming...
DataOne had been running those engines without air permits since late 2025, and by the summer the state was closing in.
In late August, DataOne told regulators it would start phasing out engines, and in September the NJ DEP fined it $1.07M and gave it 45 days to apply for permits. DataOne is still contesting both.
I find it a bit ridiculous that $NBIS management insisted for months after the $BE announcement that Vineland was still on track for year-end delivery. In effect, they were counting on DataOne running unpermitted gas engines until the Bloom capacity was fully installed.
Either that, or they were ignorant of the fact that DataOne had no permits, which would arguably be an even worse look given that this information was publicly available.
Whatever the reason, this is a bad look. No other way to cut it.
In aggregate, this entire fiasco sums up the $IREN thesis.
Developing your own sites, being your own landlord, and having a >5 GW pipeline of secured grid power, alongside >35 GW of additional early-stage pipeline, means you don’t have to rely on sketchy third-party developers that don’t even have secured power.
Now, to be fair, $NBIS is fully aware of this and is actively moving away from the colocation-heavy model, having started construction on multiple self-owned data center projects.
For anyone interested in learning more about that, I recently covered its site portfolio, along with the potential strings attached to the individual projects, in a dedicated $NBIS deep dive for subscribers.
In any case, given that $IREN has severely underperformed $NBIS this year, this isn’t a “gotcha moment.” Anyone who held $NBIS from the beginning of the year has done better, so congrats on that.
But I believe now is as good a time as any to take another look at $IREN if you haven’t already.
There is a lot to look forward to in 2027, which I’m very excited about.
Thank you for reading, cheers!

Metaman retweeted

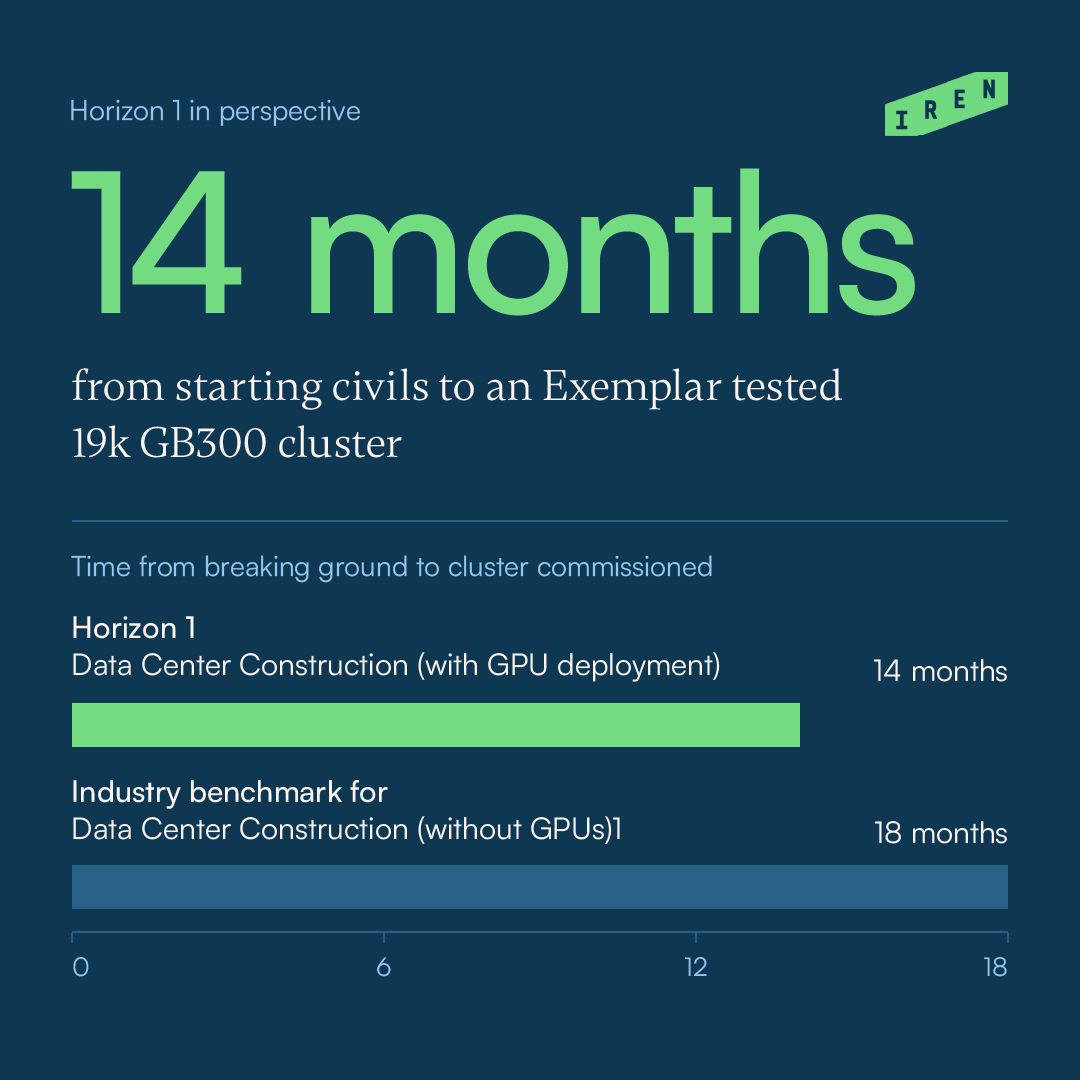
22% faster delivery than the industry benchmark.
Horizon 1, the first of four 50MW (IT) AI Cloud deployments for Microsoft, went from starting civils to an NVIDIA Exemplar Cloud-tested GB300 cluster in 14 months.
IREN's vertical integration delivers end-to-end control across design, engineering and construction, so contracted capacity reaches customers sooner.

Metaman retweeted
$IREN: The Days of Endless Dilution Are Coming to an End
Against the roughly $6B of CapEx $IREN has yet to fund for FY2027, the company has access to $12B-$15B of NON-DILUTIVE funding sources.
Personally, I think the vast majority of that CapEx will ultimately be funded through customer prepayments and GPU financing.
GPU-backed debt in particular is one of the more lender-friendly forms of financing, since it is supported by both the cash flows from the underlying customer contracts and the GPUs themselves.
So even in a more challenging financing environment, I don’t believe securing GPU-backed debt should pose a major challenge for $IREN. And if it does, the company has plenty of other non-dilutive sources of capital at its disposal.
In any case, Thursday’s earnings call made it clear that $IREN is better capitalized than ever and no longer has to rely almost entirely on equity-related sources of capital to fund its growth.
It’s also worth taking a moment to appreciate what all that dilution, which caused plenty of investor grief over the years, actually bought shareholders.
By the end of FY27 in June, management is guiding for the business to own roughly $10B of data center assets.
Those assets can now be borrowed against to help fund the next stage of growth, creating a much more capital-efficient financing flywheel as the infrastructure base expands.
The days of heavy dilution are truly coming to an end.
I wouldn’t be surprised to see $IREN begin buying back shares as early as the early 2030s.

Metaman retweeted

There's no shortage of $iren coverage so I'll keep it brief.
@danroberts0101 and team had arguably their best earnings call since I first bought shares in fall of 2024.
I'm glad they went off camera to draw less attention to their body language and IR put together a sexy presentation that showcased the effectiveness of the operations.
$msft requested a change order and like a good partner, the team obliged. Plenty of FUD regarding this very topic and I'm glad the team hit the topic head on.
My favorite slide below. After creating controversy last quarter over $25-30B of cap ex, the team did a much better job of explaining how they have adequate funding sources of approximately 2x the funding gap of $6B before issuing more equity or convertible debt. Less dilution!
I believe that over 35 GW of pipeline may present opportunities to lease or sell powered land to maximize shareholder value as the company can only build so many DCs on their own but time will tell.
For now, I can acknowledge after the 90% prepay and $22m/MW deal announced that cloud remains viable and the funding slide in particular put my mind at ease with respect to equity issuance.
The frustrations of 2026 appear to almost be in the rearview mirror as 2027 looks to be the best yet.
Don't let the macro or price action fool you; the company has a strong balance sheet with adequate funding sources to allow the share price to recover and even create new highs as the company scales its cloud business.

Metaman retweeted

WHY WOULD YOU BUY $IREN TODAY AFTER THEY ARE A HORRIBLE COMPANY DOWN OVER 80% FROM HIGH'S
They are now trading under a 1 price to cash
They are trading at 0.50 my projected 2028 ARR
They are trading at 1.73 Price to book value
IF THEY GOT LIQUIDATED TODAY WITH THE ACTUAL VALUE OF THEIR ASSETS THEY WOULD BE BOUGHT FOR 3-4X MARKET CAP
they are bringing on 500 mw in 2028
at 20 million per mw is 10 billion ARR+ 4B from 2026
OUR MARKET CAP IS HALF OF THAT
The are vertically integrated so they will have higher margins and be announcing huge deals soon.


Metaman retweeted

$IREN’s co-CEO’s have been copping it from everyone…..
BUT THIS 👇 IS MAX CONVICTION!! 🔥🔥🔥
PS. @MirantisIT did the same! They took their acquisition payout in IREN shares 💪

$IREN's two founders just took their pay in shares they cannot touch for six years. In the new proxy filing, co-CEOs Daniel and William Roberts each received 9.1M restricted shares, vesting over four years with a two year hold after that, and no new equity grants for the CEOs through 2031.
The same filing asks shareholders to approve settling the convertible hedges in shares, up to 149.9M shares through capped calls, so dilution gets offset instead of paid in cash.
The stock sits at $22, down 71% from its high, and the founders locked themselves in until 2032. Thursday they report. $IREN

ALT the word IREN in white letters on a bright green flag shape, on a dark navy background.

ALT Screenshot from IREN Limited's proxy filing. The section "2027 Co-CEO Staking Grants in Lieu of All Equity Incentives Until Fiscal 2031" states each Co-CEO was granted 9,099,328 TRSUs, vesting in four equal annual installments, each subject to a further two year post-vesting holding period, with no other equity grants during the vesting period, which ends in Fiscal 2031. The grant size, the two year holding period, and the Fiscal 2031 end date are highlighted in gold.
Metaman retweeted

🧵 $IREN: MUY BULLISH rumbo al earnings call. 🚀
1/6 — El precio va con retraso; la tesis sigue avanzando. Mi convicción está en los contratos, la infraestructura y la capacidad de convertirlos en ingresos.
2/6 — ARR confirmado: en agosto, IREN reportó US$4.000 millones de ARR contratado para capacidad de 2026 y US$1.000 millones ya operativos. El siguiente paso es activar lo contratado: requiere puesta en marcha y aceptación del cliente.
3/6 — La construcción va tomando forma a gran escala. Esta foto muestra la magnitud de la infraestructura. Horizon 1 ya fue entregado a Microsoft; la guía de agosto apuntaba a entregar H2–H4 en el cuarto trimestre. Quiero ver esa ejecución confirmada. 🏗️
4/6 — ¿Qué espero del call del 5 de noviembre, 5 pm ET? Avances concretos en H2–H4, crecimiento del ARR operativo, visibilidad de márgenes y financiamiento, y novedades sobre contratos y capacidad de 2027.
5/6 — ¿Por qué tan bullish? Energía, terrenos, centros de datos, GPUs y software dentro de una misma plataforma. Clientes contratados y una expansión que puede transformar la escala del negocio. Cada entrega acerca esa oportunidad a los resultados.
6/6 — Mi tesis: si IREN cumple las entregas y convierte el ARR en ingresos y márgenes, el precio terminará alcanzando los fundamentos. El mercado puede tardar; mi convicción sigue firme. ¡Ánimo, a ejecutar! 💪🚀
📸 Crédito de la foto: Frans Bakker.
Fuente de cifras: resultados FY26 de IREN, 27/08/2026.

Metaman retweeted

$IREN Mackenzie UPDATE:
Thermal imaging from 10/24 shows significant heat coming from data halls 4 and 2. All 8 segments of data hall 4 are showing enough heat to suggest commissioning. With fiber optics still being tied in, however, they are most likely not billing yet. As for hall 2, 6 of 8 segments are showing heat signatures and are most likely being commissioned, yet not billing since fiber optics has not been tied in.
Lots of work has been done since 9/23 footage was taken. I believe 3-4 halls could be online and billing before year-end.
Metaman retweeted

If you’re long $IREN, follow @g_duerksen. Early connection to PodTech, personal knowledge of the Roberts brothers, and clean analysis on the company’s setup and deals. Worth the follow.

From the day I met the Roberts brothers, it was clear they had a different arroach. It focused on positive and proactive community engagement. Making sure to take care of "the moms and dads".
@IREN_Ltd
Metaman retweeted
A lot of questions this week on funding, so here's how a GPU typically gets funded at $IREN.
First, the customer signs a multi-year take-or-pay contract and agrees to a prepayment. On our recent 3-year contracts, prepayments have been 45% to 55% of the associated GPU capex.
Second, financing is committed, secured by the contracted GPUs. On the Microsoft contract we secured an A-rated facility at around 6%, which together with prepayments covers 96% of GPU capex. More recently, for a non-investment grade counterparty at Mackenzie, we secured financing at 9% fixed, which together with prepayments covers more than the full cost of the GPUs.
That's the GPU side. The data centers are a separate, long-term asset base, and we own the ones our GPUs run in. Construction has been funded from cash to date, with no debt against these multi-billion dollar assets. As they come online with contracted customers, they can support financing in their own right.
The processes behind the next facilities are continuing, and new paper will cost what the market charges. With GPU paybacks of around two years on our recent 3-year contracts, a wider spread barely moves the economics.
There's more customer demand than we can build for. As we noted at our recent earnings, 2026 is largely sold out, recent 3-year contracts are at more than double the prior year's pricing, and demand for anything we can bring online in 2027 covers it several times over, with prepayments a focus in every negotiation. Conversations on 2028 capacity are already underway.
Meanwhile announced capacity keeps slipping across the industry, which is the point: signing deals isn't the bottleneck in this market, bringing GPUs online is, and that's our focus.
Metaman retweeted

On November 5, 2025 $IREN closed at an all-time high of $76.88. The next day it hit its all-time intraday high of $80.19.
It’s currently $29.80 - down 61% from its ATH. And still falling.
And here is all it has accomplished in that time. Markets are sometimes disconnected from reality.
🤖 Made with AI

Metaman retweeted
🚨 $IREN x Anthropic Leak
The Information, one of the best-sourced outlets covering the AI industry, just reported that Anthropic recently signed a cloud deal with $IREN.
For anybody who has followed management’s commentary closely over the past few weeks, this doesn’t come as much of a surprise.
First, $IREN announced a new contract with an unnamed “leading frontier AI lab” during its recent earnings call, followed by CCO Kent Draper revealing that the company in question was “1 of 2” possible customers.
While The Information didn’t disclose any specific MW amounts or terms of the deal, I believe it’s very likely that Anthropic secured the 50 MW of air-cooled B300 capacity coming online at $IREN's Childress site THIS year.
As for the economics behind the deal and where this relationship could go from here, we recently published an in-depth report for both our X and Substack subscribers covering exactly that.
I’ll link it below in the comments for anybody interested.
Wishing everybody a great rest of Sunday and a great start to the new week. Cheers!

Metaman retweeted

3. Summarizing.
So if the economics are so good, the pace of construction is predictable and solid, and GPU debt and customer prepayments are abundant and clear.
Why did $IREN not guide for a 2027 ARR?
My current take is that the company has underestimated the ability of the market to draw conclusions based on tools and data points that the company has provided.
It comes off as incredibly basic, but apparently the market needs IREN to spoon-feed it the outcome of the napkin math that you can get from multiplying the 0.5GW of IT load times the range of $20 - 25m per MW of revenue.
Behind the pretty pictures of OnlyFrans, there is a select group of people active to communicate with IR at IREN, to establish a better communication platform between the company and investors on X.
And make no mistake, there are a lot of institutional investors on X, but for the most part they like to remain anonymous.
Based on recent interactions, it's clear to me that management is aware of a few things, and for transparancy reasons I think it's important to share this with everyone here:
"Management acknowledged areas where disclosure can become more precise, particularly around operating capacity, future capacity, capex, and the relationship between capacity additions and revenue."
And further relevant to this post:
"Management agreed that IREN may continue to trade with sensitivity to interest rates and financial conditions while investors view the company predominantly through the lens of large near-term capex requirements."
Clearly the market needs better education from IREN, more precise disclosures, and not an isolated capex chart, without giving acompanied indicative ARR figures.
To be honest, IR has improved a lot in the last 6 months, and the addition of Bob Chen and Chris Sailer to the team have been incredibly valuable.
Here is my current overview of the company and associated investment thesis:
1. Execution risk is present, but delivery is underway. Seeing very frequent construction updates around the portfolio has definitely helped with predicting the outcome.
2. Financing is turning into a low-equity story, and with ABF coming into the equation, the longer this capacity shortfall prolonges, the better it is for spinning up a powerful flywheel for this.
3. The company has shown to be willing to improve their communication, and via IR, has demonstrated the ability to do better.
4. Corporate governance is a point where many X investors disagree on, and so I will not dive into that here. For now I see this as a temporary concern, but as long as the company delivers on their roadmap, I think this topic will fade into the background.
Furthermore:
- Horizon 2 will be delivered this month, I personally expect a handover to be imminent, and a subsequent acceptance shouldn't be far out.
- Horizon 3 is not far behind, I'm hoping for a completion by early November, acceptance before the end of the 3rd week of November.
- I am going to include Sweetwater 2, $CIFR barber lake, and a Crusoe data center for $META, to my coverage. If you're interested in joining, or have a question, leave a comment.
- I will not further comment on the SemiAnalysis piece. There is nothing more to say, IREN will have to figure it out with them. Needless to say, IREN should be judged based on their actual managed service contracts, and now Mirantis is on board, I expect the $NVDA contract to be a piece of cake. Just as with the construction and financing, just delivering on those managed services contracts will show who was right.
I am also very excited to have found out a couple of things about the new cooling tech that IREN is implementing in Childress, and I suspect this will further help them to become more efficient in PUE, and faster in deployment of the hardware.
John Gross is an absolute final boss, and he will do great things for IREN, mark my words.
To close it off, here is the proof that the network core building for Horizon 5 and 6 is underway, and I can also confirm that Horizon 3 has received its first batch of GPUs.
The stock is on a discount.
Non of this is financial advice.
Long $IREN

Metaman retweeted
$IREN's insane profitability
Despite $IREN trading like a turd these days, the underlying fundamentals are actually improving drastically.
One of the most underrated developments is the sharp improvement in profitability. $/MW contract terms have more than doubled since last year, while most project-level operating expenses have stayed relatively flat.
That is creating very strong operating leverage. While revenue per MW has 2.4x’d, pre-tax profit has increased by roughly 12x.
The graphic below shows this pretty well.
During $IREN's last earnings call, management revealed that recent contracts were being signed at rates of >$20m/MW.
However, at the follow-up Goldman Sachs conference, CCO Kent Draper disclosed that the company’s most recently announced contract was priced at $23m/MW.
I assume that was the “leading frontier AI lab” contract management announced during earnings, which I believe to be Anthropic.
Now, the $12m/MW pre-tax profit figure implied by that $23m/MW headline rate already accounts for financing expenses, depreciation and the direct expenses associated with the deployment, in line with the company’s broader guidance.
What it does not include are SG&A, R&D and taxes.
However, once $IREN reaches sufficient scale, I think those >50% project-level margins are a pretty solid indication of where GAAP net income margins could ultimately trend towards.
Interestingly, with current negotiations now taking place around the $25m/MW range, according to management, margins appear to be moving even higher.
Most of that additional $2m/MW should fall straight into the pre-tax project profit pile, since the underlying cost base stays largely fixed.
A major advantage $IREN has here is that it doesn’t have to pay colocation fees to rent third-party data centers, since the company develops and operates its own facilities.
With colocation pricing rising sharply, that gives $IREN another meaningful advantage over competitors that have to absorb those rental costs every time they bring new capacity online.
TLDR: Don’t get distracted by noisy price action. Keep your eyes on the fundamentals.

Metaman retweeted

$IREN
In 90 days, Mackenzie should look very different.
One site:
- 80MW of operating gross megawatts
- 70MW of operating IT megawatts
- 32,920 NVIDIA B300 GPUs (and some GB300s)
Serving customers including:
- Higgsfield
- Fal
- Figure
- Prometheus
- Perplexity
- Others
And when fully ramped, that single site will produce approximately:
- $1,029,840,000 of revenue pear year
- $257,460,000 of revenue per quarter
- $85,820,000 of revenue per month
- $2,821,4790 of revenue per day
All those numbers just slightly more than Bitcoin was producing. 🤣
Don't say I didn't warn you.

MACKENZIE UPDATE: Thermal imaging of $IREN Mackenzie site (captured 9/23) is showing a quiet signature — and that's exactly what you'd want to see right now, not a red flag.
On the FY26 earnings call, Co-CEO Dan Roberts confirmed GPUs have been racked in the first two of Mackenzie's four air-cooled data halls, with the remaining capacity targeted for commissioning by the December quarter.
Racked ≠ powered on. Until compute load actually goes live, there's no meaningful heat signature or power draw to expect — no HVAC load, no occupancy heat, no active workloads. A "cold" thermal read at this stage of buildout is a construction-phase signature, not a delay signal.
Watch for the thermal profile to shift once GPUs energize. That's the tell that Mackenzie's ramp is underway. 🔧⚡
LOTS of progress has been made!
More thorough Mackenzie footage posts and pics to come. If you want to get site updates please like, follow and turn on notifications.
Metaman retweeted

$IREN CCO sets the record straight on the SA hit piece released yesterday. @SemiAnalysis_ is the shady and scammy TMZ of AI...
Well done @McnallieM 👍
xitter.cf/McnallieM/status/21032…
🦘🕐⚡🚀🤌

ClusterMAX 3.0: The Industry Standard GPU Cloud Rating System Returns
In gory detail: reliability, performance, support, pricing
—and, of course, security—
in our most thorough analysis of GPU cloud providers globally
semianalysis.substack.com/p/…
