

Wall Street Writer: Wide Moat Research and Seeking Alpha https://xitter.cf/t.co/DCJLTvT3sm
United States
Joined May 2009
- Tweets21.6K
- Following5.1K
- Followers23.3K
- Likes20.9K



$EGP is one of my favorite industrial REITs and just delivered another strong quarter!
$EGP continues to demonstrate why I favor high-quality Sunbelt industrial real estate.
📈 Q3 FFO/share +7.9% YoY
💰 Cash leasing spreads +20.6%
🏢 Occupancy approaching 97%
🚀 2026 FFO guidance RAISED to $9.61/share
🏗️ Development pipeline expanding, with 8.1% projected yields
📊 Cash same-store NOI growth guidance raised to +7.5%
Not everything is perfect. Development pre-leasing has softened, and CA remains a laggard.
But $EGP continues to demonstrate pricing power, disciplined development, and durable earnings growth.
This is what I call a SWAN (Sleep Well At Night) REIT.
Quality matters. Valuation matters. And dividends matter.
$EGP $PLD $REXR $STAG

$EPRT delivering again. 🏠📈
+3.6% after hours following Q3 results:
• AFFO/share +6% YoY to $0.51
• Rental revenue $157.8M — ahead of estimates
• 2026 AFFO guidance tightened to $2.02–$2.05
• 2027 AFFO guidance introduced at $2.10–$2.18
What stands out to me: disciplined underwriting in a changing cost-of-capital environment.
That’s exactly what I want from a net lease REIT: steady growth, disciplined capital allocation, and no need to swing for the fences.
$EPRT remains one of my favorite net lease REITs.

I may be the only analyst on @SeekingAlpha with a SELL rating on $MRP, and there's a reason...
Years ago, I covered American Realty Capital Properties (ARCP). The yield was attractive, but something didn't smell right.
I called it my “sniff test.”
Elevated payout ratio. Governance concerns. A troubling history of external management.
I downgraded ARCP from BUY to HOLD.
About a week later, the company disclosed accounting irregularities involving AFFO.
My biggest regret? I should have gone straight to SELL.
Fast-forward to $MRP.
External management. Related-party transactions. Potential conflicts of interest. And a shift away from the original land-banking business model.
I'm NOT alleging fraud or suggesting $MRP is another ARCP.
But I've seen enough warning signs to make me uncomfortable.
This time, I didn't stop at HOLD. I went straight to SELL.
After 16 years writing about stocks, I've learned that protecting principal sometimes means walking away before you have all the answers.
A 13%+ dividend yield means little if your principal isn't safe.
Sometimes you have to trust your sniff test.
Happy SWAN Investing! 🦢

$ADC's acquisition pace may be slowing, but its fortress balance sheet and high-quality tenant base remain competitive advantages.
Q3 highlights:
✅ AFFO guidance raised to $4.585 midpoint
✅ Acquisitions of $309M at a 7.3% cap rate
✅ Approximately $2B in liquidity
✅ Net debt/EBITDA of just 3.9x
⚠️ Investment guidance trimmed to ~$1.6B
⚠️ Analyst price target cut from $84 to $74
Here's my takeaway:
In net lease investing, the cost of capital matters, but so does the quality of the capital allocator.
$ADC $O $NNN

🚨 WHO'S BUYING HOMEBUILDER STOCKS? 🏠
September pending home sales just plunged to an ALL-TIME LOW!
📉 Down 7.3% month-over-month
📉 Down 11.3% year-over-year
📉 Nearly 40% below September 2019
Meanwhile, homebuilder stocks are struggling.
2026 YTD performance:
$DHI: -6.1%
$LEN: -26.2%
$PHM: -5.4%
$NVR: -20.1%
$TOL: -3.0%
$KBH: -24.5%
$MTH: -11.3%
Higher mortgage rates, affordability challenges, and weak buyer confidence continue to pressure housing.
But remember: The best investment opportunities often emerge when sentiment is at its worst.
Is this a generational buying opportunity—or a value trap?
Who's buying homebuilders today? 🎯
Chart Source: Wolf Richter

🎯 Don't Paint All REITs with the Same Brush!
While investors obsess over $SPY and broad REIT ETFs like $VNQ, we focus on being SHARPSHOOTERS.
We target companies with:
✅ Fortress balance sheets
✅ Superior earnings growth
✅ Sustainable, growing dividends
✅ Best-in-class management teams
✅ Attractive valuations
Case in point: $CLDT - a Wide Moat Confidential recommendation, with shares up over 100% YTD!
We don't buy the REIT sector; we hunt for its winners.
That's the Wide Moat difference.
#REITs
(Click the link in my bio to sign up for the FREE Wide Moat Daily)


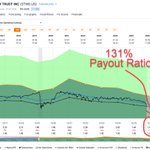
🚨$STWD is now yielding a whopping 16%!
But there's a catch...
📌 Dividend yield: 16%
📌 Payout ratio: 130%
📌 2027 consensus earnings growth: +28%
The dividend isn't currently covered by earnings, but analysts expect a meaningful rebound in 2027.
The million-dollar question: Can $STWD grow back to cover the dividend...or is a dividend cut inevitable?
At 16%, the market is clearly pricing in risk.
Who's willing to make that bet? 🎲
#REITs #Dividends

🚨 $PLD: Strong Earnings, Cautious Outlook, Attractive Valuation.
Q3 highlights:
✅ Core FFO: $1.60/share
✅ Occupancy: 95.6%
✅ Rent spreads: +38%
✅ Embedded NOI upside: $780M
✅ Data center pipeline: 5.8 GW
Higher Treasury yields are pressuring transaction activity, and management has raised its return requirements.
But here's the BIG PICTURE:
New construction requires rents 27% ABOVE current market levels to justify development.
That's a powerful barrier to new supply.
With approximately 20% annualized total return potential in our forward valuation scenario, I continue to see an attractive risk/reward proposition.
Short-term headwinds. Long-term WIDE MOAT.
$PLD #REITs #Dividends

I've written more than 4,500 articles on @SeekingAlpha, generated over 85,000 comments, and built a community of nearly 120,000 followers.
But it's comments like this one that remind me why I keep writing.
Not every stock pick has been a winner. I've had my share of mistakes, and I don't shy away from them.
My goal has never been to get every stock right; it's to help readers become better investors by focusing on fundamentals, valuation, and protecting principal.
After all these years, I still love researching businesses, sharing what I've learned, and engaging with investors who challenge me to think harder.
The greatest reward isn't the number of followers or articles; it's knowing that my work has made a difference in someone's investing journey.
To everyone who's been along for the ride, through the winners AND the losers, thank you.
Happy SWAN Investing! 🦢

America is making a potential $10 TRILLION bet on AI.
But here's what Wall Street may be overlooking...
You can build the RIGHT data center, in the RIGHT location, with the RIGHT customers...
And still lose your shirt if you finance it the WRONG way.
Just look at $CRWV.
I'm watching the infrastructure owners: $EQIX, $DLR, $IRM, $AMT, $CCI, $SBAC $BXDC
History reminds us that the railroads changed America, but many railroad investors went broke.
I'm not bearish on AI. I'm bearish on BAD BALANCE SHEETS.
🎥 Watch my latest episode of The Ground Up and tell me who you think wins the AI infrastructure race (link in the comment section below)
#AI #DataCenters #REITs #Investing


In March 2018, my friend @porterstansb made a provocative argument about $BRK.A $BRK.B.
In his book Warren's Mistakes, Porter questioned whether the investment discipline that had made Berkshire one of the greatest wealth-creation machines in American history was beginning to deteriorate. He even described Berkshire as "being badly mismanaged."
Those were fighting words, but I've known Porter long enough to appreciate that he isn't afraid to challenge conventional wisdom. Although I don't necessarily agree with his sweeping assessment of Berkshire, I've always believed that even the world's greatest investors deserve scrutiny.
This brings me to $LEN and $MRP...
I'll include the @SeekingAlpha link in the comment section below.


🚨 THE DATA CENTER DOOMSDAY SCENARIO
Larry Fink warns data center moratoriums could trigger a RECESSION.
Others predict today's data centers will become GHOST TOWNS.
And now we're told data centers are moving to OUTER SPACE. 🚀
I grew up watching The Jetsons, but I prefer investing in reality.
Here's what concerns me most:
Not demand. Not obsolescence. Not outer space.
It's the COST OF CAPITAL.
Look at $CRWV. Revenue is booming, but debt financing is becoming increasingly expensive.
That's why I prefer owning the infrastructure behind the AI revolution: $EQIX, $DLR, $IRM, and select cell tower REITs like $AMT and $CCI.
My latest @SeekingAlpha article examines FOUR doomsday predictions and explains where I see the greatest risks and opportunities.
I'm not bearish on digital infrastructure. I'm bearish on bad balance sheets.
$NVDA $AVGO $GOOGL
Long $DLR $EQIX $IRM $AMT $BX

🚨 $BRK.A keeps buying $LEN. I'm SELLING $MRP.
Here's why:
$LEN spun off $MRP as a land-banking REIT, and now $MRP is buying completed $LEN homes and taking on rental-property risks.
Meanwhile:
• Lennar's gross margin: 15.8%
• Stuart Miller's voting power at $MRP: 43.2%
• Estimated $MRP rental yield: ~5%, according to short seller Hunterbrook
I'm bullish on the long-term housing opportunity, but that doesn't mean I'm bullish on every homebuilder.
My preference? $TOL over $LEN, and $AMH or $INVH over $MRP.
Follow the money. Demand a margin of safety.
Stay tuned for my next @SeekingAlpha article:
Berkshire Is Buying Lennar, I'm Selling Millrose
$BRK.B $LEN $MRP $TOL $NVR
Long $TOL $AMH


