



Asxmicro retweeted

The Great Rare Earth Disconnect: Prices Up 23%, Miners Down 28% zerohedge.com/commodities/gr…

Asxmicro retweeted

🇺🇸US needed about 48,000 tonnes of rare earth magnets last year.
It made 300.
China makes about 94% of the world’s sintered magnets.
Now look inside a data centre.
The chips run on gallium, germanium, arsenic and indium.
The US imports all of each.
Rare earths for the hard drives: 80% imported.
Platinum: 85%.
Tin: 73%.
2 dates make this urgent:
On 1 January 2027, the Pentagon bans magnets with any Chinese, Russian, Iranian or North Korean step in the supply chain, from mine to finished magnet.
On 10 January, the US-China truce that paused Beijing’s toughest rare earth rules runs out.
China’s April 2025 controls never went away.
Dysprosium and terbium prices outside China have risen 4-5 times since then.
Money can’t close this gap fast.
US magnet capacity is on track for about 5,000 tonnes by the end of this year, barely 10% of demand.
Data centres, missiles and EV motors all draw on the same short supply.
Which comes first a new truce, or a real US supply chain?

Asxmicro retweeted

Do they worry about Lynas? No. Mt Pass? No. Has it stopped any REO project? No. Does it stop operations? No. Am I worried? No. Sorry if my No’s sound negative 😂. For me it is a walk in the park but I’ve been around this for +20 years.
Asxmicro retweeted
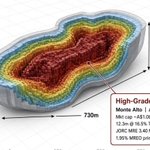
With 22 years in the rare earths space, this is the best grades and intercepts I’ve been involved with. I can only point to Mt Weld for equivalent grade interests. The operating mine!

Asxmicro retweeted
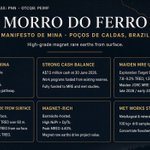
Here is my persepctive
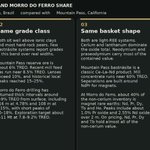
The comparison between Alvo’s Bluebush and Power Minerals’ Morro do Ferro puts considerable weight on Dy/Tb ratios and the apparent simplicity of ionic clay processing. That analogy needs context.
A percentage of the rare earth basket is not a grade per tonne.
Using the original post’s figures purely as an illustration:
• Bluebush: 1,300 ppm TREO × 3% Dy/Tb = 39 grams of Dy/Tb oxides per tonne.
• Morro do Ferro: 77,000 ppm TREO × 0.5% Dy/Tb = 385 grams per tonne.
That is almost ten times the contained Dy/Tb oxide grade despite the smaller basket percentage and before considering recovery.
Nor should light rare earths be dismissed as low-value material. Nd and Pr are light rare earths and central to permanent magnet production. Their contained and recoverable value belongs in the comparison.
Processing also deserves a more strategic assessment.
China established commercial ionic clay production, but historical ammonium-based in-situ leaching has documented water and soil pollution. A “Simple salt wash” therefore does not automatically mean low environmental impact or low commercial cost. Reagent management, water treatment, rehabilitation and downstream processing all matter. Has this been considered?
Serra Verde now provides a commercial ionic clay precedent in Brazil. That is significant but it does not establish Bluebush’s project-specific recoveries or economics.
Morro do Ferro offers a different precedent that reports valuable magnet rare earths that are predominantly hosted in bastnäsite (nil to cerianite), the principal rare earth mineral processed at Mountain Pass in the United States and primary mines in China.
Bastnäsite processing has an established industrial pathway involving concentration, leaching and separation.
Mining is about making money. Your comparison should begin with gross contained value per tonne: [Element-specific oxide grades × consistent oxide prices].
Then assess potentially recoverable value: [Contained value × element-specific recoveries through to a saleable product].
Finally, account for payability, operating costs, capital requirements and environmental obligations.
Gross in-situ value is not revenue, profit or a project valuation. But it is a more informative starting point than basket percentages alone. For supply-chain strategy, the decisive question is how much saleable Nd, Pr, Dy and Tb each project can deliver reliably and competitively.
I am not against clays but your comparing to very different processes.
By the way Morro do Ferro is tenured to a Mining Licence…….
#RareEarths #CriticalMinerals #Metallurgy
Asxmicro retweeted
Jim and the Liar in the Lodge can try and spin all they want.
Australians know life is getting worse under Labor.


Asxmicro retweeted


Chuck @ChuckChunder007 has been warning us for years about the high risk of $MEI and $VMM's project. No one listened
xitter.cf/ChuckChunder007/status…

