

concentrated investments & unwavering conviction 🌩️ @flashfundllc
Not financial advice
Joined April 2021
- Tweets1.9K
- Following540
- Followers2.4K
- Likes2.9K




are retweeted

Watching people freak out over CXMT's 4F² and claim that CXMT has caught up with Western memory technology is honestly laughable.
CXMT has hit the limits of DUV scaling. What it is trying to do is move from 6F² to 4F² at the relatively relaxed 13 to 14nm node so it can extend the life of DUV. It is not jumping straight to 4F² to leapfrog Western memory makers that use EUV. People have the cause and effect backwards.
Samsung and SK hynix are also not holding off on 4F² because they are stupid. If they wanted to mass produce 4F² right now, they actually could. The only reason they don't is that the yields aren't there.
I really can't make sense of this selloff sparked by CXMT. 🤡
$MU
Very ugly day and start to the week for Micron, it may just be a -3.8% day, but its never good to be under the psychological level of $1,000.
The main reason for the drop is that a major Chinese competitor, CXMT, announced they are making very fast progress on a new, highly efficient memory chip. They plan to release this new technology by the end of the year.
This news made investors worried that Micron will face tougher competition and that there could soon be too many memory chips on the market, which would drive prices down. This worry also caused other big chipmakers to lose value today.
In my opinion, this is such an overreaction from the market considering the shape Micron is in;
- Micron recently gave huge financial forecasts for next quarter, showing that demand and their ability to charge high prices remain incredibly strong.
- already signed contracts that guarantee the sale of over 75% of its entire production through 2027... these are guaranteed sales...
- The company expects the global shortage of AI memory chips to last until 2028, meaning they will have plenty of buyers for years.
- And talk is cheap... It is much easier for a rival to announce a new chip design than it is to actually manufacture millions of them reliably
This is just how these memory / chip stocks trade, the first sign of a new competitor or extra supply scales short term trades into selling first and actually doing research / asking questions later.


$MU is a big example of this
- revenue up 380% YoY, above estimates
- Gross margin of 87% (straight profit)
- Guided for $61 Billion 2027 revenue ($57B expected)
- Heavy long term commitments and supply-demand conditions extending into 2028
- Avg wallstreet price target of $1,630
And one of the best looking weekly / monthly bases on the market...
Don't overthink it. 🫰


$HPE & $DELL continue to show why they are 2 of my core holdings in my portfolio
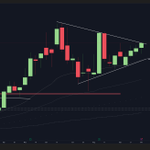
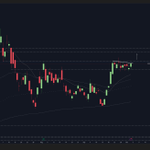
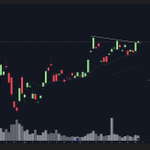
$HPE just broke out of another are of consolidation, I would expect this to continue to trend to $80+
$DELL bounced perfectly at the 8 week, uptrend still intact for a $600 test 🎯


are retweeted

JPMorgan sees memory supply remaining tight through 2028, with customer order discussions already extending into 2031.
Its estimates point to:
• HBM bit demand growth: +63%
• Non-HBM server DRAM: +37%
• CY27 HBM blended ASP: +54% YoY
JPM also believes Micron’s >35% revenue coverage under long-term supply agreements through 2030 could prove conservative, noting Asian memory peers have LTAs covering 50%+ of capacity.

are retweeted
MICRON $MU Q4’26 EARNINGS HIGHLIGHTS
🔹 Revenue: $54.23B (Est. $51.07B) 🟢; +379% YoY
🔹 Adj. EPS: $33.42 (Est. $31.61) 🟢
🔹 Adj. Gross Margin: 87.0% (Est. 86.1%) 🟢
Q1 FY27 Guide:
🔹 Revenue: $61.5B ± $1.5B (Est. $57.02B) 🟢
🔹 Adj. EPS: $38.15 ± $1.00 (Est. $35.40) 🟢
🔹 Adj. Gross Margin: ~86.25% (Est. 86.4%) 🟡
CapEx & Cash Flow:
🔹 Operating Cash Flow: $43.97B (Est. $34.47B) 🟢
Business Unit Revenue:
🔹 Cloud Memory: $16.28B
🔹 Core Data Center: $18.00B
🔹 Mobile and Client: $13.11B
🔹 Automotive and Embedded: $6.82B
Other Q4 Metrics:
🔹 Adj. Oper Income: $44.64B (Est. $42.41B) 🟢
🔹 Adj. Net Income: $38.40B (Est. $36.31B) 🟢
🔹 GAAP EPS: $32.87
Key Updates:
🔸 Quarterly dividend of $0.15 per share
Comments:
🔸 “Micron delivered record fiscal 2026 results, and we expect an even stronger fiscal 2027”

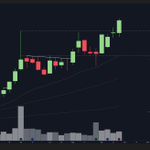
Bullish hammer candle on $STX so far today 👀

$STX Seagate Technology
- Massive bull flag on the weekly (extremely bullish pattern)
- Hasn't closed under the 20W EMA since April '25 (Year and a half of a powerful trend)
- Revenue up +50% YoY, $3.1B of FCF
- Apart of one of the strongest sectors out now
Weekly close above 945 and I expect a moonshot
PT: $1,100 🎯

