


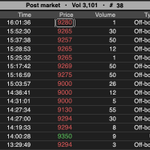





Yesterday's late trades have now been logged, adding a further 1,127 to the 6,283 already in the book
That means the final count for yesterday's volume was 6.6% of total shares traded (7,410 out of 111,112) 🤯
VERY encouraging signs
But something tells me there's MORE to come


I love that MORE is now trading.
The £100 target still lies above but we are now on our way there, and the track record is being built.
For interest, I've included a screenshot of the first five days of STRC.
Price was pretty equivalent at this stage of trading.


Two trading days later, and we've got a new ATH for volume in less than two hours of trading.
Over 2% of the shares of MORE (2,335/111,112) traded already today.
MORE volume.

A solid day.
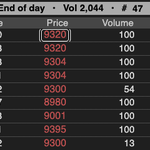
Final figures (aside from any late trades that may appear):_ 1.8% of the entire float (2,044/111,112 shares) of MORE exchanged hands today.
Liquidity continuing to grow.
MORE tomorrow.

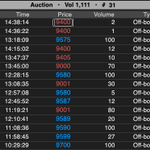
With nearly two hours of trading left to go, 1% of the entire float (i.e., 1,111 out of 111,112 shares) of MORE has official exchanged hands so far today.
Liquidity steadily growing.
Bullish.

If we hit 1,111 shares traded (latest figure = 916), that will be 1% of the entire float traded in one trading day.
And this is on only the second day of trading, with still only some brokers allowing access.
Positive steps.
Only halfway through the day, but we have already nearly doubled yesterday's trading volume on MORE, with over £50k of trades.
Starting from small beginnings but encouraging signs of liquidity beginning to build.
All this with only some of the brokers live for trading.


Really pleased to see MORE complete its first day of trading on the Main Market of the London Stock Exchange today.
Over £30,000 of MORE shares changed hands, with every buy trade taking place between £99 and £100, within 1% of the £100 reference price used to establish the initial 12% dividend rate.
Seeing trades at £100 is encouraging, although the spread remains wide as the market begins to establish where MORE should trade.
One of the potential benefits of a relatively modest initial raise is that we have built a shareholder base predominantly made up of investors attracted to the long-term income proposition, rather than those looking to take advantage of a discount and make a short-term trade.
Of course, time will tell, but I believe that is a good foundation from which to build.
It has also been great to see the support from our community, particularly those reaching out to brokers and investment platforms that do not yet support MORE.
This is a normal part of bringing a new equity to market. Access will take time, and as more platforms make MORE available, a broader group of investors will have the opportunity to consider it.
It was also a difficult day for SWC shareholders, with our Ordinary Shares closing almost 10% lower on over £1 million of trading volume.
Admission is the beginning. A listing does not automatically create a successful market, a sustainable source of capital or a widely understood investment proposition. Those things take time, communication, education and consistent execution.
Our focus remains on building both equities, scaling MORE into a much larger income equity, continuing to grow our Bitcoin treasury and operating businesses, and making disciplined capital allocation decisions that create long-term shareholder value.
We now have two distinct equities trading on the Main Market of the London Stock Exchange, each offering investors a different way to gain exposure to the future of Smarter Web.
There is a lot of work ahead of us and I could not be more excited about our potential.
We are only just getting started.
LSE: #SWC #MORE | OTCQB: $TSWCF | FRA: $3M8

MSTR/BTC ratio - nearly four months on.
Quoted tweet was the day MSTR/BTC bottomed (3x higher than the 2022 low).
Since then, it has continued to follow the 2022-23 pattern.
Look what lies ahead.
We all know BTC is going up.
MSTR will go up more.


I bought more SWC on this pullback by the way.
The post-disbelief pullback.
Hope is on the way. And a whole lot MORE.
LSE: #SWC #MORE | OTCQB: $TSWCF | FRA: $3M8
xitter.cf/ableinch/status/210596…


I was early to SWC (bought at 4.7p and was allocating more funds from June through August this year), and I have decided to get in at the IPO for MORE.
I don't need income but intend to support MORE by holding my shares and not selling.
LSE: #SWC | OTCQB: $TSWCF | FRA: $3M8


$SWC I'm up 137% on this tranche from early August.
Yet this is just the beginning.
My shares are locked away until the price is much MORE high.

SWC/BTC ratio.
And there we have it:_ Confirmation.
The weekly close is in. Break out and retest confirmed.
As @matthewkerridge would say, onwards.
£MORE

SWC/BTC ratio.
Following a recommendation by @matthewkerridge, I have updated to BTC in GBP rather than USD.
Interestingly, this makes for a much cleaner chart.
The break out and retest still awaits confirmation at the end of Friday but this is looking very promising.
MORE.

Here we go again.
$SWC first place as the highest riser on the FTSE All Share Index. Again.
Up over 20% today.
Notice by the way the 7 million views of this page on the London Stock Exchange website.
Volatility is Visibility.
LSE: #SWC | OTCQB: $TSWCF | FRA: $3M8


The new rules seem designed to push me to £MORE
Where do I put profits in the coming bull run?
- Can’t earn interest in stocks and shares ISA (taxed at 22%)
- Can’t transfer to cash ISA
- Don’t want to leave it idle
- Don’t want currency risk
MORE is the only realistic option

SWC Community:
Yesterday I wrote about Britain’s £360bn love affair with Cash ISAs.
But I missed perhaps an interesting bit…
From April 2027, the UK Government isn’t JUST reducing the amount that under-65s can put into a Cash ISA from £20k to £12k. (See “Anti-circumvention rules” per the link below - and p.s. your cash savings can’t just be hidden in a boating accident 🫣)
They’re also going to some lengths to make sure people can’t simply find clever ways around it.
This, I think, maybe makes the timing of #SWC’s proposed MORE Preference share even more interestng.
The overall ISA allowance next year is staying at £20,000. But only £12,000 of that can go into a Cash ISA from Apr 27.
So what happens to the other £8,000 if we want to use your full tax-free allowance?
Well, the Government clearly wants us to INVEST it. In the 2025 Budget speech then-chancellor Rachel Reeves described that £8,000 as being “exclusively for investment”.
But what about the millions of Brits I wrote about yesterday who seemingly REALLY don’t want to invest?
Could they just open a Stocks & Shares ISA, stick the other £8k in there as cash and collect interest instead?
Nope.
From April 2027, interest earned on cash sitting inside a non-Cash ISA will face a 22% charge. Collected through your ISA platform direct…
OK then…
Put the £8k into a Stocks & Shares ISA and buy a nice safe Money Market Fund instead?
Well, nope. HMRC has thought of that too.
A non-Cash ISA made up 100% of cash-like assets - specifically Money Market Funds - will become non-qualifying.
Fine. Put £20k into a Stocks & Shares ISA and then transfer it across into a Cash ISA?
Nope. Transfers from Stocks & Shares ISAs into Cash ISAs will also be prohibited for under-65s.
You CAN still transfer money the other way, from your Cash ISAs into a Stocks & Shares ISA.
Interesting asymmetry, that.
This isn’t an accidental side-effect of the policy either.
HMRC explicitly says these rules are being introduced to stop the £12k Cash ISA limit being ‘circumvented’ and to hit the Government’s aim of “encouraging retail investment”.
In other words…
The Government isn’t merely opening the door towards investing.
It’s attempting to usher reluctant UK savers through it.
This is where we wander back to #SWC and MORE.
Because there is an important little detail in HMRC’s new rules.
What DOESN’T count as a “cash-like” asset?
Individual shares.
Funds.
ETFs.
Corporate bonds.
Government bonds.
Gilts.
Actual investments, basically.
Now think back to those 14.4million people who held a Cash ISA but no other type of ISA.
These people are already signaling through their behaviour, what many of them appear to value:
Stability.
Predictability.
Income.
Liquidity.
Simplicity.
Government is about to effectively reserve £8k of their £20k annual ISA allowance for investments if they want to use the whole thing.
So what happens if, at almost exactly the same time, a new UK-listed investment exists which is deliberately designed to offer SOME of those cash-like characteristics…
…but which is actually an investment?
A security designed around par.
A predictable dividend.
Paid EVERY flipping week.
A yield potentially significantly higher than cash savings rates - an attractive rate as Andrew has signalled.
And, capable of sitting inside a Stocks & Shares ISA on the largest retail platforms for the UK.
The question then probably isn’t ‘Can MORE compete with a Cash ISA?”
It’s …what might those millions of reluctant UK investors choose when Government policy increasingly makes them choose between…
£12k in cash, and leaving part of their ISA allowance unused
OR
£12k in cash + putting up to another £8k into an actual investment?
What sort of investment might appeal to John Smith who’s never particularly wanted to become an “investor” in the first place?
Perhaps one deliberately designed to give them a little MORE of what they already like. 👀
gov.uk/government/publicatio…

SWC/BTC ratio.
Following a recommendation by @matthewkerridge, I have updated to BTC in GBP rather than USD.
Interestingly, this makes for a much cleaner chart.
The break out and retest still awaits confirmation at the end of Friday but this is looking very promising.
MORE.
